
Toxic debts is an informal expression for seriously troubled loans or debt-related investments. It often describes assets with deteriorating repayment prospects, uncertain values or little market demand. The term became prominent during the 2007–2009 financial crisis, particularly for complex mortgage-related securities.
It is not a standardized accounting or regulatory classification. A debt does not become worthless merely because its market price falls, and an asset described as toxic may still generate substantial recoveries.
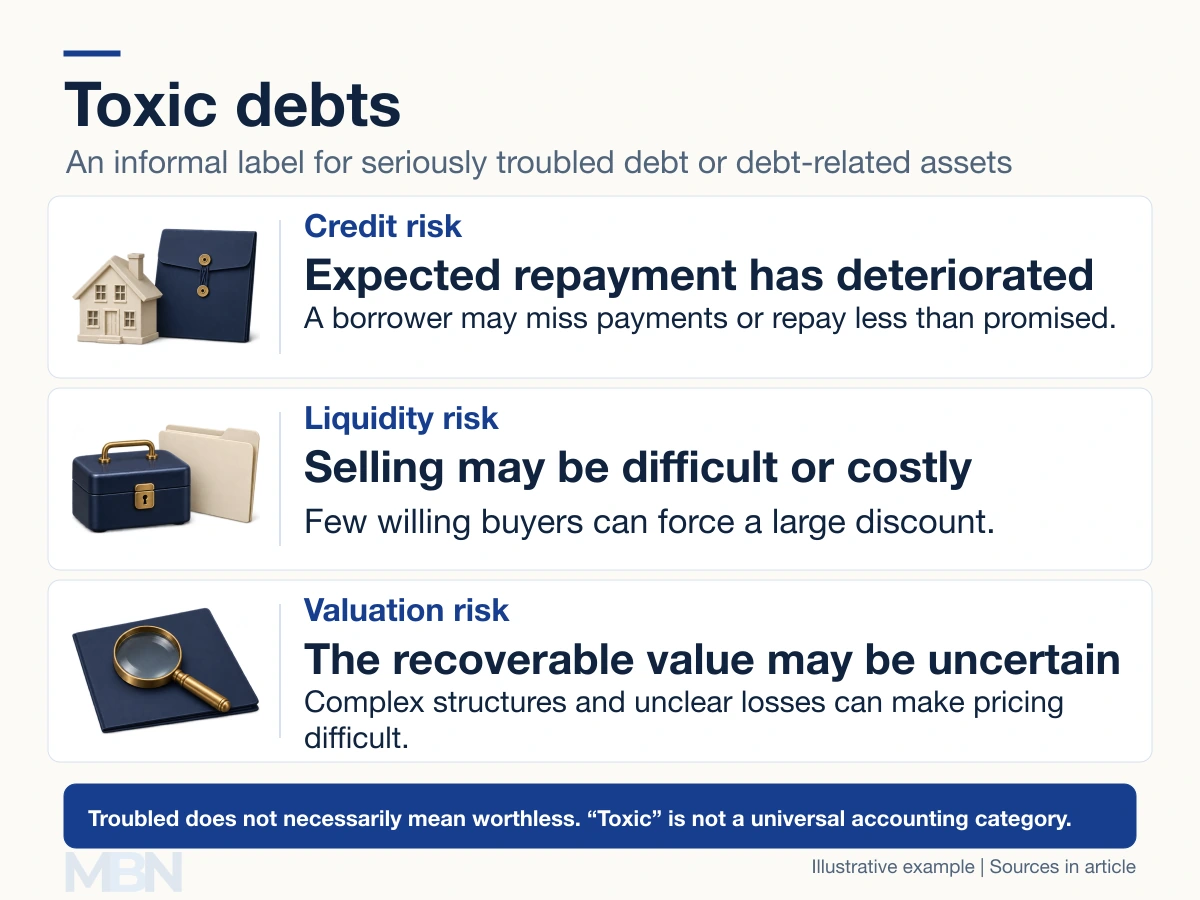
Three problems that can overlap
Credit risk concerns whether promised payments will be made. Liquidity risk concerns whether an asset can be sold promptly at a reasonable price. Valuation uncertainty concerns how confidently its worth can be estimated.
A borrower may still be paying while the investor struggles to sell the security. Conversely, an overdue loan may have valuable collateral that supports partial recovery. Nasdaq’s toxic-assets explanation emphasizes illiquidity, difficult valuation and the possibility of large write-downs.
Toxic debt and non-performing loans
A non-performing loan, or NPL, has a more specific supervisory meaning. The ECB explanation includes loans where repayment is unlikely or agreed payments are more than 90 days overdue. Detailed rules and materiality conditions depend on the framework.
Non-performing does not mean that nothing will be collected. Restructuring, future payments or collateral sales may recover part of the amount. Equally, a loan can become doubtful before it crosses a particular overdue threshold.
A recovery example
Suppose a lender is owed $100,000 in principal and estimates it will recover $60,000. The undiscounted shortfall is $40,000 before legal costs, collection costs and the timing of receipts are considered.
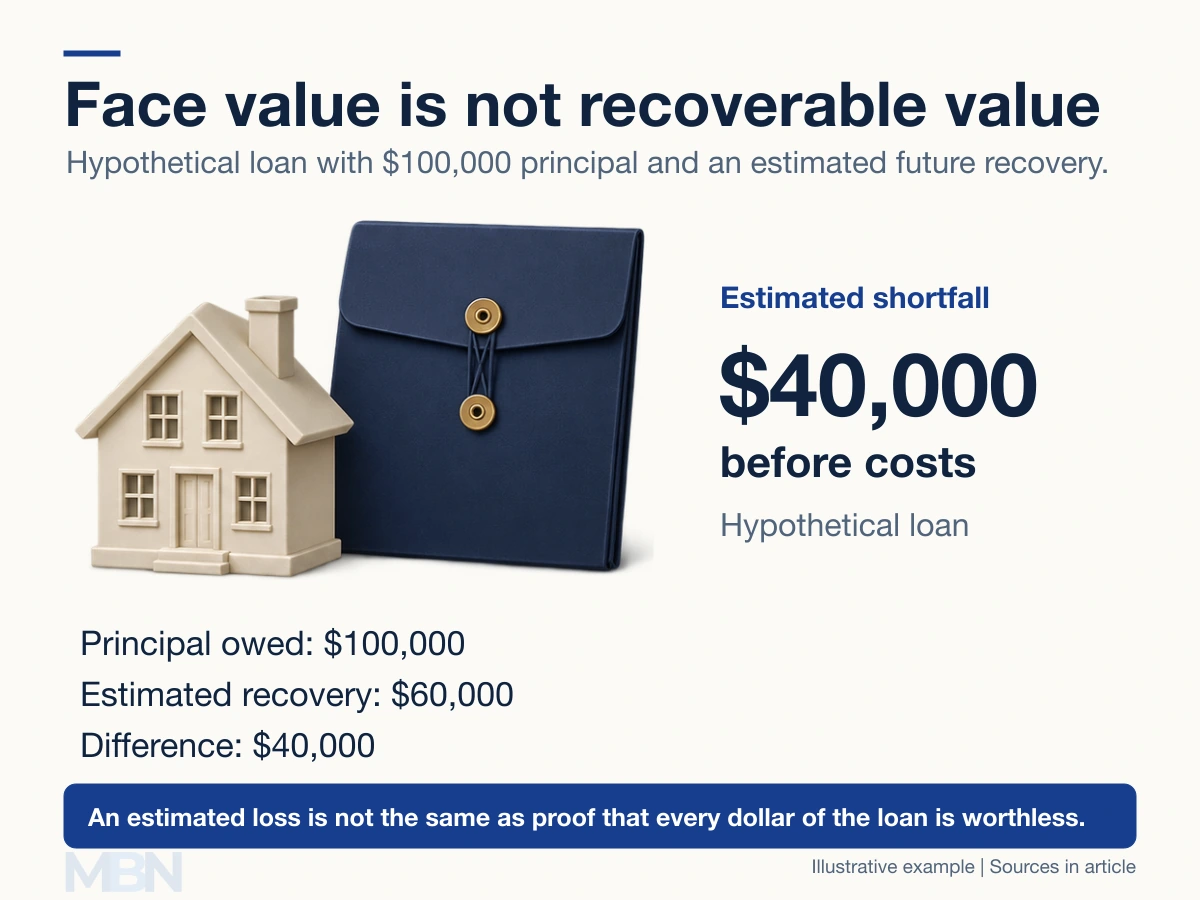
This is a simple loss illustration, not a complete accounting measurement. The amount recorded depends on the applicable rules, expected cash flows and other inputs. IFRS 9 includes an expected-credit-loss framework for relevant financial assets and credit commitments.
A purchaser might offer a different price because it uses different recovery assumptions, requires compensation for risk or expects a long collection process. Face value, expected recovery, carrying amount and market price are therefore distinct figures.
What happened in the financial crisis?
Mortgage-backed securities distribute cash flows from pools of mortgages. Collateralized debt obligations, or CDOs, can repackage exposures into layers with different priorities for receiving payments and absorbing losses. The structures were related, but they were not all identical bundles of directly originated mortgages.
The Federal Reserve’s subprime-crisis history describes how falling house prices, defaults, leverage and interconnected financing arrangements spread losses. Some assets suffered severe losses, while others retained value. Complex structures and uncertainty about exposures made confidence and trading conditions worse.
Treasury’s TARP history records emergency stabilization programs. Describing every CDO as worthless, or every crisis intervention as the same kind of asset purchase, obscures what happened.
Why troubled assets affect banks
Losses reduce earnings and can weaken capital, the resources available to absorb losses. Funding pressure and uncertainty may also constrain lending. The scale of the problem depends on expected losses, concentration, available capital and funding, rather than the use of a dramatic label alone.
Last checked and updated on November 11, 2026 by the MBN editorial team.