
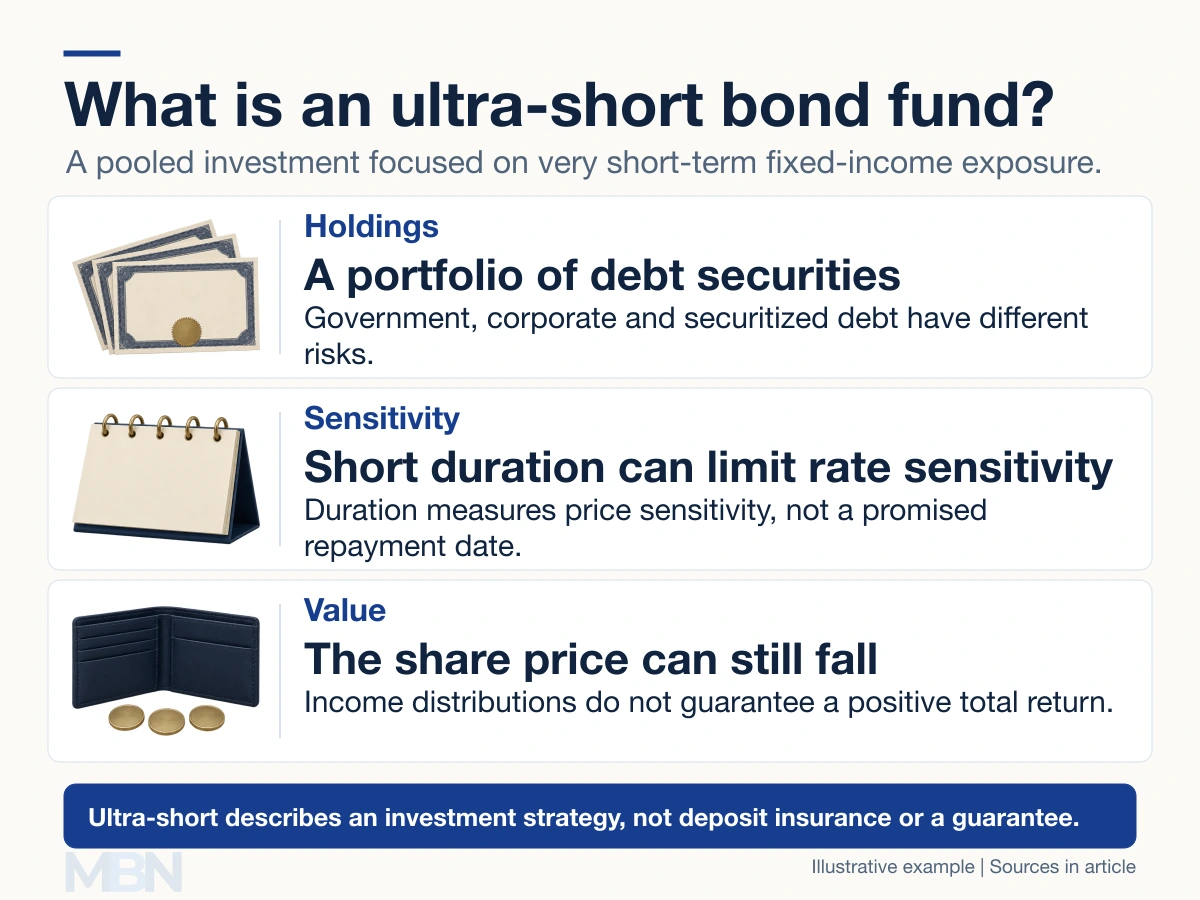
An ultra-short bond fund pools investors’ money in debt securities while seeking very short-term interest-rate exposure. It can generate income, but its share value can fluctuate and investors can lose money.
The Securities and Exchange Commission (SEC) explains that these funds can hold corporate, government, mortgage-backed and other asset-backed securities. Their names do not establish identical holdings, credit quality or maturity limits. The prospectus defines the particular strategy.
Maturity and duration are different
Maturity is when a security’s principal is due for repayment. A fund continually buying and selling securities does not necessarily have one maturity date at which an investor’s original capital will be returned.
Fidelity explains duration as a measure of sensitivity to interest-rate changes. Shorter duration generally means a smaller price response to a comparable rate change, with other factors held equal. It does not eliminate credit losses or guarantee that the fund will preserve capital.
How it differs from a money market fund
US money market funds operate under specific investment and liquidity requirements. Current Rule 2a-7 limits weighted average maturity to 60 calendar days and weighted average life to 120 days. These are portfolio measures calculated under the rule, not a requirement that every security mature within 60 days.
Ultra-short bond funds do not gain money-market-fund status merely by holding short-term debt. Their credit and maturity policies can differ substantially.
Investor.gov distinguishes stable and floating net asset values among money market funds. Most retail and government money market funds seek a stable $1 share value. Institutional prime and institutional tax-exempt funds have floating values. A universal claim that every money market fund maintains $1 is incorrect.
What can produce a loss?
Rising market yields can reduce the value of existing fixed-rate securities. Issuer default, deteriorating credit quality and difficulty selling investments at reasonable prices can also damage returns. The mix of securities matters as much as the ultra-short label.
The Federal Deposit Insurance Corporation (FDIC) excludes mutual funds from deposit insurance, including those bought through an insured bank. An ultra-short bond fund is therefore different from an eligible bank deposit. Lack of deposit insurance is not itself a forecast of a particular loss.
Income and total return
Suppose a fictional $10,000 holding falls to $9,850 and pays a $100 cash distribution during the same period. Without reinvestment, the shares and cash total $9,950. The investor has lost $50, or 0.5%, before taxes.
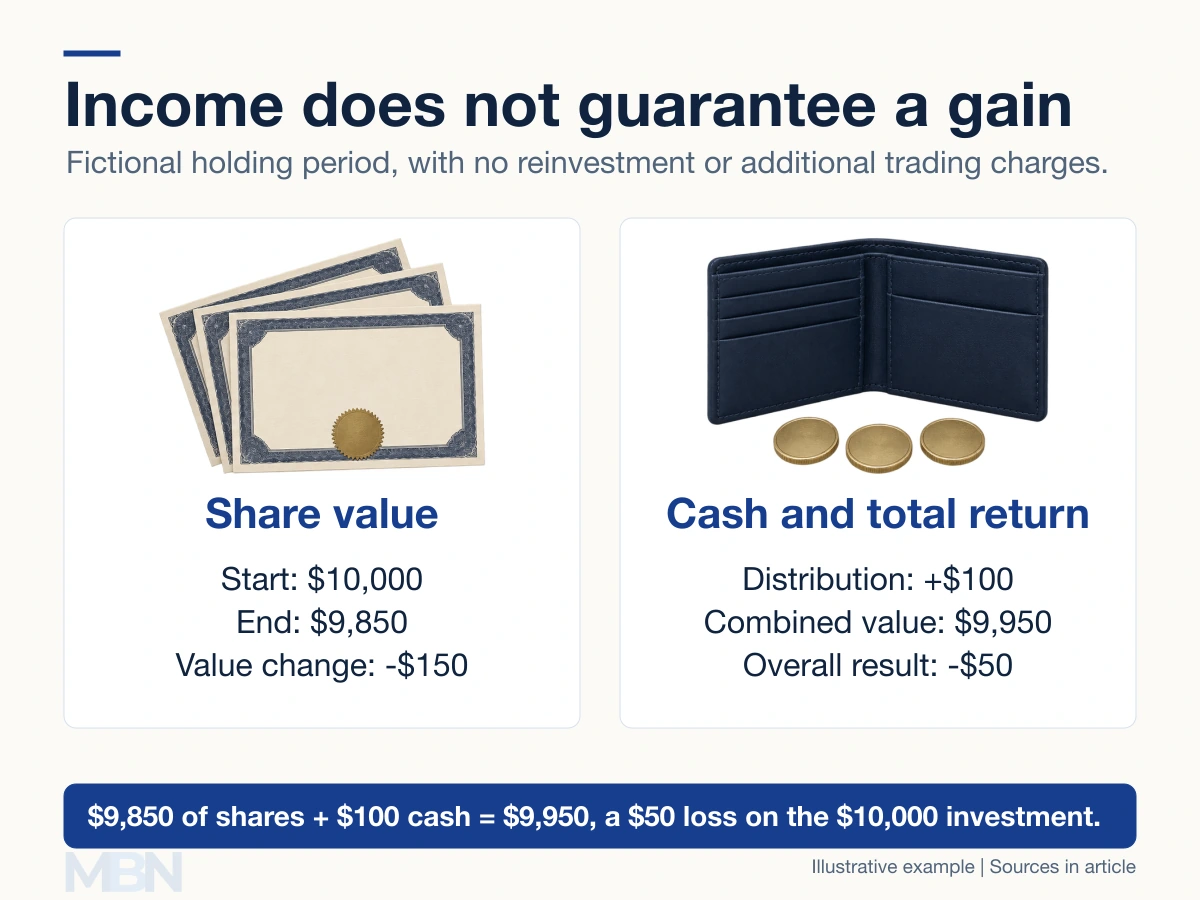
The example assumes fund costs are already reflected and there are no additional trading charges. A distribution yield alone would not reveal that overall loss.
Expenses and yields vary
There is no timeless expense-ratio range or guaranteed yield advantage for the category. The SEC’s fees guide distinguishes recurring operating expenses from transaction charges. An expense ratio expresses annual fund operating expenses relative to assets; it is not simply the manager’s fee.
A fund’s current fee table, holdings and risk disclosures explain the product more reliably than a generic label. Comparisons also depend on prevailing rates and the risks each fund takes.
Last checked and updated on November 4, 2026 by the MBN editorial team.