
An underlying asset is the asset or financial instrument on which a derivative is based. More broadly, an “underlying” can be a specified price, interest rate, exchange rate, index or other reference variable.
A derivative is a contract whose value depends on that reference. Shares can underlie stock options, wheat can underlie commodity futures, and a futures contract can itself underlie an option. An index or interest rate is a reference value rather than an object that can be delivered.
The underlying and the derivative are separate
The CFTC’s futures glossary describes derivatives based on securities, commodities, indices, other derivatives and agreed pricing arrangements. This makes “a security” too narrow as a general definition of the underlying.
Owning a call option on shares does not by itself make the option buyer a shareholder. The option creates contractual rights. Share ownership arises only through a separate share purchase or an exercise that results in delivery under the contract.
An option example
Suppose a hypothetical call covers 100 shares and has a $50 strike, meaning the specified purchase price. Its premium is $3 per share, or $300 for the contract. Assume it is held to expiration and ignore fees and tax.
If the stock finishes at $52, the call’s exercise payoff is $200: the $2 difference multiplied by 100. After the $300 premium, the buyer has lost $100. If the stock finishes at $60, the payoff is $1,000 and profit is $700. Expiration break-even is $53.
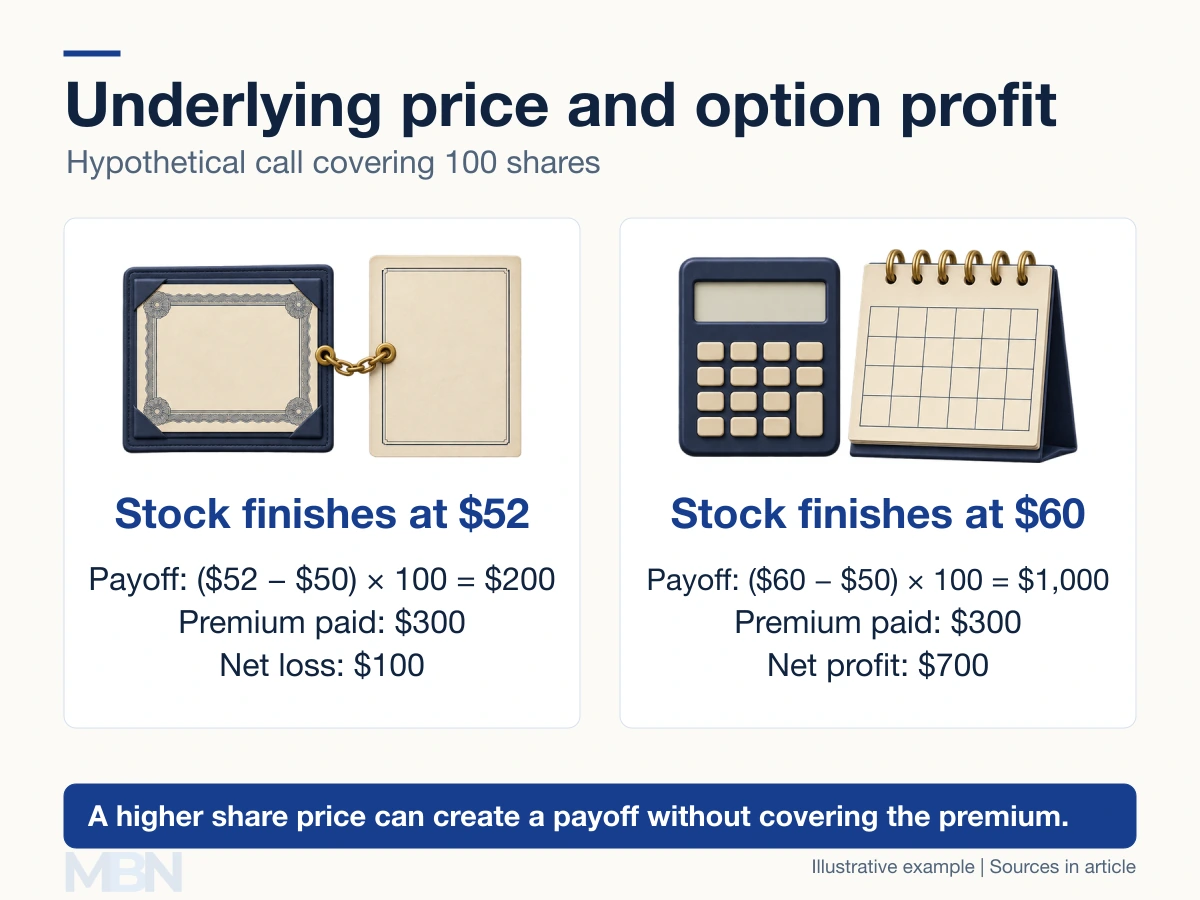
If the stock finishes at or below $50, this call expires without a payoff and its buyer loses the premium. A correct prediction that the share price will rise is therefore insufficient by itself to ensure an option profit.
Why prices do not move one-for-one
The underlying price is only one influence on an option’s premium. The Options Industry Council’s pricing guide also identifies strike, time remaining, implied volatility, interest rates and dividends. Implied volatility reflects the price variability embedded in option prices.
A share price can rise while a call loses value if other influences, such as declining time value or implied volatility, outweigh that effect. Different derivatives and positions have different sensitivities to the same reference.
Does the underlying have to be delivered?
No. CME Group distinguishes physical delivery from cash settlement. A physically delivered contract can require transfer of the specified commodity or instrument. A cash-settled contract instead uses a reference settlement value to calculate payments.
Closing a futures position before its delivery obligations arise is also different from holding it through settlement. Buying or selling a derivative should not be described as automatically receiving its underlying.
Hedging and speculation
A hedge uses a derivative to offset a related exposure, but a mismatch in size, timing or reference can leave risk. A speculative position deliberately takes exposure to possible price changes.
The OIC’s risk explanation distinguishes a standalone buyer’s premium loss from potentially much larger written-option obligations. Buying any option does not automatically reduce an investor’s overall risk or create unlimited profit potential. Those outcomes depend on the whole position and contract.
Last checked and updated on November 5, 2026 by the MBN editorial team.