
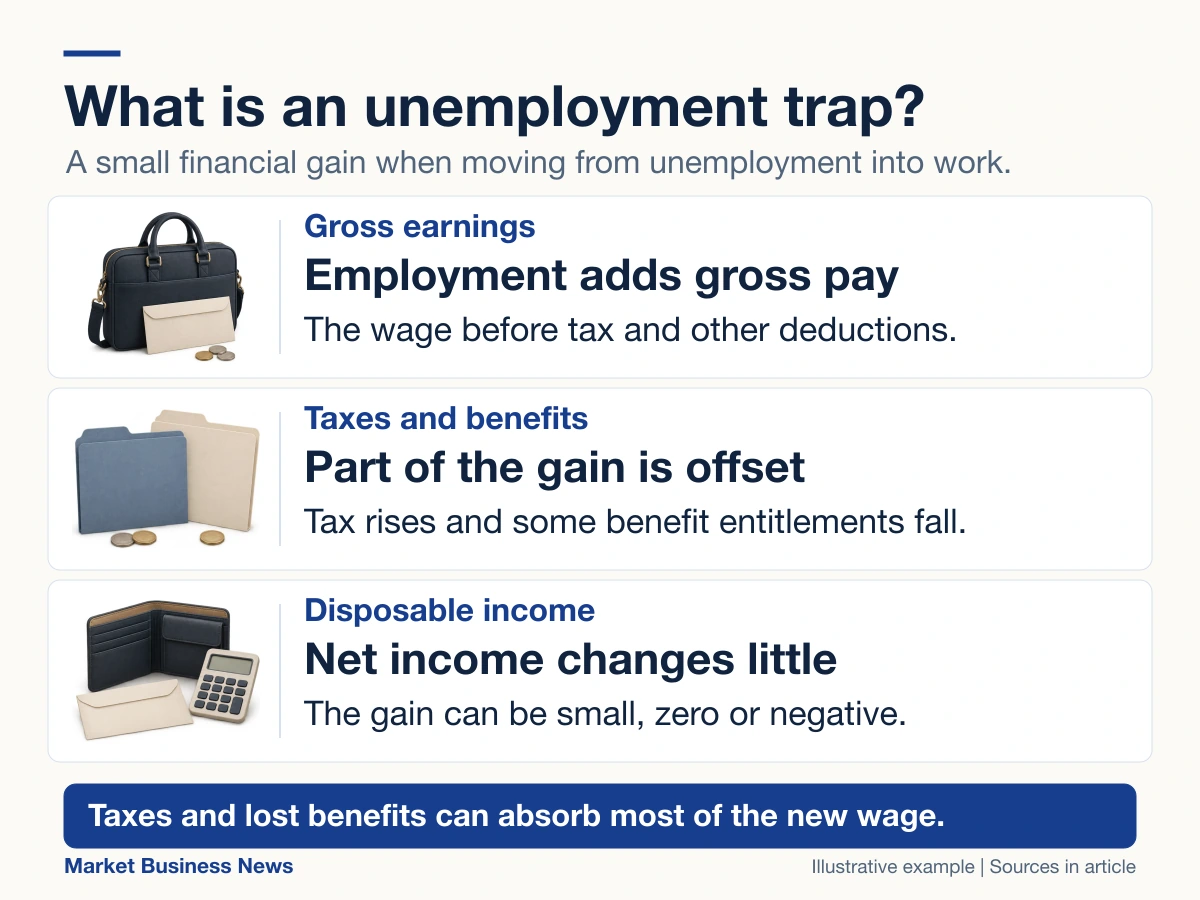
An unemployment trap occurs when taking a job produces little extra disposable income, or even a fall in income, because taxes rise and benefits are withdrawn. The gross wage can be much larger than the household’s financial gain from working.
Disposable income is what remains after direct taxes and contributions, including any benefits received. The term describes a financial incentive created by the interaction of earnings, taxes and benefits. It does not establish a person’s motivation or explain every reason someone is out of work.
How the unemployment-trap indicator works
The European Commission’s methodology defines the unemployment-trap indicator as the share of additional gross earnings offset by higher taxes, employee social contributions and lower benefits when an unemployment-benefit recipient enters work.
A high percentage means that a large share of the new wage is offset. It is not simply the income-tax rate. The loss of a benefit counts in the calculation even though it is not a tax payment.
The calculation depends on the household and the assumed job, including earnings, benefit entitlement and the rules in force. A published rate for a particular household type is not the rate faced by every unemployed person.
A hypothetical monthly income example
Suppose a person receives US$800 a month in unemployment benefits and pays no tax on that income. A job offers gross pay of US$1,000 a month. Under the invented rules for this example, the benefits end and tax plus employee contributions total US$100.
Disposable income becomes US$900: US$1,000 of pay minus US$100 of deductions. Compared with the previous US$800, the gain is US$100.
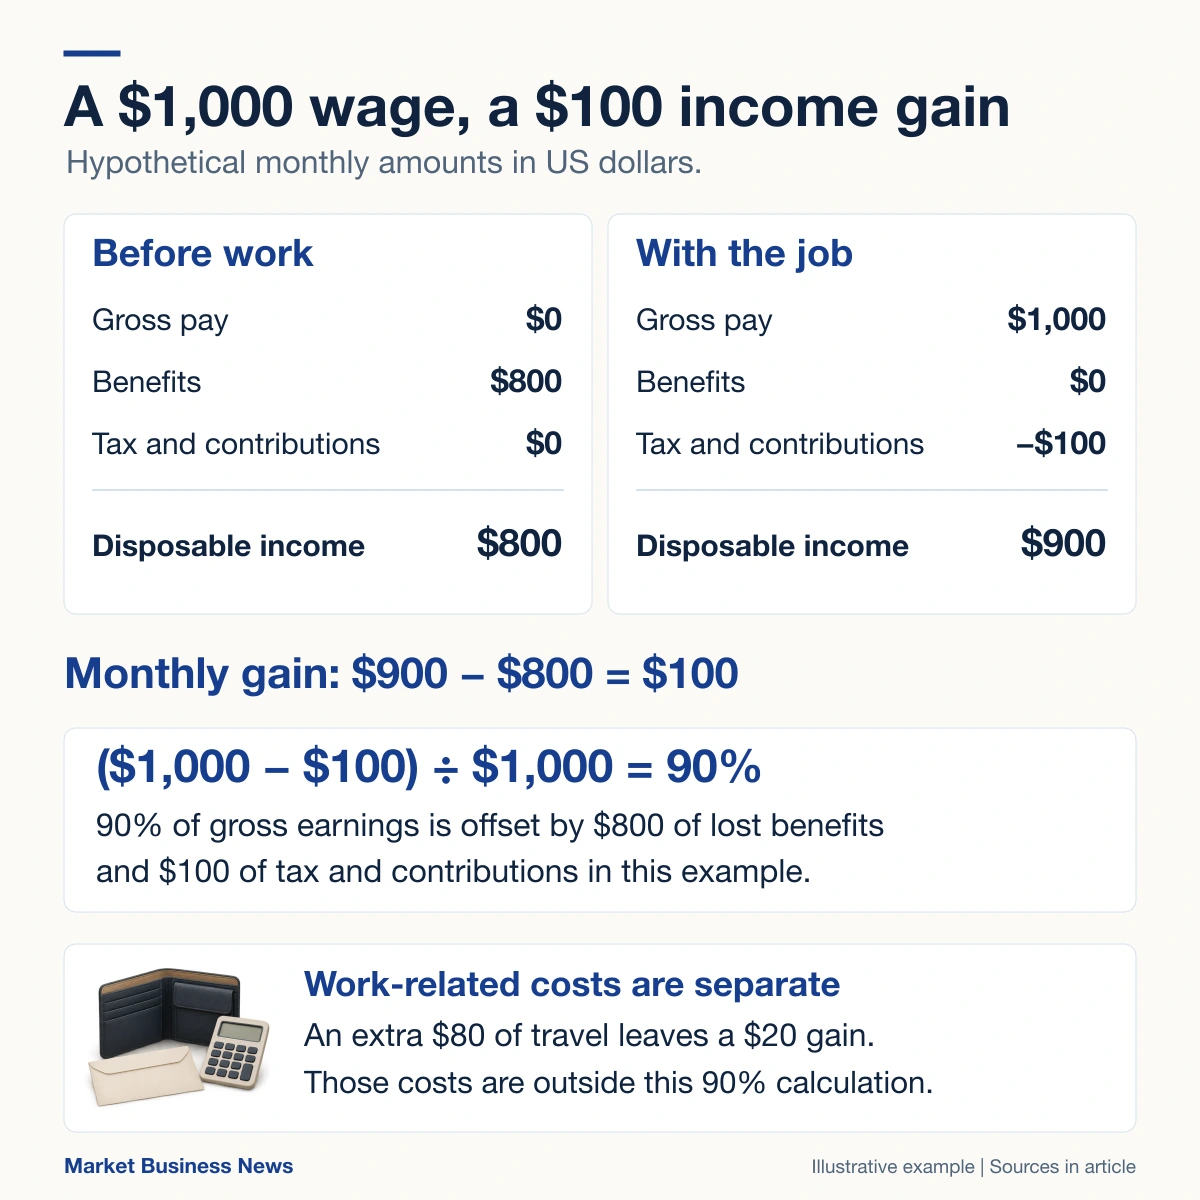
Of the US$1,000 in new gross earnings, US$900 is offset by lost benefits and deductions. The illustrative unemployment-trap rate is therefore 90%: (US$1,000 minus the US$100 income gain) divided by US$1,000. These are fictional amounts, not a calculation under US benefit rules.
Work-related costs affect the remaining gain
The example above excludes travel and childcare. If the job also requires US$80 of extra monthly travel spending, the amount left after that cost rises by only US$20.
Different indicators include different costs. The OECD’s measure for parents using childcare includes net childcare costs alongside taxes and lost benefits. Its assumptions therefore differ from a tax-and-benefit-only comparison.
A change in benefit withdrawal rules or in-work support changes the financial calculation. The availability of suitable jobs and childcare affects whether a household can take up work at all.
The indicator is separate from unemployment status
An income comparison cannot show whether someone is searching for work, available to start, facing a shortage of vacancies or dealing with another barrier to employment. Long-term unemployment describes how long someone has been unemployed, rather than the financial gain from entering work.
In US statistics, the Bureau of Labor Statistics uses employment, availability and job-search criteria, with specific rules for temporary layoffs. Receiving benefits is not itself the test for being counted as unemployed.
The Commission also identifies a related low-wage trap, where an employed person retains little of the extra earnings from additional hours. It concerns an increase in work by someone already employed, while the unemployment-trap indicator concerns the move into work.
Video explanation
The following video introduces the unemployment-trap concept.
Last checked and updated on November 2, 2026 by the MBN editorial team.