
A variable-rate mortgage is a home loan whose interest rate can change under its agreement. The change may affect the payment, the amount of principal repaid or both. The label does not tell you exactly how the rate will be set.
Tracker mortgages, standard variable rate mortgages and adjustable-rate mortgages have related features, but they are not identical products.
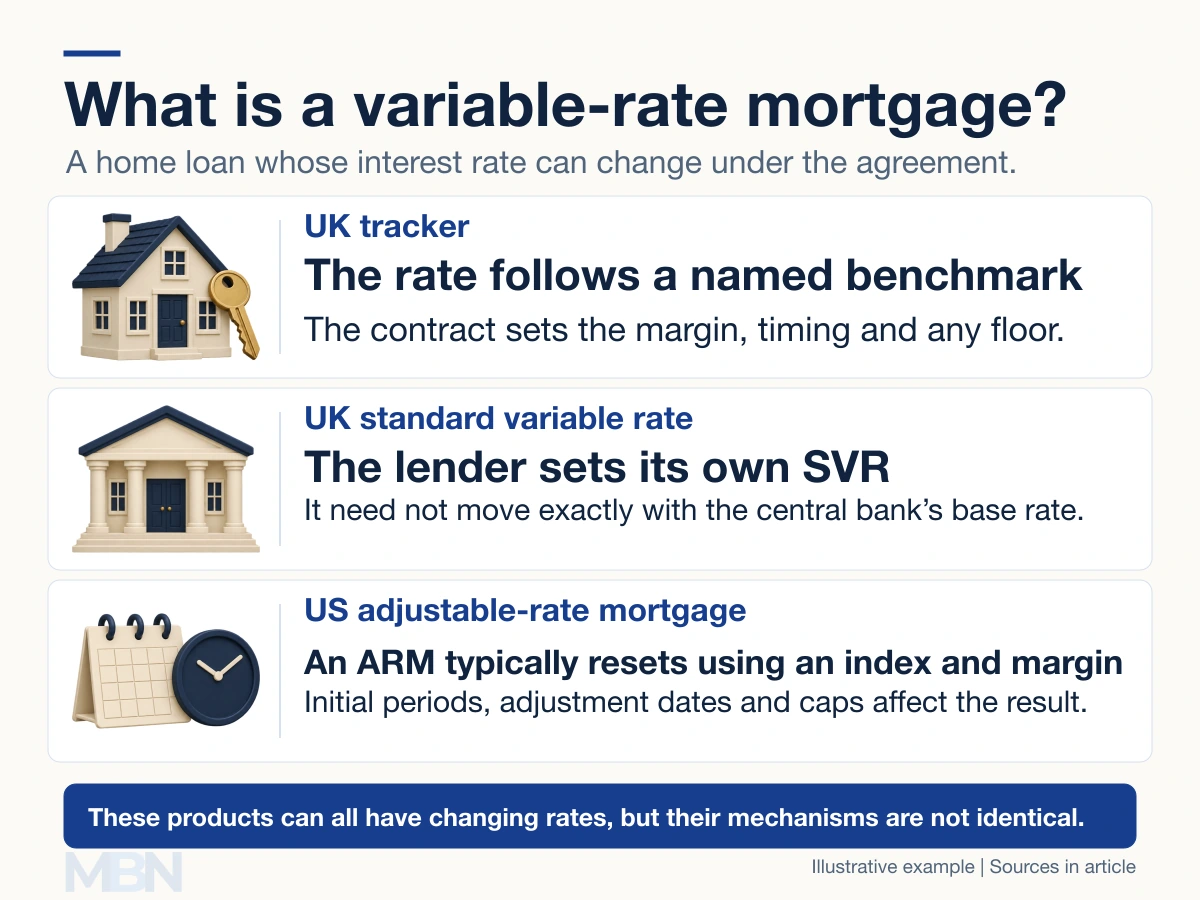
How do the different rate mechanisms work?
MoneyHelper distinguishes UK tracker mortgages from a lender’s standard variable rate, or SVR. A tracker follows a named benchmark according to its contract. An SVR is set by the lender and need not change by the same amount, or at the same time, as the central bank’s base rate.
The Consumer Financial Protection Bureau explains US adjustable-rate mortgages, or ARMs. Many have an initial fixed-rate period, followed by scheduled adjustments. A variable rate does not necessarily change every month.
What are the index, margin and caps?
The CFPB describes an ARM’s fully indexed rate as the index plus a margin. The index is a benchmark interest rate. The margin is the number of percentage points added under the agreement.
Adjustment caps limit specified rate changes, while lifetime caps limit increases over the loan’s life. Floors can limit decreases. These features mean that the formula alone may not be the actual rate applied at a reset.
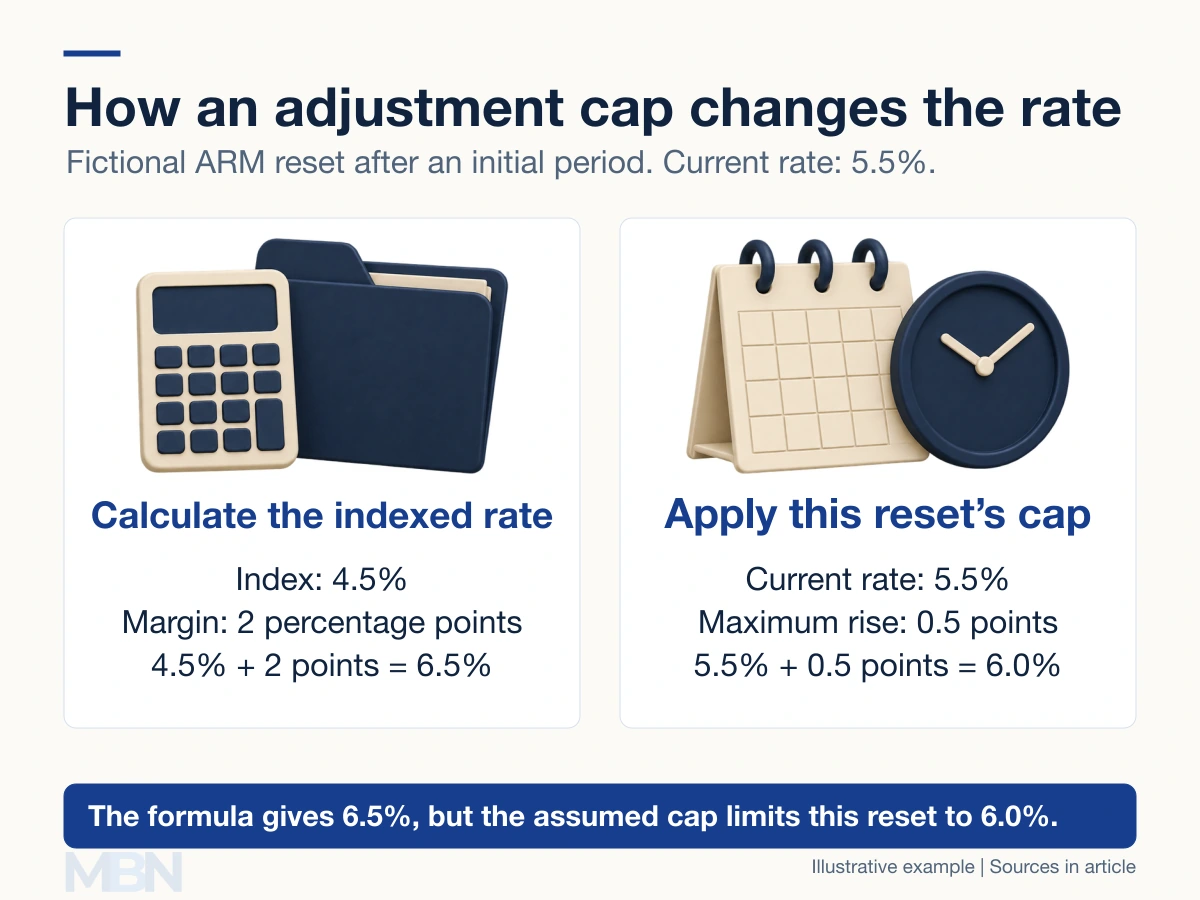
In the fictional example, a 4.5% index plus a two-percentage-point margin gives 6.5%. But the current rate is 5.5% and this reset allows an increase of only 0.5 percentage points. With no other binding conditions, the new rate is 6.0%.
The cap limits this adjustment; it does not promise that the rate can never rise again. A percentage-point change should also not be confused with a percentage change in the rate.
Must the monthly payment change when the rate changes?
Not always. The Financial Consumer Agency of Canada explains variable-rate mortgages with fixed payments. When the rate rises, more of a fixed payment goes to interest and less to principal.
At the trigger rate, the payment covers interest but no principal. If it becomes insufficient to cover interest and unpaid interest is added to the debt, the balance grows, known as negative amortization. Contractual responses can include higher payments or additional funds. Fixed payments do not make the interest rate fixed.
Is switching always free or available?
No. The CFPB explains that some mortgages have prepayment penalties. UK products can also have early-repayment conditions and arrangement costs. A new lender’s eligibility and affordability checks still apply.
A lower market rate does not guarantee refinancing, automatic savings or a particular new payment. The contract’s benchmark, margin, caps, remaining balance and term determine how the loan operates. Our fixed-rate mortgage explanation shows how a fixed interest rate differs from a fixed total monthly bill.
Last checked and updated on November 4, 2026 by the MBN editorial team.