
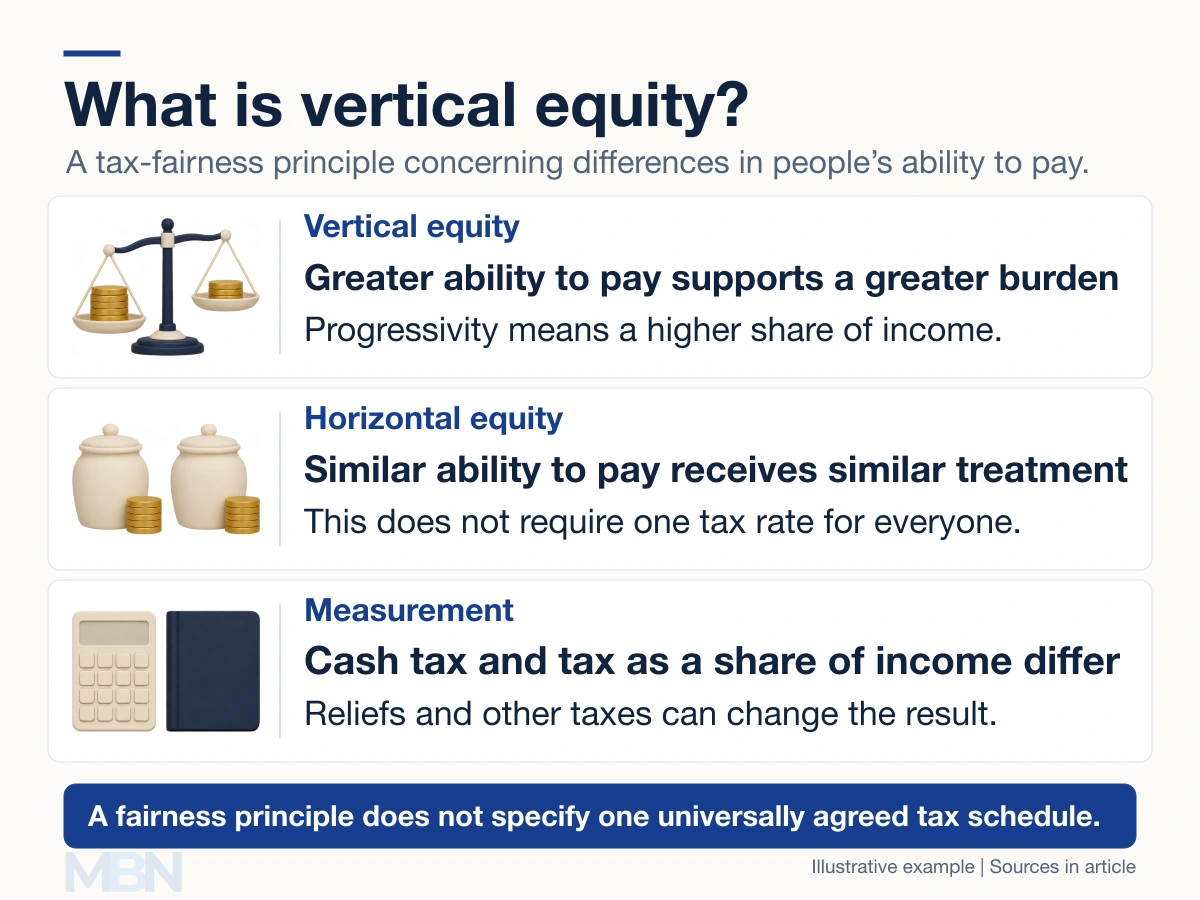
Vertical equity is the principle that people with greater ability to pay should bear a greater tax burden. It is commonly associated with progressive taxation, under which higher-income people pay a larger proportion of their income in tax.
It is a judgement about fairness, rather than a single formula. The US Government Accountability Office explains that vertical equity concerns differences in ability to pay. People can agree on that broad principle while disagreeing about appropriate rates, allowances or the treatment of wealth.
How is horizontal equity different?
Horizontal equity means treating people with similar ability to pay similarly. It is a companion principle, rather than the opposite of vertical equity. The Australian Parliamentary Budget Office distinguishes both principles and considers equity across the tax-and-transfer system.
For example, two people with similar relevant incomes and circumstances might be expected to face similar tax treatment. That does not mean every taxpayer, regardless of income, must face the same rate.
More tax in cash or a larger income share?
A proportional tax takes the same percentage of income from everyone. At an assumed 5% rate, a person earning $50,000 pays $2,500, while someone earning $100,000 pays $5,000. The second bill is larger, but the income share is unchanged.
A progressive tax takes a larger income share as income rises. A regressive tax takes a smaller share. These IRS teaching definitions distinguish the three patterns. Paying more cash alone does not establish progressivity.
A progressive tax example
Consider an invented annual schedule with 10% on the first $10,000, 20% on the next $10,000 and 30% on income above $20,000. A person earning $30,000 pays $1,000 + $2,000 + $3,000 = $6,000.
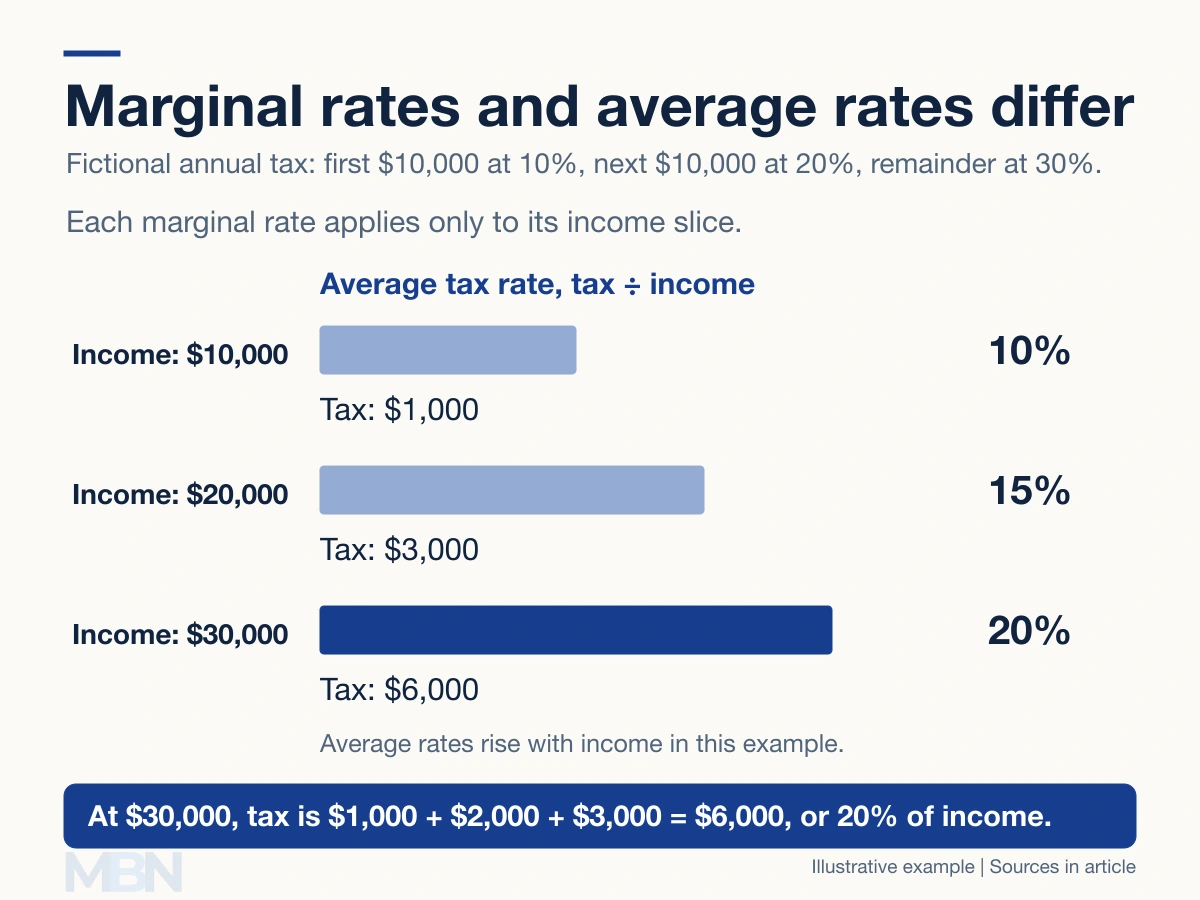
The marginal rate on the next dollar is 30%. The average rate is $6,000 ÷ $30,000 = 20%. Entering a higher band does not apply its rate to every earlier dollar.
How do real systems differ?
Allowances, credits, deductions, other taxes and benefits affect the overall result. A progressive statutory rate schedule does not by itself establish how progressive the whole system is.
For an actual example, HMRC publishes UK rates and allowances for 6 April 2026 to 5 April 2027. Scottish income-tax bands differ. The fictional dollar example above is separate from those rules.
A brief UK historical example
UK Parliament dates William Pitt’s introduction of income tax to 1799 and its reintroduction by Sir Robert Peel to 1842. Historical money also needs care: the Bank of England records 240 old pence to the pound, before decimalisation in 1971.
Neither history nor a calculation settles the fairness debate. Choosing how to measure ability to pay and balance different objectives remains a policy judgement.
Last checked and updated on November 3, 2026 by the MBN editorial team.