
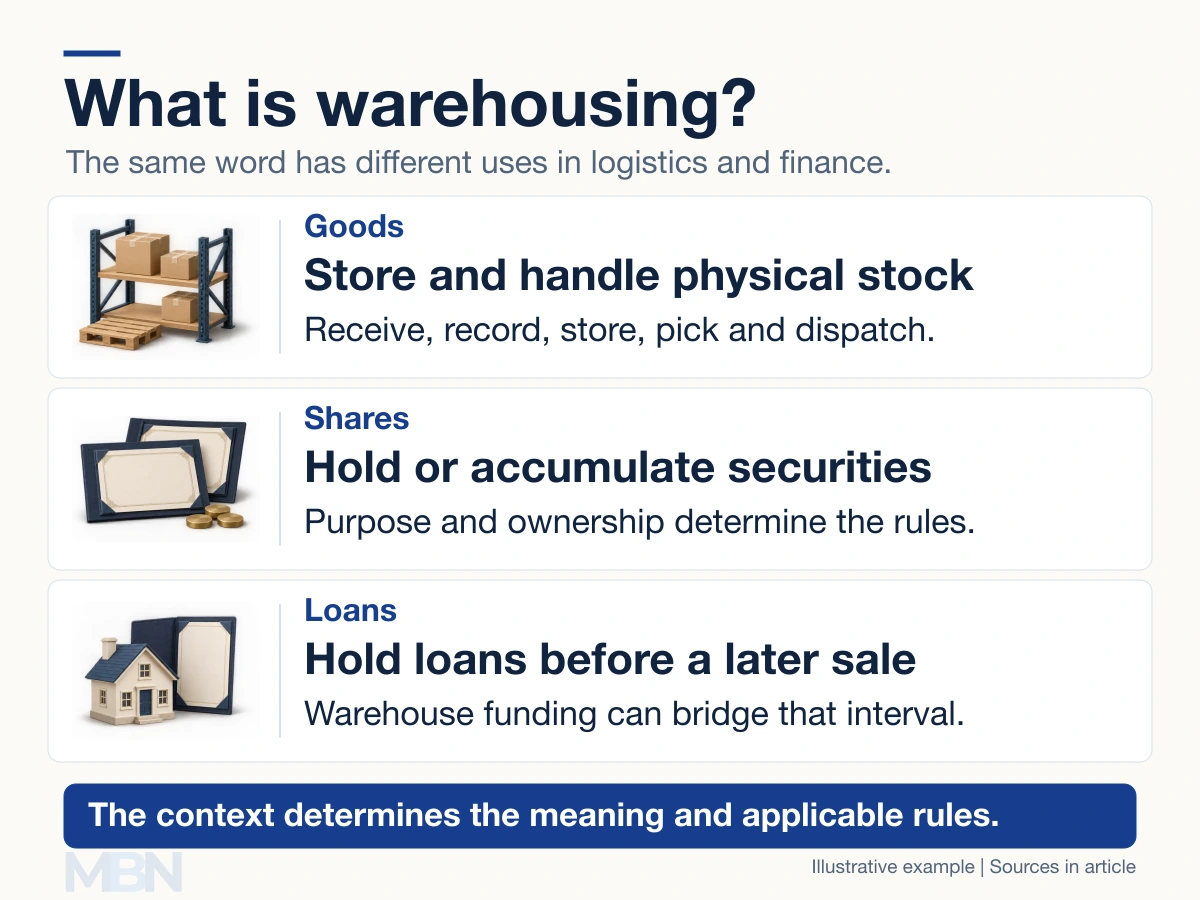
Warehousing usually means receiving, storing and handling goods before they are needed or sent elsewhere. In finance, the same word can describe temporarily holding loans or shares for a later transaction.
The activity and its purpose matter. Storage, mortgage funding and shareholding arrangements involve different assets and rules. Gradually buying shares is not automatically illegal, and a disclosure threshold is not a general ownership limit.
Warehousing goods
Goods warehousing includes receiving deliveries, checking quantities and condition, recording locations, storing stock, retrieving items for orders and preparing dispatch. Businesses may handle raw materials, components, spare parts or finished products.
A fictional furniture retailer might receive 100 boxed chairs, record their rack locations and later pick four for a customer order. Storage separates the arrival of stock from its eventual use or delivery.
Racking, handling equipment, inventory records, suitable storage conditions and trained staff support that work. The equipment depends on the products and operation; automation is not a defining requirement.
The Council of Supply Chain Management Professionals places warehousing within logistics management, alongside activities such as transport, materials handling and order fulfilment. A warehouse is the storage facility; warehousing is the activity.
Warehousing shares
In securities markets, warehousing can describe shares being accumulated or held for another party, sometimes ahead of a proposed takeover. Buying an initial stake ahead of a possible bid is also called stakebuilding.
These arrangements can raise disclosure, takeover and market-abuse issues. Their legality depends on the facts and applicable law, rather than the label alone.
Hong Kong’s Securities and Futures Commission distinguishes legitimate nominee arrangements from schemes used to conceal holdings, manipulate prices or evade regulatory requirements. A nominee holds securities in its name for someone else.
US beneficial ownership reporting
The US Securities and Exchange Commission (SEC) requires reporting for certain equity securities, generally classes registered under Section 12 of the Securities Exchange Act. These are called covered classes here.
For US reporting under Rules 13d-1 and 13d-3, beneficial ownership can include direct or indirect power to vote shares or direct their disposal. Using different account names does not necessarily create separate beneficial owners.
Suppose one fictional investor controls voting and disposal of 30,000 shares in each of two accounts. With 1,000,000 shares outstanding in the same covered class, that investor beneficially owns 60,000 shares, or 6%.
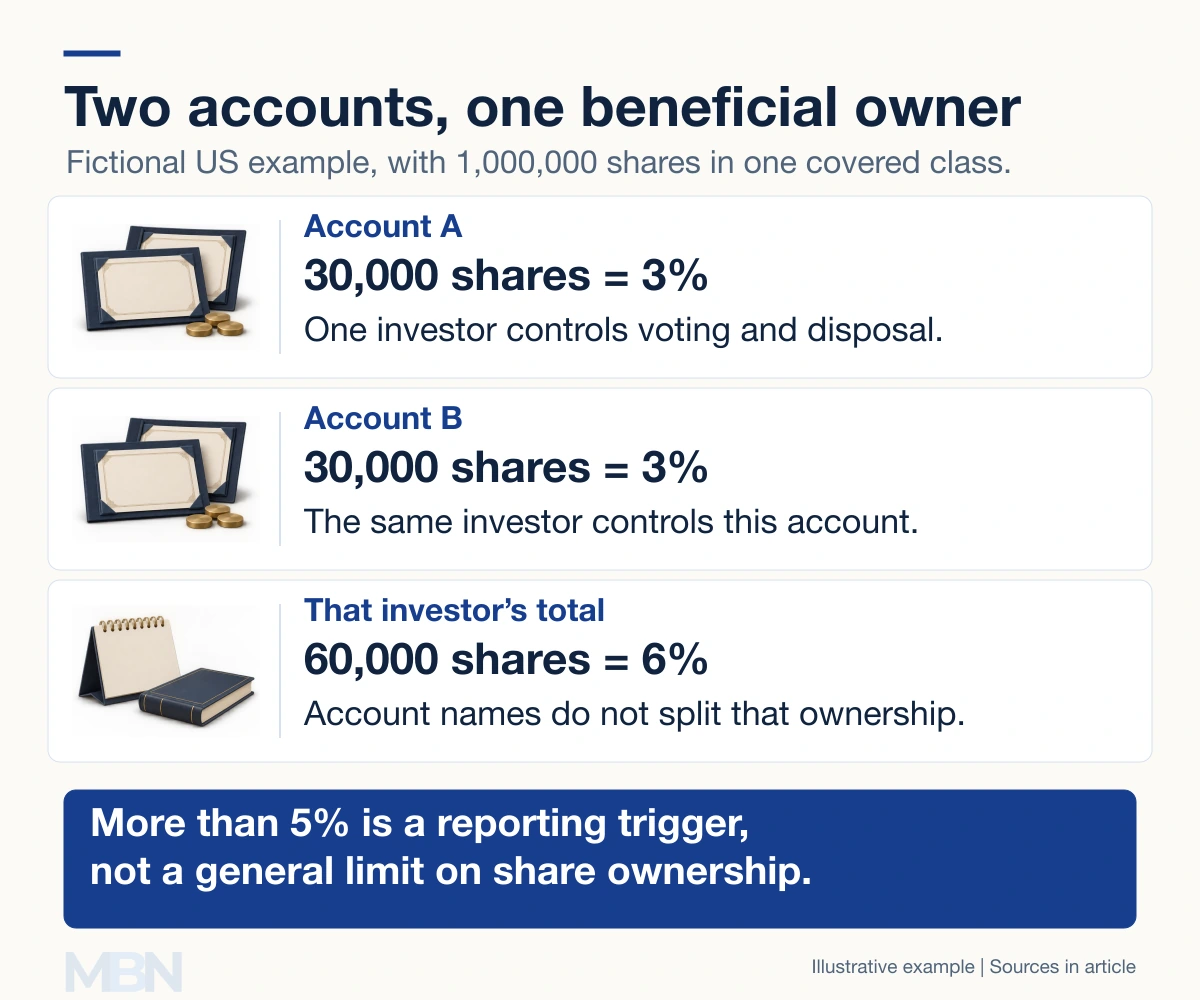
Under the SEC’s reporting rules, acquiring beneficial ownership of more than 5% of a covered class generally triggers Schedule 13D, unless an exemption or eligibility to use Schedule 13G applies. The initial Schedule 13D is generally due within five business days after the triggering acquisition. A material change generally requires an amendment within two business days.
Schedule 13G has separate eligibility conditions and deadlines. Neither filing is a universal rule for every company or security. These reporting requirements do not themselves prohibit owning more than 5%.
Rule 13d-3 also addresses arrangements designed to evade reporting. The SEC’s current interpretations explain specific reporting situations. Rules in other jurisdictions differ.
Warehousing loans
A mortgage lender may temporarily hold completed loans before selling them or arranging securitisation, the creation of securities backed by a pool of assets.
A warehouse credit line can finance that interval, with the mortgages pledged as collateral. The Richmond Fed describes this funding model for nonbank mortgage companies. Here, the assets being warehoused are loans, rather than physical goods or a concealed shareholding.
Last checked and updated on November 2, 2026 by the MBN editorial team.