
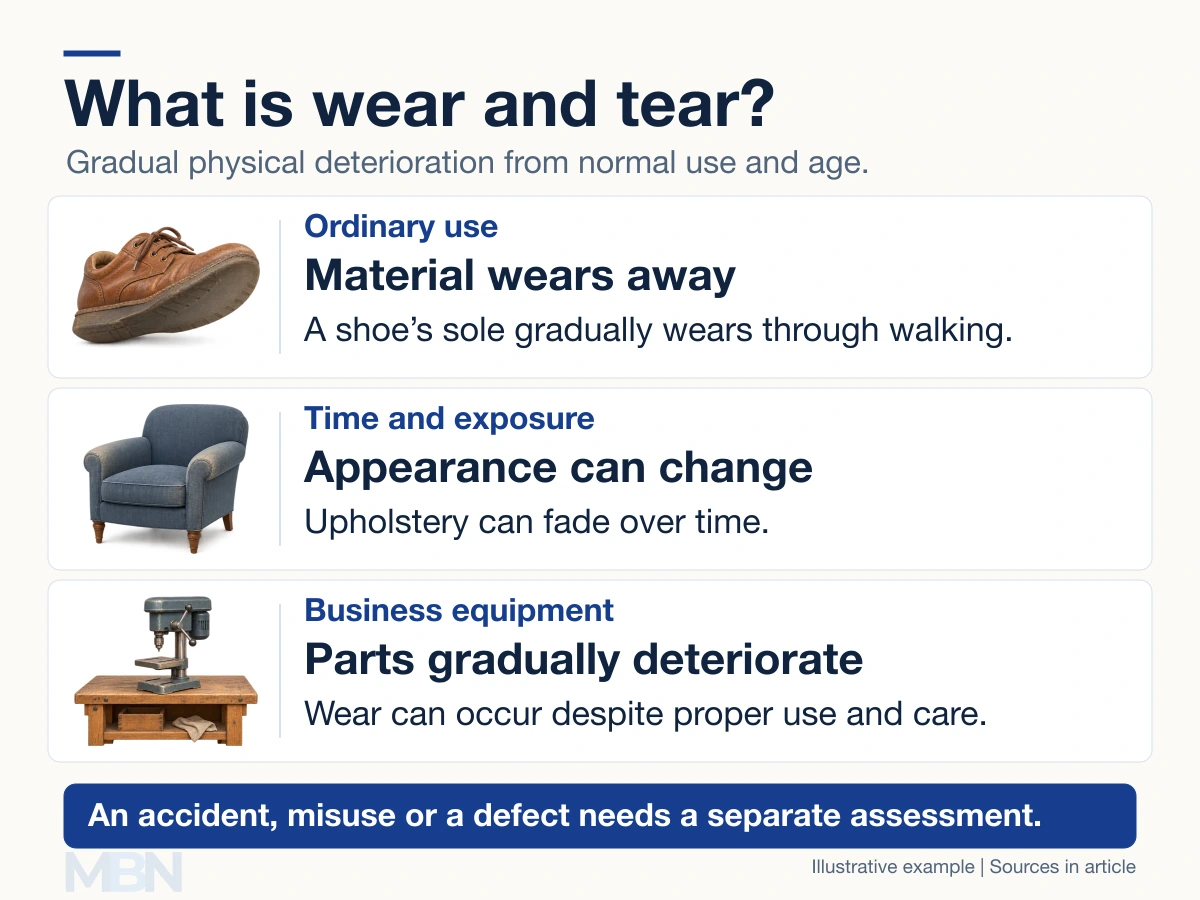
Wear and tear is the gradual physical deterioration that occurs through ordinary use, age and exposure. A shoe’s sole wearing down through walking, or upholstery becoming faded and rubbed, are common examples.
The term appears in discussions of equipment, rented property and warranties. It describes an item’s condition. Accounting depreciation deals with how an asset’s depreciable cost is allocated over its useful life.
Ordinary use and separate damage
Normal use can gradually change an object even when it is handled carefully. Repeated contact can rub away a surface, moving parts can wear, and exposure can fade some materials.
A chair with lightly rubbed upholstery after years of sitting illustrates gradual wear. A chair leg snapped in an accident illustrates a separate cause of damage. A manufacturing defect is another issue: deterioration alone does not establish what caused it.
The item’s age, original quality, starting condition and length of use help put the change in context. A worn surface on an old item and the same condition on a nearly new item may call for different explanations.
Wear and tear in rented property
In rental discussions, fair wear and tear generally refers to deterioration reasonably expected from normal occupation over time. It is different from treating every change since move-in as tenant-caused damage.
The UK’s Insolvency Service guidance separates normal wear from other damage when discussing tenancy deposits. The Tenancy Deposit Scheme also assesses the evidence of an item’s condition and the circumstances of each dispute.
The term does not set a universal number of years that a carpet, chair or appliance must last. The facts, tenancy terms and applicable law determine how a particular case is treated.
Wear and tear in warranties
A warranty may cover defects while excluding ordinary deterioration. For example, Apple’s U.S. one-year limited warranty excludes defects caused by normal wear or normal product aging. Its terms separately address defects in materials or workmanship and recognize that other consumer rights may apply.
That is one manufacturer’s contract, rather than a rule for every product. Gradual wear, accidental damage and a defect can have different coverage consequences.
How depreciation differs
Under the accounting principles in IAS 16, depreciation systematically allocates an asset’s depreciable amount over its useful life. Physical wear can influence the expected useful life, alongside factors such as technical obsolescence.
Suppose a fictional machine costs $10,000, has an estimated residual value of $1,000 and will be used for five years. With straight-line depreciation and unchanged estimates, the full-year charge is ($10,000 − $1,000) ÷ 5, or $1,800.
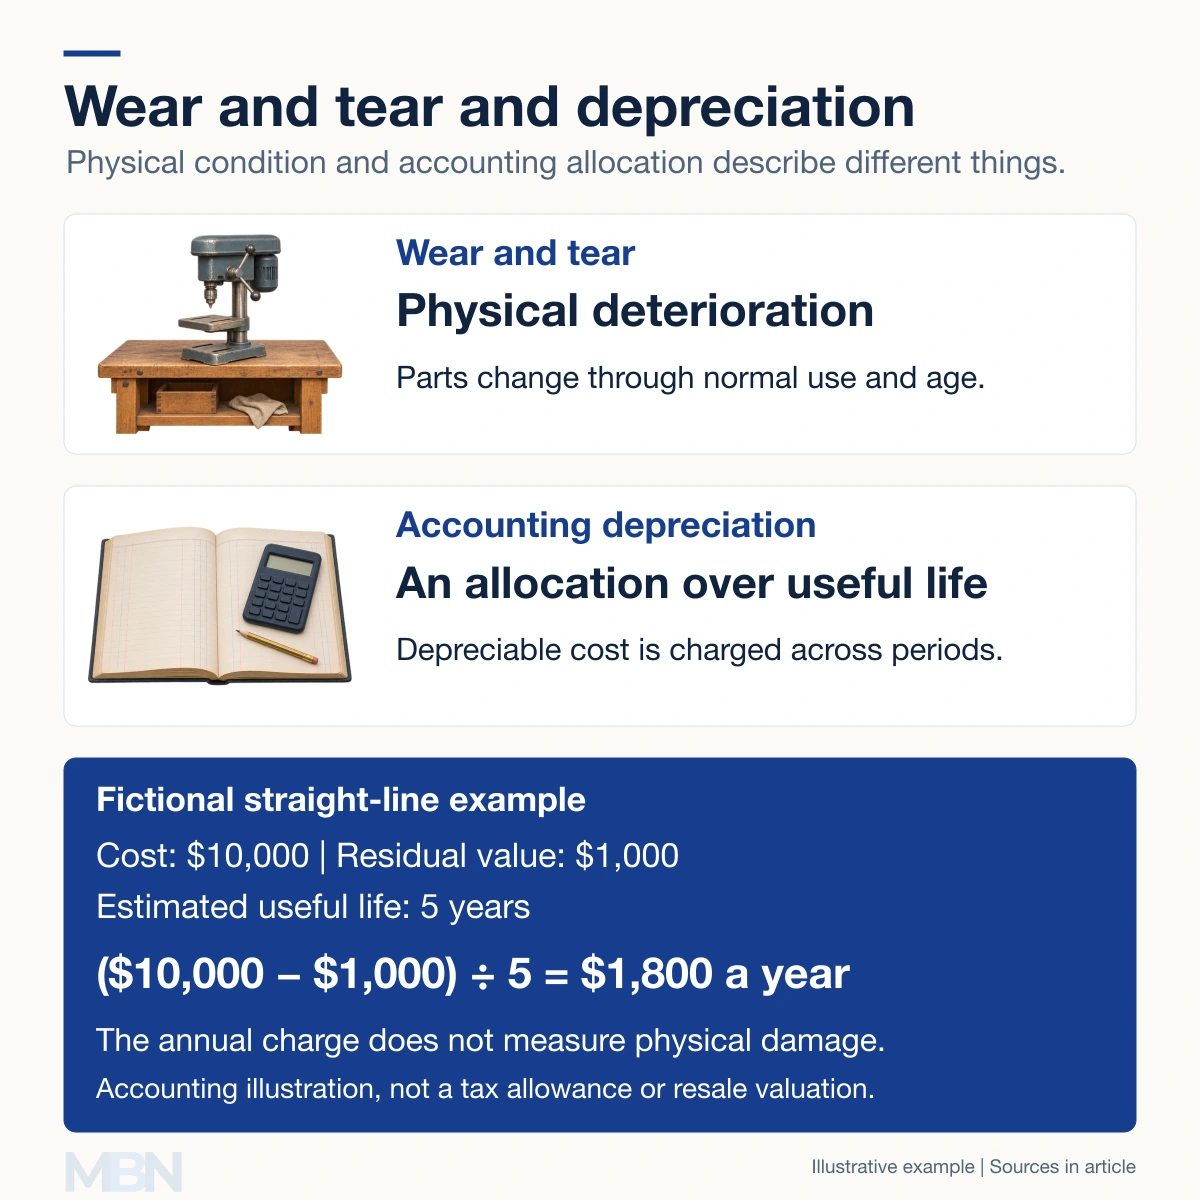
The charge does not mean that the machine has suffered exactly $1,800 of physical damage or lost that amount in resale value. Maintenance may slow deterioration while the accounting allocation continues.
Last checked and updated on November 2, 2026 by the MBN editorial team.