
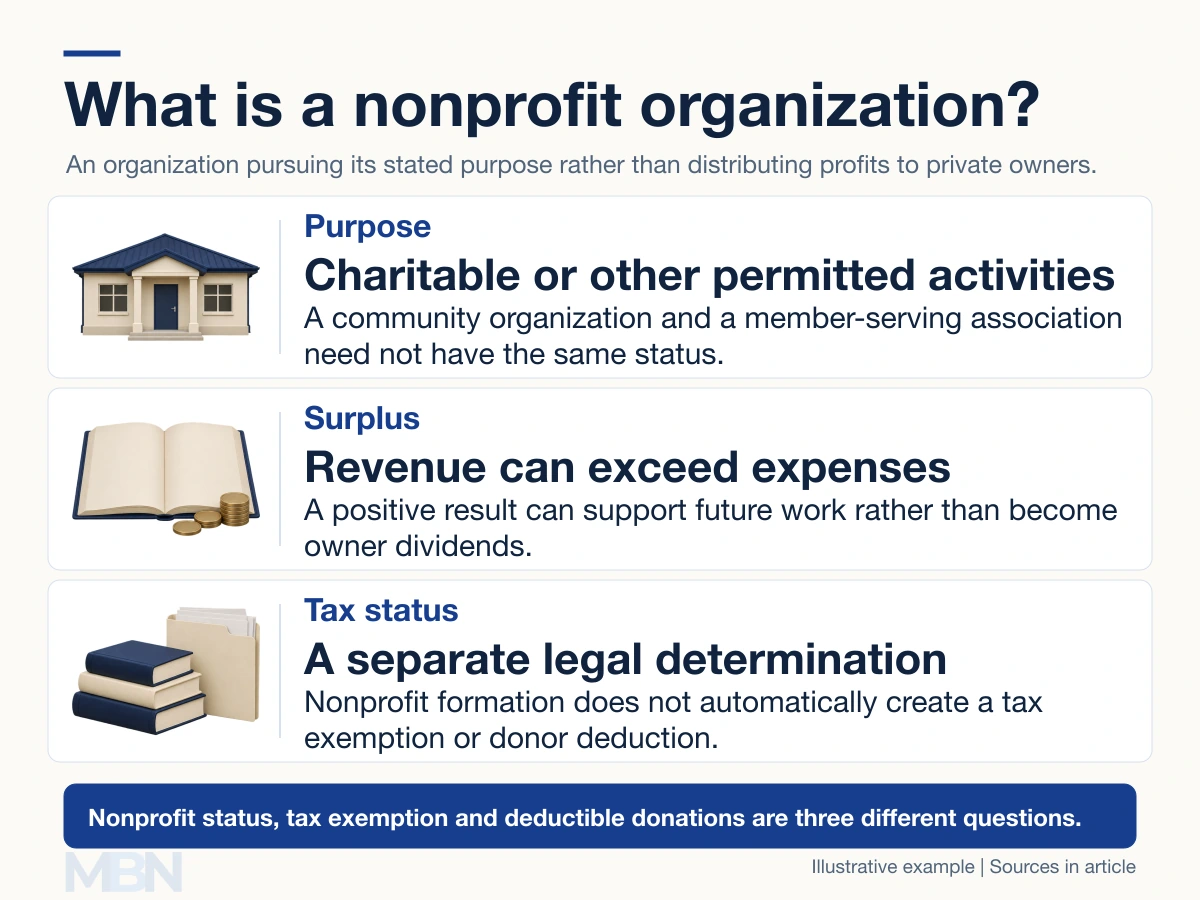
A nonprofit organization pursues a stated purpose rather than distributing profits to private owners. It can receive revenue, employ staff, charge for services and report a financial surplus. Nonprofit does not automatically mean charitable, tax-exempt or eligible to receive tax-deductible donations.
Examples include educational and community organizations, charities, professional associations and social clubs. Their legal forms, purposes and tax treatment can differ. A nonprofit can carry out business activities; calling it a “non-business entity” can obscure how it operates.
A surplus is not an owner dividend
Suppose a fictional nonprofit recognizes $120,000 in annual revenue and $100,000 in expenses. Its accounting surplus is $20,000. That positive result does not contradict nonprofit status.
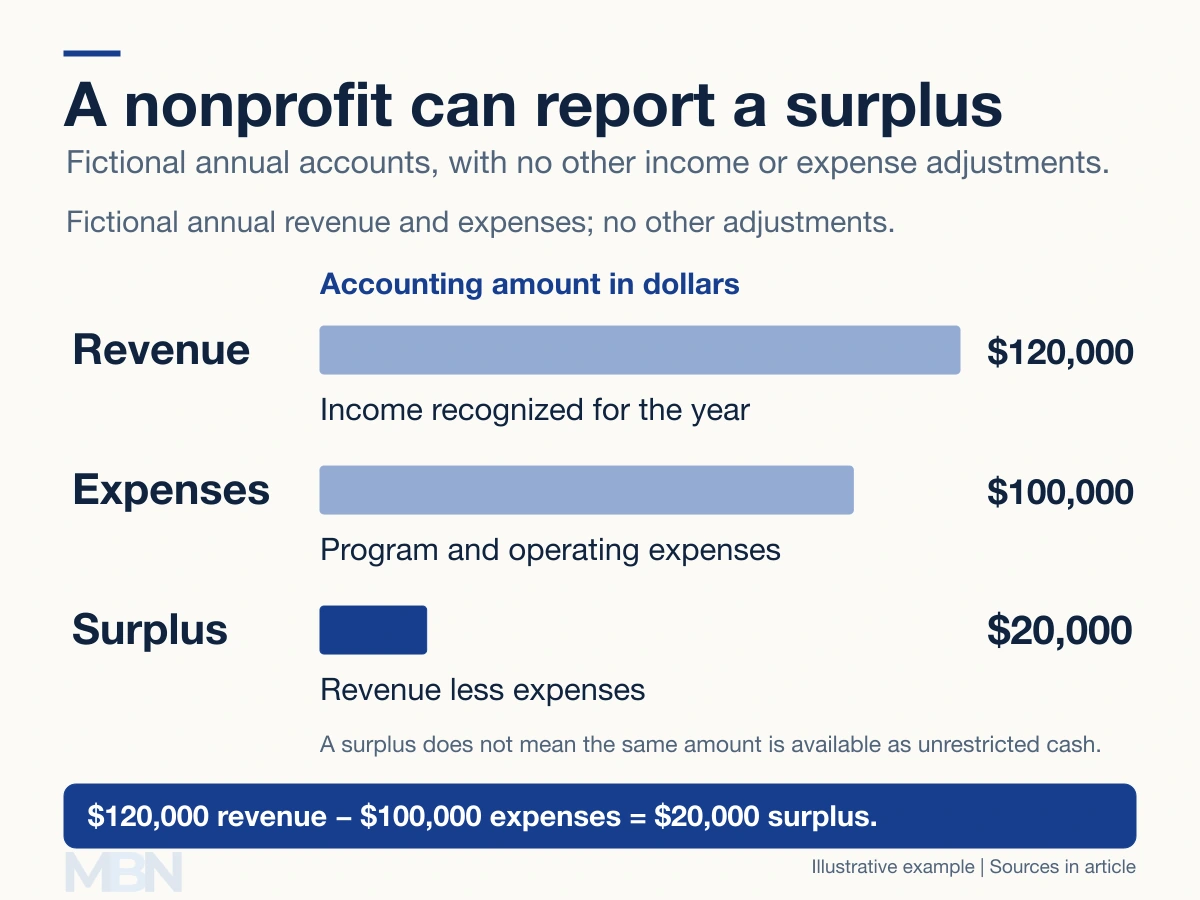
Funds can support current or future activities, subject to the organization’s purposes, law and any donor restrictions. A surplus is not necessarily the same amount as available cash. Nor must every dollar remaining at year-end automatically be spent immediately.
Paying staff is also different from distributing profits. The IRS distinguishes reasonable salaries from improper private benefit. For a US section 501(c)(3) organization, net earnings must not improperly benefit private shareholders or individuals. Excessive compensation or diversion of assets can jeopardize exemption.
Nonprofit status and tax exemption differ
In the US, nonprofit incorporation normally arises under state law. The IRS explains that this status does not automatically grant federal income-tax exemption. Most organizations seeking recognition must apply, although exceptions exist.
Section 501(c)(3) covers qualifying charitable, religious, educational and certain other purposes. Other provisions address different exempt organizations. A member-serving association is not necessarily a charity, and an exemption is not a blanket release from every tax.
An unincorporated association is not automatically disqualified. The IRS lists unincorporated associations and trusts among forms that may qualify under section 501(c)(3), alongside qualifying corporations and certain limited liability companies. The organizing documents and actual activities must meet the requirements.
Donations are not automatically deductible
An organization’s exemption and a donor’s deduction are separate questions. Deductibility depends on the recipient, gift and donor meeting the applicable rules. A donation to every type of tax-exempt organization is not necessarily a deductible charitable contribution.
The IRS Tax Exempt Organization Search provides deductibility information, filings and status records. The IRS notes that some eligible recipients, including certain churches and group-exemption subordinates, may not be listed separately.
How a nonprofit earns revenue matters
Donations and grants are possible sources, but fees, membership dues and other revenue can also support operations. Nonprofits are not necessarily funded only by gifts or government grants.
Even a tax-exempt organization can owe unrelated business income tax. In general, this concerns a regularly conducted trade or business not substantially related to the exempt purpose, with exceptions and modifications. Using its proceeds for a good cause does not by itself make the underlying business related.
Nonprofit and not-for-profit
The terms often overlap. The IRS itself uses nonprofit, not-for-profit and nonstock when explaining state-law organizational forms. They should not be separated by a universal rule that one means an organization while the other means only a hobby.
The important distinction is the organization’s actual legal structure, permitted purposes, restrictions on private distributions and particular tax status.
Last checked and updated on November 4, 2026 by the MBN editorial team.