
Window dressing in finance means arranging transactions, holdings or presentation to make a reported position appear more favourable. It often concerns a snapshot taken at a reporting date, such as a quarter-end balance sheet or a fund’s portfolio holdings.
The term does not establish whether conduct is legal. A properly disclosed transaction can be legitimate. False figures, omitted material information or misleading presentation can breach reporting requirements. Claims that window dressing is generally lawful need more qualification.
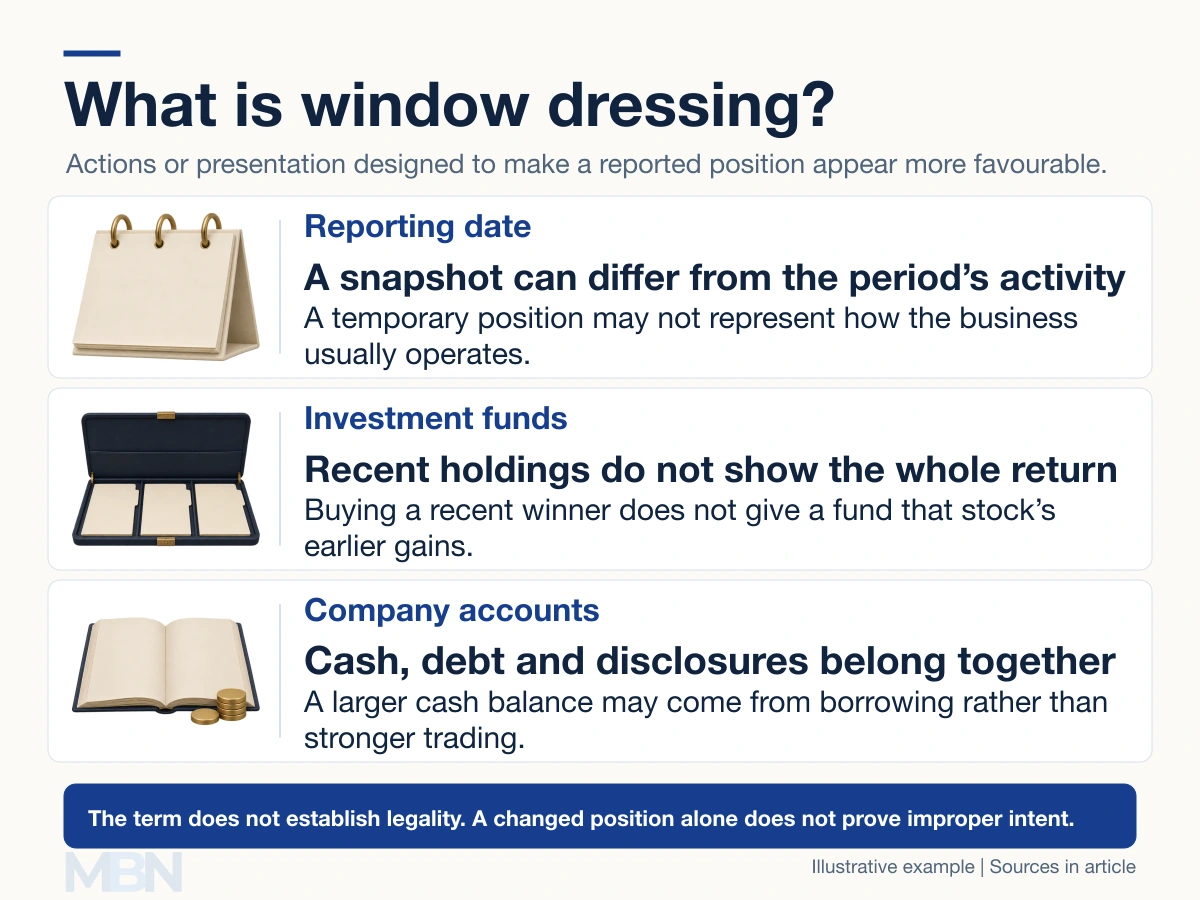
How fund holdings can create an impression
A fund might sell poor-performing investments and buy recent winners shortly before reporting its holdings. The resulting list can suggest that the manager selected successful investments earlier than it actually did.
Buying a stock after its price has risen does not give the fund the earlier gain. Selling a losing investment also does not erase the loss already incurred. Portfolio holdings at one date and investment performance over a period answer different questions.
In their research on mutual-fund window dressing, Vikas Agarwal, Gerald Gay and Leng Ling examined this pattern. Their work concerns incentives, disclosed holdings and fund performance. It does not justify assuming that every end-of-quarter trade is deceptive.
A higher cash balance can come from borrowing
Imagine a fictional company with £100 cash and £200 interest-bearing debt. It borrows another £500 just before its reporting date, with no fees, interest accrual or other transactions.
Cash becomes £600 and debt becomes £700. Using a simplified definition of net debt as debt minus unrestricted cash, net debt remains £100. The borrowing itself creates no profit.
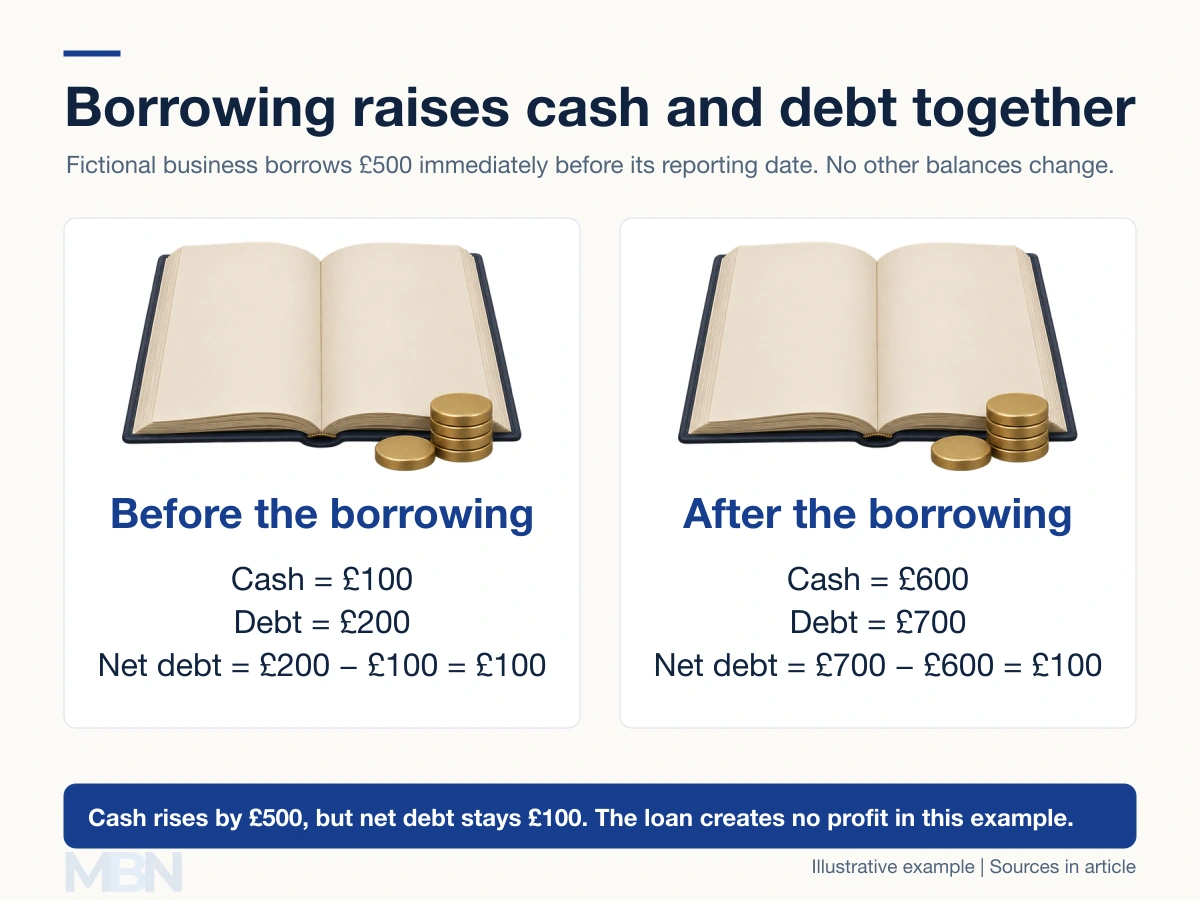
Reporting the higher cash balance accurately is not, by itself, misconduct. Presenting it as evidence of stronger trading while obscuring the new debt can give a different, potentially misleading impression.
Reporting dates and normal activity can diverge
The European Central Bank has discussed banks reducing certain balance-sheet positions around reporting dates and expanding them afterwards. Its analysis concerns particular banking incentives and reporting measures, rather than every company’s accounting.
Seasonal customer demand, repayments, genuine asset sales and routine portfolio changes can also alter a reporting-date position. A single snapshot does not establish the motive for a transaction or prove window dressing.
Disclosure and substance matter
In UK reporting, the Financial Reporting Council explains that omitting, misstating or obscuring material information can affect users’ decisions. The overall presentation matters as well as individual numbers.
Companies Act 2006 section 393 requires directors to be satisfied that accounts give a true and fair view before approval. Calling a practice window dressing does not override that requirement.
Window dressing overlaps with creative accounting, but the emphasis is often on the apparent position at a particular date. In ordinary retail language, window dressing also means arranging a shop-window display, a separate use of the phrase.
Last checked and updated on November 4, 2026 by the MBN editorial team.