
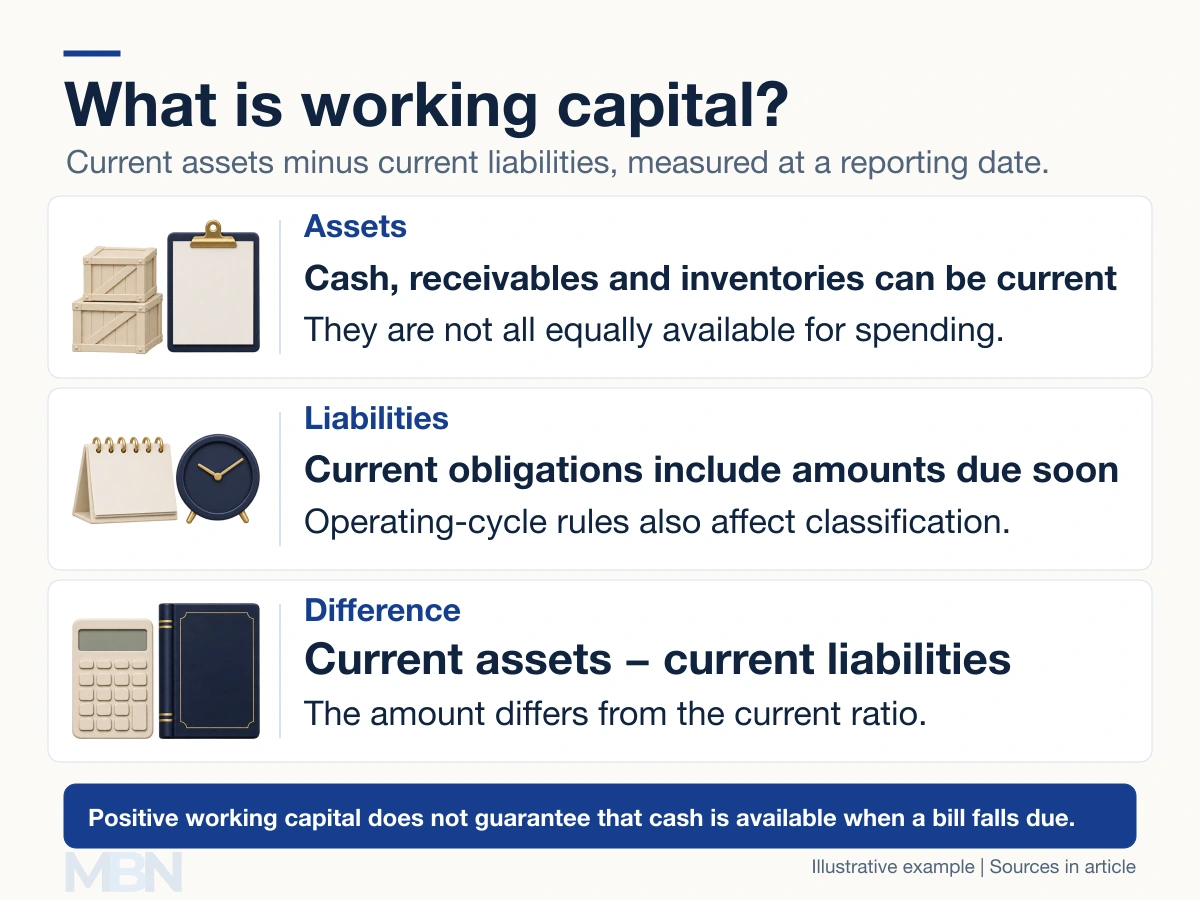
Working capital is current assets minus current liabilities. Usually called net working capital, it is a balance-sheet measure of the resources remaining after current obligations are deducted, rather than the amount of cash available to spend immediately.
The SEC’s financial-statement guide gives the formula: working capital = current assets − current liabilities. It is measured at a particular reporting date.
What counts as current?
Current assets commonly include cash, customer receivables and inventories. Current liabilities include supplier payables and obligations due in the near term. The precise classification follows the accounting rules.
IAS 1 includes both twelve-month and normal-operating-cycle criteria. Inventory can be current even where the production cycle lasts more than a year. Being classified as current does not mean an asset can instantly be converted into its recorded value in cash.
How does it differ from the current ratio?
Working capital is an amount. The current ratio, sometimes called the working capital ratio, divides current assets by current liabilities. Business Queensland explains that ratio and its formula.
If a fictional business has $100,000 of current assets and $70,000 of current liabilities, working capital is $30,000. Its current ratio is $100,000 ÷ $70,000, or about 1.43.
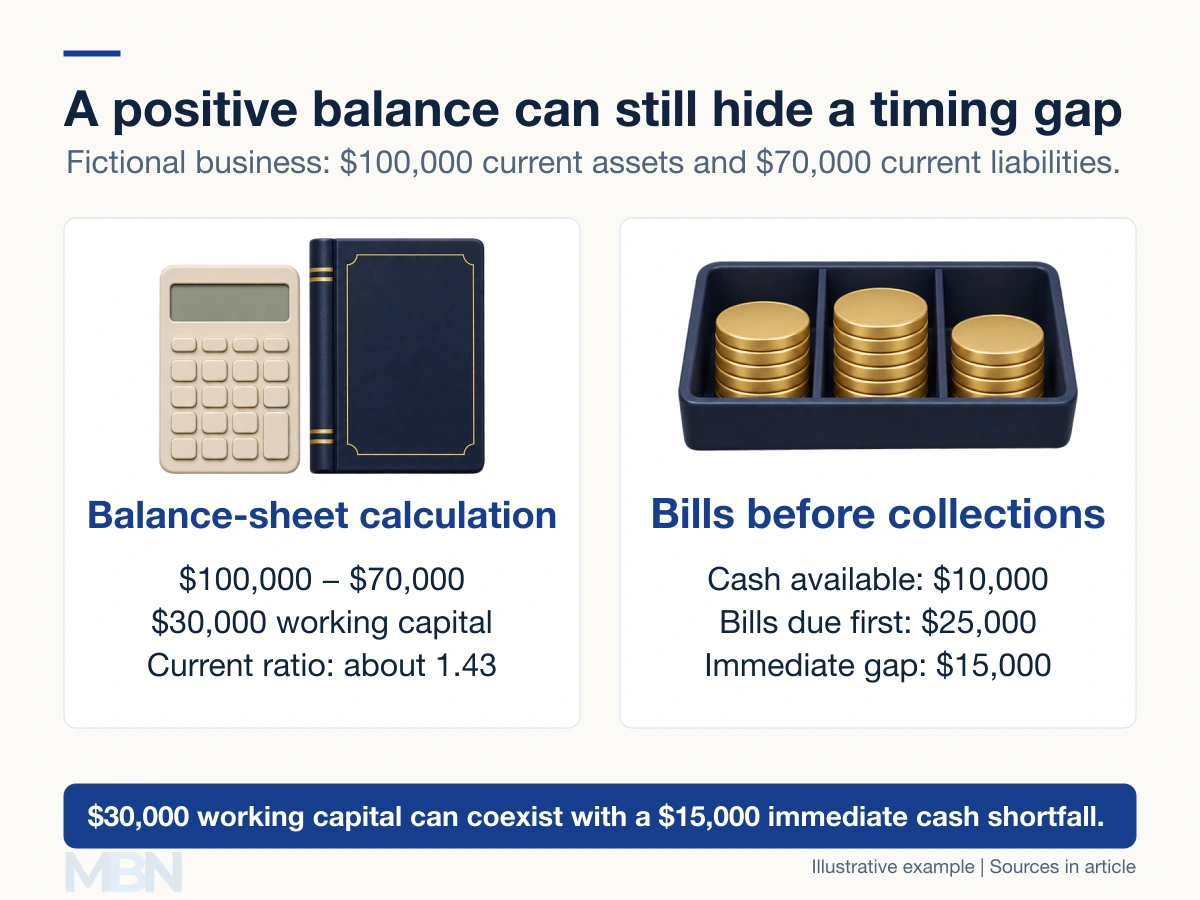
Suppose the assets comprise $10,000 cash, $40,000 receivables and $50,000 inventory. If $25,000 must be paid before further customer collections, the business has an immediate $15,000 cash gap despite positive working capital.
Is negative working capital always a crisis?
Negative working capital means current liabilities exceed current assets. It warrants attention, but the conclusion depends on payment timing, cash generation and access to finance. BDC discusses the composition and availability of working capital, including the lower liquidity of inventory.
A business that receives customer cash before paying suppliers may operate with relatively little working capital. Conversely, slow sales, overdue receivables or unavailable credit can make a positive balance less reassuring. No current-ratio range guarantees financial health for every business.
What is the working capital cycle?
The cash operating cycle measures the time between paying suppliers and receiving customer cash. A common calculation is inventory days + receivables days − payables days. ACCA explains why the cycle differs across business models.
For example, 40 inventory days + 30 receivables days − 50 payables days gives a 20-day funding interval. A negative cycle means customer cash arrives before suppliers are paid; it is a different measure from negative balance-sheet working capital.
How is cash flow different?
A cash-flow statement records cash movements over a completed period. A cash-flow forecast estimates future movements. Working capital is a snapshot. Comparing them helps explain why profit, cash and a working-capital balance do not move together.
Last checked and updated on November 3, 2026 by the MBN editorial team.