
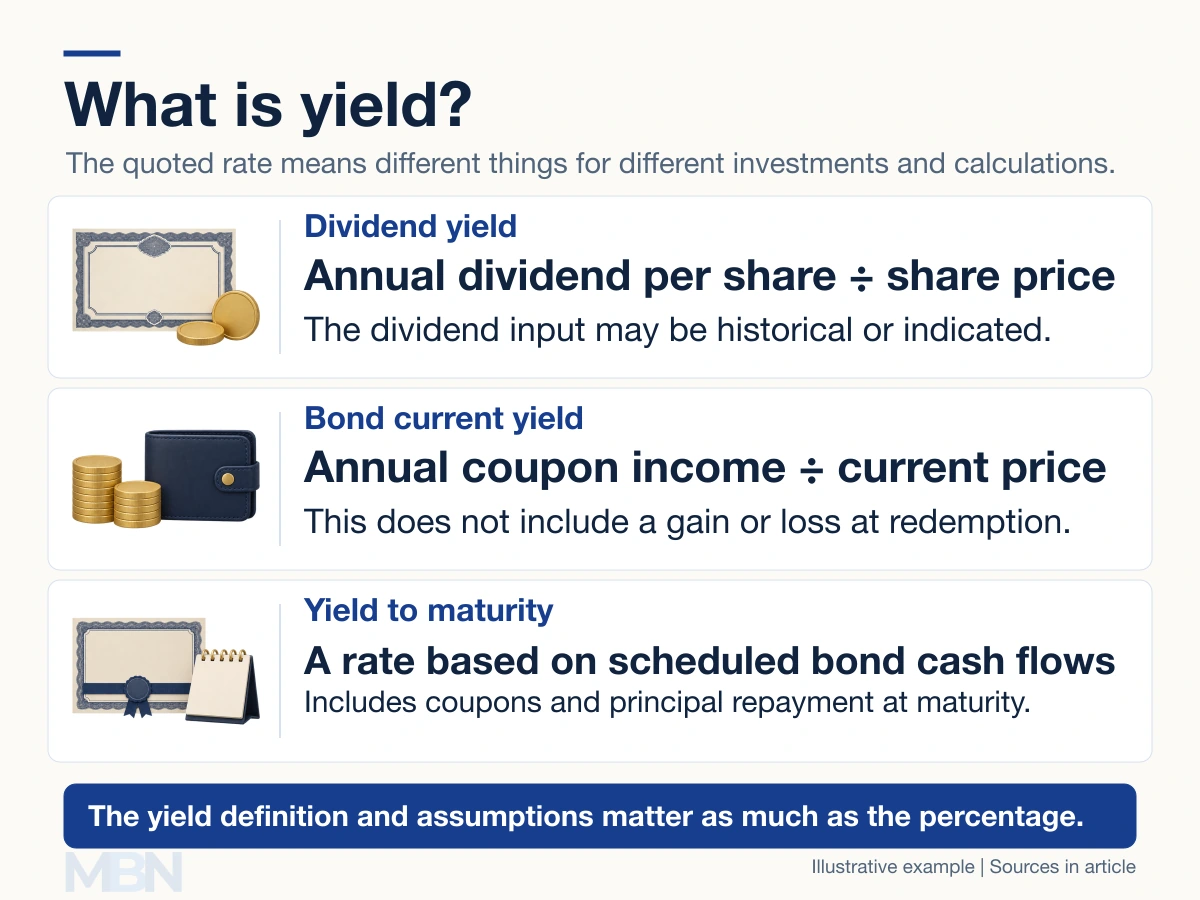
Yield is a quoted rate relating investment income or specified future cash flows to a price or value. Its meaning depends on the calculation: dividend yield, bond current yield and yield to maturity are different measures.
Most familiar yield quotations are annual rates. The percentage alone does not establish an investment’s total return, risk or future cash payments.
Dividend yield can use past or indicated payments
Fidelity explains both trailing and indicated dividend-yield calculations. A trailing measure uses dividends over the previous twelve months. An indicated measure annualizes a recent regular payment, assuming that payment continues.
Divide the chosen annual dividend per share by the relevant share price and multiply by 100. The dividend period, treatment of special payments and price date should be clear.
In our fictional example, a share bought for $15 now trades at $30 and has a $2 annual dividend. Yield on the original cost is $2 ÷ $15 = 13.33%. Current dividend yield is $2 ÷ $30 = 6.67%.
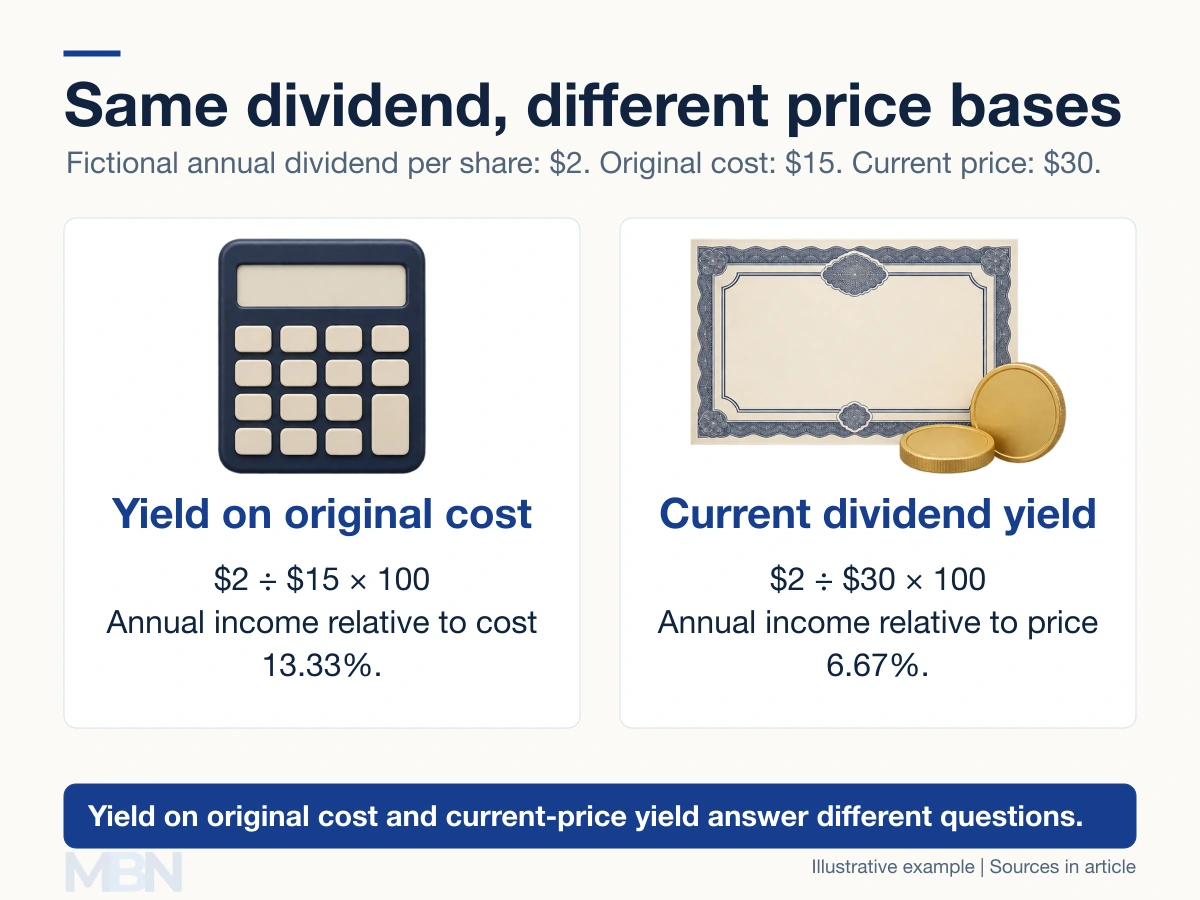
The original purchase cost does not change what a new buyer pays today. Neither calculation guarantees that the dividend will continue.
Bond current yield and yield to maturity
Investor.gov defines bond current yield using annual interest and the current market price. For a fictional bond paying $50 annually and trading at $1,000, current yield is 5%. It excludes the gain or loss between purchase price and redemption value.
The St. Louis Fed defines yield to maturity as the rate discounting scheduled coupons and principal to the bond’s price. It therefore includes the price-to-redemption relationship, rather than income alone.
FINRA explains that yield-to-maturity calculations assume timely payments and can differ from realized total return. Selling early, default, fees, taxes and the rates earned on reinvested coupons can change the outcome.
Why yield is not total return
Total return includes income and price changes over a specified holding period. It can be measured historically or estimated prospectively. Both yield and return quotations can use past data or forecasts, depending on the measure.
Suppose someone buys a different share for $30, receives $2 in cash dividends and ends the period with a $25 share value. The gain or loss is $25 + $2 − $30 = minus $3, giving a minus 10% total return before costs.
A positive income yield can therefore accompany an overall loss. Our total-return explainer also distinguishes cash dividends from reinvestment.
What can a high yield indicate?
A falling price can raise an income yield even without a larger payment. It may reflect increased risk or doubts about future payments. Dividends can be cut, and bond issuers can fail to pay. A higher quoted yield does not automatically make an investment safer.
Last checked and updated on November 3, 2026 by the MBN editorial team.