
Payday loan firms will have an 0.8% per day price cap imposed by the Financial Conduct Authority to help make sure they do not rip off borrowers. The new regulations come into force on January 2nd 2015.
The Financial Conduct Authority (FCA), Britain’s watchdog, said the new regulations will help reduce costs for the majority of borrowers.
The 0.8% per day ceiling applies to all high-cost short-term loans, and must also include the charges for fees.
There will be a price cap of £15 on all fixed default fees, the aim being to protect borrowers who are finding it difficult to pay back.
The total cost limit of 100% aims to shield borrowers from runaway debts. As from January 2nd, the amount paid in fees and interest should never be more than the original loan.
This means that for every £100 borrowed on a 30-day contract, on-time repayments should not exceed £24 in fees and charges.
The FCA had announced its proposals in July, then put it to consultation, and issued its decision on Tuesday.
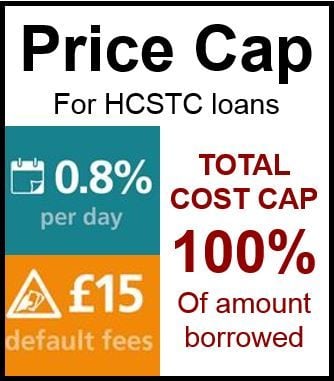
(Data source: Financial Conduct Authority infographic)
The rules are fair for all market players, the FCA believes, despite their being a 35% decline in payday loan volume during the first five months of its oversight. This was probably because lenders were being more careful.
After its new reforms come into effect, the FCA estimates that about 70,000 people, or 7% of all current borrowers, may not have access to payday loans. “These are people who are likely to have been in a worse situation if they had been granted a loan. So the price cap protects them,” the FCA said.
Payday loan lobbyists say the new regulations will probably drive loan candidates who are now turned down to loan sharks.
Martin Wheatley, FCA CEO, said:
“If the price cap was any lower, then we risk not having a viable market, any higher and there would not be adequate protection for borrowers. For people who struggle to repay, we believe the new rules will put an end to spiraling payday debts.”
“For most of the borrowers who do pay back their loans on time, the cap on fees and charges represents substantial protections.”
Payday loan firms have been described as ‘legal loan sharks’.
A payday loan is a small loan that the borrower requires until payday. The lender expects to be paid back when the borrower gets his or her salary.
