
Royal Bank of Canada ranks highest in overall customer satisfaction among the country’s Big 5 Banks, beating Toronto-Dominion Bank (TD), which had been the unrivaled league-table winner for a decade.
Royal Bank of Canada, known formally as RBC Royal Bank (RBC) achieved a customer-satisfaction score of 765, versus TD’s 761. RBC scored particularly well in product; the most important of the seven factors used in the rating system.
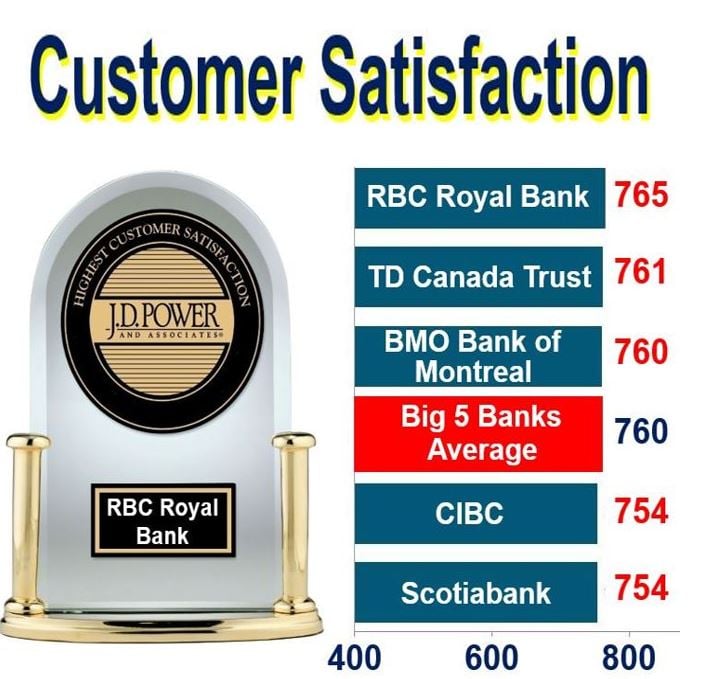 RBC Royal Bank beat TD Canada Trust in the J.D. Power 2016 Canadian Retail Banking Satisfaction Study. (Image: adapted from jdpower.com)
The study, carried out by J. D. Power, is now in its 11th year. It measures customer satisfaction with retail banks in two segments: The Big 5 and the Midsize Banks. In both segments customer satisfaction is measured in the following seven factors (listed in order of importance):
1. Product
2. Self-Service
3. Personal Service
4. Facilities
5. Communication
6. Financial Advisor
7. Problem Resolution
Each bank achieves up to 1,000 points – the higher the number the better customers rate them.
Tangerine, a direct bank and a subsidiary of Scotiabank, ranked highest in overall customer satisfaction among midsize banks – for the fifth year running. Tangerine, with a score of 840, performed particularly well in personal service, product, self-service and communication.
President’s Choice Financial – scoring 789 – came second among the medium size banks.
The 2016 Canadian Retail Banking Satisfaction study, is based on responses of over 13,000 customers who use a primary institution for their personal banking requirements. The survey includes the biggest financial institutions in the country, and was fielded during April and May this year.
Customers increasingly satisfied
Overall satisfaction with Canadian retail banks has improved considerably as customers become more willing to accept higher fees incurred during the past 24 months, says J. D. Power.
This year, overall customer satisfaction was twenty-three points higher than in 2015. The overall satisfaction average for the Big 5 Banks was 760, compared to 737 last year. Midsize banks also scored better – from 759 in 2015 to 783 this year.
The survey authors said it was encouraging to see satisfaction improve despite changes in fees. For example, one quarter of the Big 5 Banks’ customers this year say there has been a change in their fee structure, while 16% said new fees were introduced – both percentages were similar to last year.
Paul McAdam, J.D. Power’s senior director of banking services, said regarding customers’ attitudes to the new pricing structures:
“The improvements indicate that customers are becoming less sensitive to new pricing structures, which caused satisfaction to tumble in 2015.”
“The banks are doing a better job communicating with their customers, who now are seeing the value they are getting in return for higher fees.”
Satisfaction has improved across all seven factors, with product and self-service being the highest-weighted drivers of the overall retail banking improvement. They increased by six and five points respectively.
Satisfaction in chequing – a subfactor of product – increased significantly year-over-year, while satisfaction in mobile and ABM (automated banking machines) were the main drivers of improved satisfaction in the self-service factor.
Mobile changing the world of banking
Mobile banking refers to the use of smartphones and other cellular devices to perform online banking tasks while out and about and away from your home computer.
According to the study, thirty-four percent of bank customer now use mobile banking channels, compared to 27% last year and 20% two years ago. Overall retail banking satisfaction among customers who use mobile banking stood at 836 this year, compared to 760 points among people who do not perform banking tasks using mobile devices.
Of all the banking channels in 2014, mobile banking scored the lowest (770). This year, satisfaction with mobile banking stood at 804, i.e. an increase of 34 points over the past two years.
Mr. McAdam said:
“Mobile is changing customer interaction models and forcing banks to transform. Banking providers understand that customer expectations of interactivity with mobile devices are different than their expectations of other touch points.”
“The effect of mobile is evident across many aspects of the banking customer experience.”
Highly satisfying mobile banking also helps minimize the negative impact of a problem or complaint, helps maintain satisfaction with a smaller branch network, reduces price sensitivity, and improves perceptions of available products and services.
The survey authors said product satisfaction among customers who use and like mobile banking scored 795 points, versus just 710 among those who never use mobile.
Facility satisfaction among customers who have just two or fewer branch offices nearby averaged 788 points among mobile users, compared with 739 points among those who never use mobile.
Mr. McAdam said:
“Self-service makes banking more convenient for customers, with mobile technology being a key element of self-service.”
“Despite the growing number of digital channel interactions, there is more that banks can do to drive customers to self-service channels for routine transactions, which make it easier for the customer and more cost-effective for the bank.”
