
Financial assets include cash, ownership interests in another entity and contractual rights to receive cash or another financial asset. Bank deposits, loans receivable, bonds and shares are common examples.
The asset is the money, claim or ownership interest. A paper certificate may document that right, but the paper is not the source of its financial value. Cash itself is included, so financial assets cannot all be defined as things with no physical form.
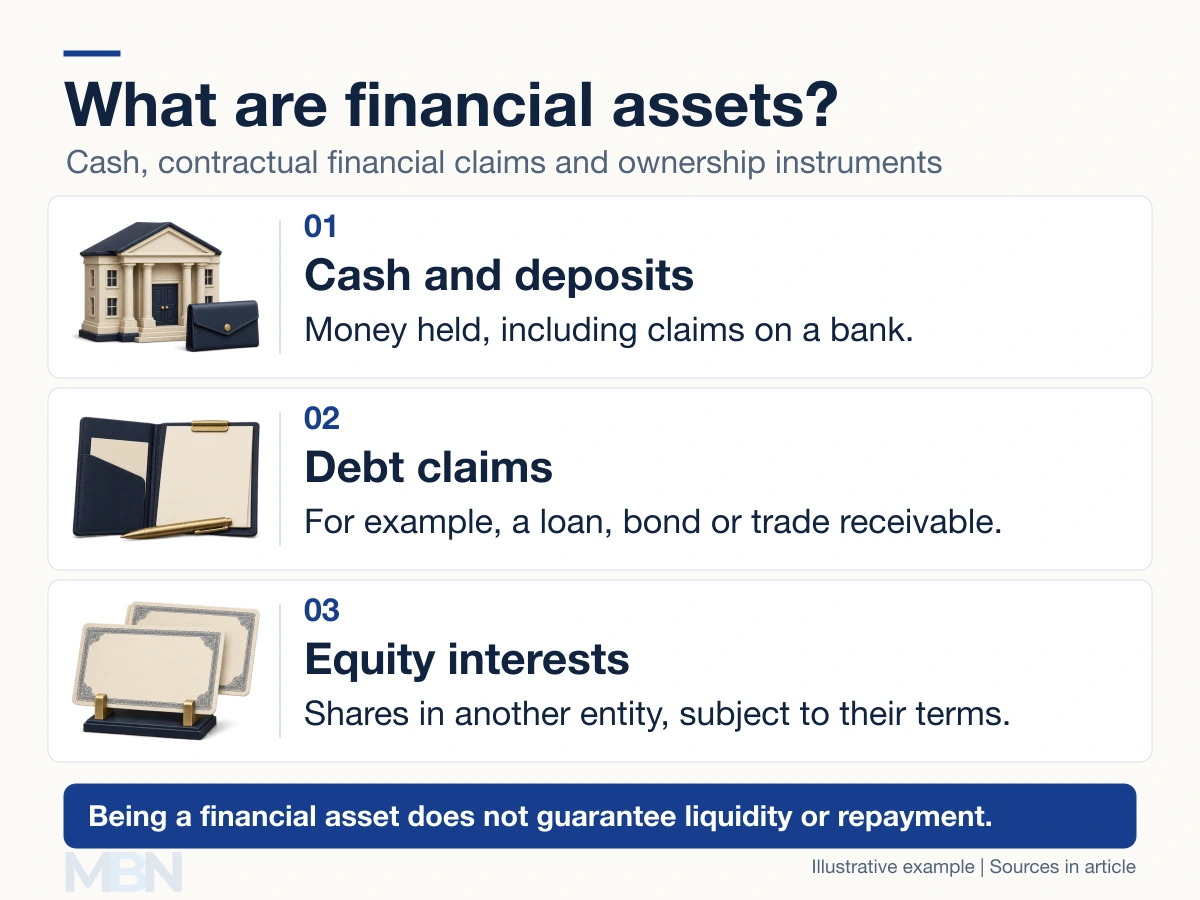
Debt, equity and other claims
IAS 32 defines financial assets for IFRS accounting. A trade receivable is a seller’s contractual claim for payment. A loan or bond gives its holder rights specified in the agreement, including repayment and any interest.
Interest need not all be paid at maturity: some bonds pay periodic coupons, while others have different payment terms. A promise to pay does not establish that the issuer will perform it.
A share is an equity interest in another entity. Ordinary shareholders generally participate in the residual value after other claims, with voting and distribution rights determined by the share terms. Dividends are not automatically guaranteed, and shares do not all have identical redemption or transfer rights.
A certificate of deposit is a bank deposit with specified terms. Rates can be fixed, variable or otherwise structured, and early withdrawal or sale may be restricted. “CD” alone does not establish one guaranteed rate or unlimited access.
A financial asset for one party can be a liability for another
Suppose company A lends $5,000 to company B. Ignoring interest, fees and impairment, A has a $5,000 loan receivable, while B has a $5,000 obligation to repay. A’s right is the financial asset; B’s obligation is the liability.
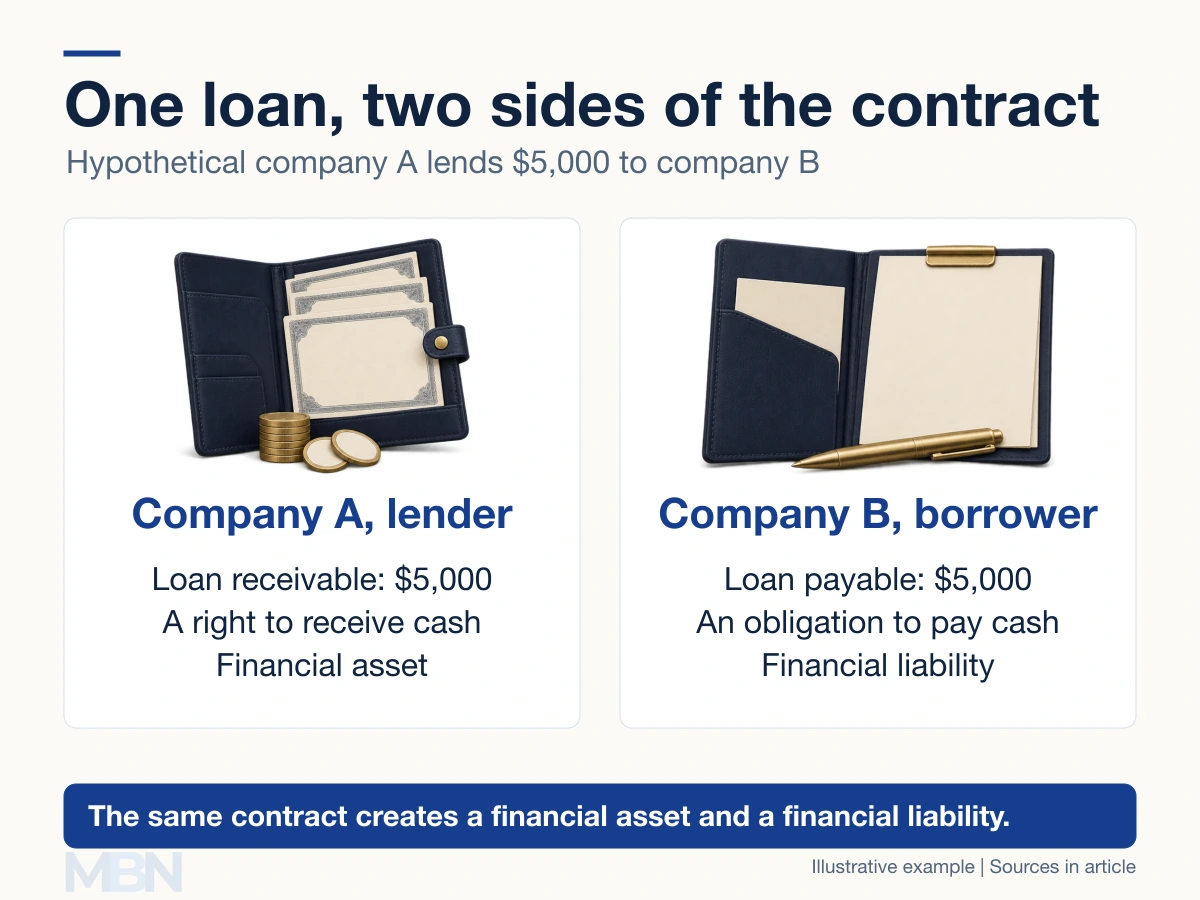
The IFRS Foundation’s IAS 32 overview explains how financial instruments are presented as assets, liabilities or equity. Classification depends on the rights and obligations, not simply the instrument’s name.
Derivatives require the same care. A derivative contract with a positive value for its holder may be a financial asset, while a negative value can represent a liability. It is inaccurate to describe every option or futures position as an asset at all times.
Valuation is not one universal cash-out price
Under IFRS 9, financial-asset measurement depends on the instrument and applicable classification. Categories include amortized cost and fair value, with fair-value changes reported through profit or loss or, where specified, other comprehensive income.
Amortized cost reflects the effective-interest method and relevant adjustments, including expected credit losses where required. It is not necessarily the price someone would pay today. Fair value is also an accounting measurement, not a promise of a particular execution price.
For a hypothetical holding of 100 quoted shares at $20 each, the simple quoted value is $2,000 before transaction costs and other applicable adjustments. That value can exist before any sale; financial assets are not valueless until converted into cash.
Liquidity and risk differ across assets
The SEC’s liquidity explanation describes how quickly an investment can be sold without a substantial price impact or cost. A thinly traded bond or private-company share may be difficult to sell, while some physical commodities have active markets.
Liquidity, credit risk and price risk are separate. A readily tradable share can still fall sharply. A highly rated debt claim can still have transfer restrictions. Financial assets also belong to a different accounting category from IAS 38 intangible assets such as qualifying patents and software rights.
Last checked and updated on November 5, 2026 by the MBN editorial team.