
If you are considering funding your retirement by downsizing your home – selling it and moving into a smaller property – and using the spare money to pay for your pension, ‘be careful’ a Royal London report warns. Your dream could easily turn into your worst nightmare.
Millions of Britons are going to reach retirement with either no money in their pension pot, or nowhere near enough. Studies suggest that up to three million people in the UK plan to use the value of their house to fund their retirement years.
They plan to sell their home and move into a smaller and much cheaper one – downsizing – when they retire, and use the spare cash to make up for the pension shortfall, says Steve Webb, Director of Policy at Royal London. Mr. Webb was a Liberal Democrat Member of Parliament and Pensions Minister in the coalition government from 12 May 2010 to 8 May 2015.
 A higher percentage of older Britons voted to leave the European Union. Were the ones who were relying on downsizing to fund their retirement aware that leaving the EU might mean less money for them? (Image: twitter.com/stevewebb1)
Downsizing an incredibly risky strategy
Mr. Webb warns that relying just on the value of one’s home to fund retirement is an ‘incredibly risky strategy’.
According to the Royal London report, for a large number of people, the downsizing plan for retirement heaven could well turn out to be a living hell.
The report authors estimated what income people would have if they downsized from an average detached property to a typical semi-detached one.
An average detached home is worth approximately £310,000, while a semi-detached house can be bought for about £197,000. This means that somebody who downsizes would expect to have a pot of about £113,000.
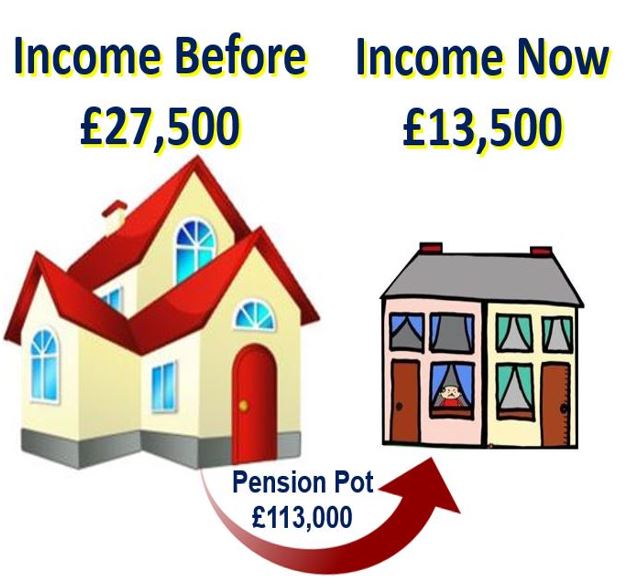 Would you be happy with a 50% decline in your living standards, after having moved from a nice-sized property into a little one?
If you use £113,000 to buy an annuity, you could end up with an annual income of approximately £13,500, which would include the income from the annuity plus a full state pension, say the report authors.
However, an average worker earns about £27,500 per year – which means a 50% drop in income on retirement to £13,500. For the vast majority of people, the authors believe, this would be an unacceptably steep fall in living standards.
A downsizing delusion
Regarding people’s plan to live off the money they get when they downsize, Mr. Webb said:
“Hoping to live off the value of your home could be a downsizing delusion for millions of people. Even with today’s record house prices, very few people could fund a retirement by selling up and moving to a smaller property.”
“In addition, house prices can be volatile, not least in the light of the recent Brexit vote, and depending on the value of a single asset – your home – to fund your whole retirement is an incredibly risky strategy.”
Since the referendum of 23rd June, when Britons voted to leave the European Union, the expectations for house price growth over the coming year have been revised dramatically – downwards. The Royal Institution of Chartered Surveyors said there is no chance after the referendum that house prices will continue their upward trend like before.
The Royal London report authors stressed that the figures they used were optimistic – people are likely to end up with a much smaller pot. They had not factored in the fees that you would have to pay for purchasing and selling, including stamp duty, which would reduce the size of the total, especially in London where prices are higher.
Older people earn more than the national average
They also based their figures on average wages across all age groups. We tend to earn more the older we get, so the income shock would be even greater for people earning more than the national average for all age groups.
If a couple are relying on downsizing, they must bear in mind that they do not have two properties – they will have to share that pot.
According to the authors, people buying and selling outside London could expect on average to earn less than two-thirds of their pre-retirement income.
Selling a London home
Downsizing works better if your property is in London and you plan to buy a smaller one outside the capital. A typical detached home in London is worth over £800,000. If you sell it and move to, for example Hastings in East Sussex, and buy a semi for £190,000, you would have a nice nest egg for your retirement.
What if your adult children have not bought their property yet? What if your adult children still live with you? What will happen when you want to sell your property and move into a smaller one? More people reaching retirement age today have their adult children living with them because they cannot get onto the property ladder.
You could be paying off other loans that continue after you are 65 years old. Bear in mind that you might be still paying loan installments when you plan to retire. Could you afford it if your income dropped by 50%?
Video – UK pensions
This short Nutmeg video explains the main types of pensions there are in the UK: 1. Workplace. 2. Personal. 3. State.
