
A bad debt is an amount owed that the creditor considers uncollectible, either wholly or partly. It can arise from a loan or from an unpaid customer invoice. An overdue payment is not automatically a bad debt.
The creditor is the person or business owed money; the debtor owes it. Bankruptcy can affect collection, but it is not a requirement for every debt to become uncollectible.
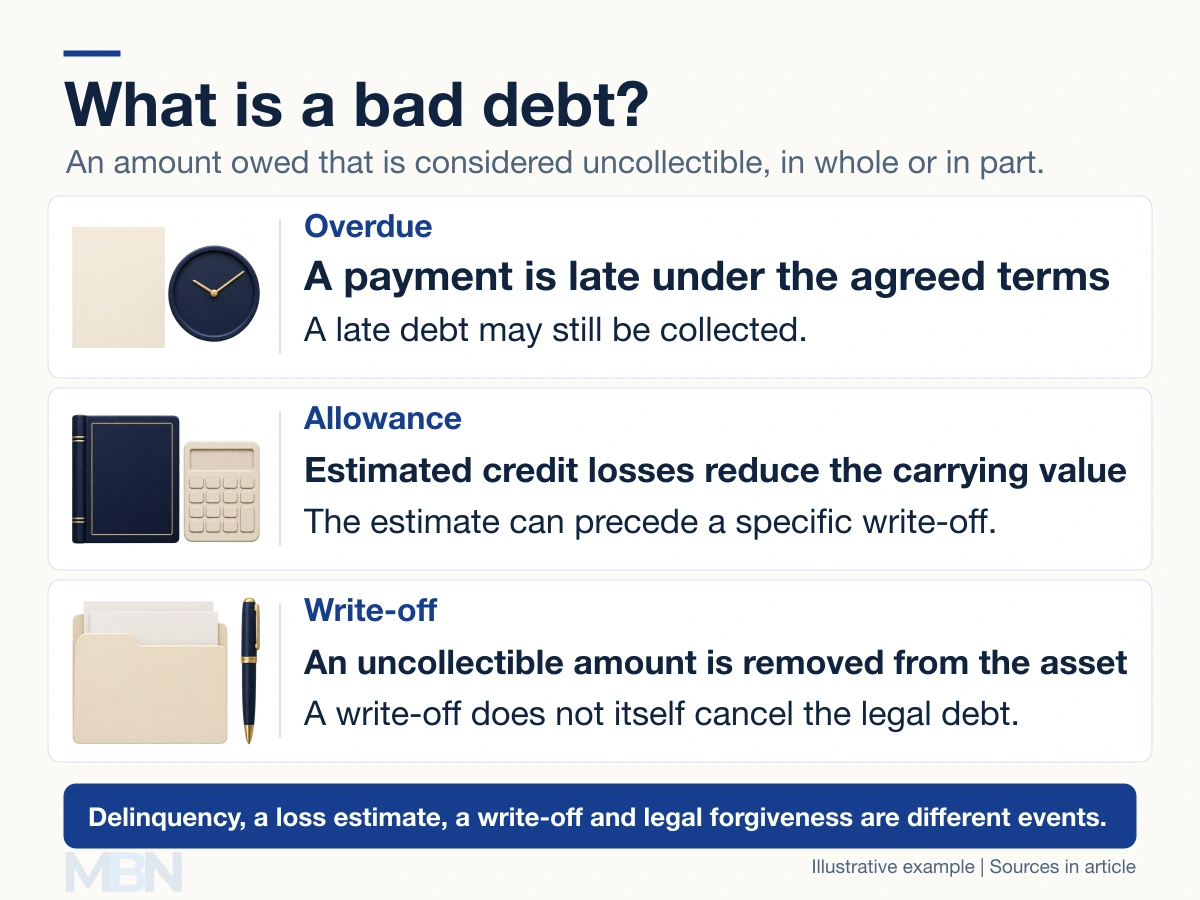
How are overdue, doubtful and bad debts different?
Delinquent means a payment is late under the agreement. Doubtful describes uncertainty about collection. A write-off removes an amount that meets the applicable uncollectibility criteria from the recorded asset.
There is no universal rule requiring every company to write off an entire loan simply because it is 90 days overdue. Accounting rules, bank regulatory classifications and collection decisions serve different purposes.
What is a credit-loss allowance?
An allowance reduces an asset’s carrying value for estimated credit losses before the final amount collected is known. The FDIC explains the US current expected credit losses framework, or CECL. Other accounting frameworks have their own requirements.
Under IFRS 9, write-off applies when there is no reasonable expectation of recovering all or part of a financial asset’s contractual cash flows. An estimate of credit losses and a later write-off are therefore different steps.
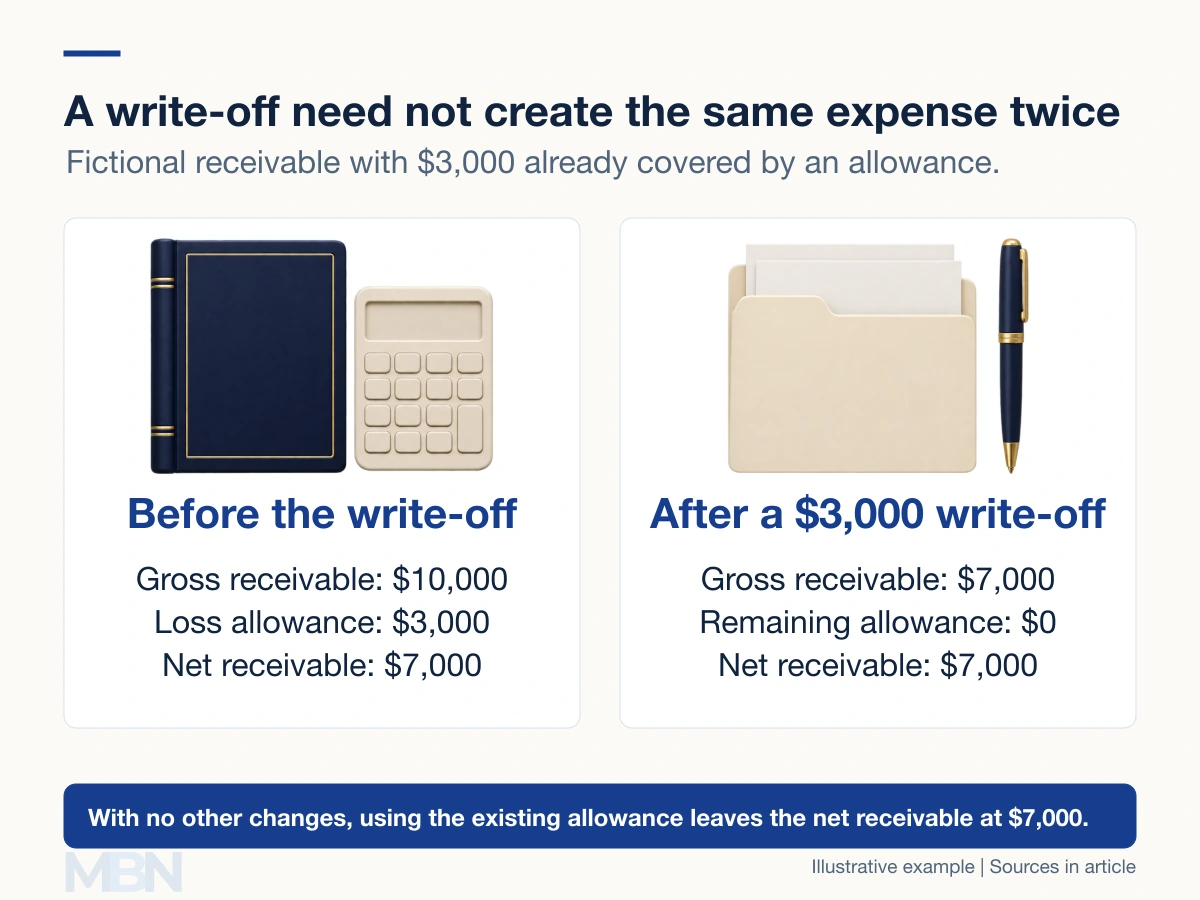
In this simplified example, a $10,000 receivable has a $3,000 allowance and a $7,000 net carrying amount. When the covered $3,000 is written off, the gross receivable and allowance both fall by $3,000.
The net amount stays $7,000, assuming no other changes. The original loss expense is not automatically charged a second time. Further deterioration in the remaining balance could require another loss estimate.
Does writing off a debt forgive it?
Not by itself. The CFPB distinguishes an accounting charge-off from cancellation of the borrower’s obligation. Collection may remain possible, subject to the contract, applicable law and any later settlement or discharge.
Is the accounting loss always tax-deductible?
No. The IRS distinguishes business and nonbusiness bad-debt deductions. US nonbusiness bad debts generally must be wholly worthless; qualifying business debts can have different partial-worthlessness rules.
For unpaid sales, whether the amount was previously included in taxable income matters. IRS Publication 334 explains why a cash-basis business generally cannot deduct an unpaid invoice never included in income. Accounting recognition and tax deductibility need not occur together.
What about personal-finance “bad debt”?
People sometimes use the phrase as a judgment about expensive or unhelpful borrowing. That is different from a creditor’s accounting loss. A loan’s interest rate alone does not make it uncollectible.
A mortgage loan is still a loan, secured on property, as the CFPB’s mortgage explanation confirms. Potential house-price appreciation does not remove repayment obligations or guarantee a profit.
Last checked and updated on November 4, 2026 by the MBN editorial team.