
A bank stress test estimates how a bank’s financial position might change under specified adverse conditions. It can examine whether the bank has enough capital or liquidity to withstand a severe shock and continue important activities.
Capital helps absorb losses. Liquidity is the ability to meet payments when due. Different exercises address different risks, so a capital stress test should not be read as a complete assessment of every threat to a bank.
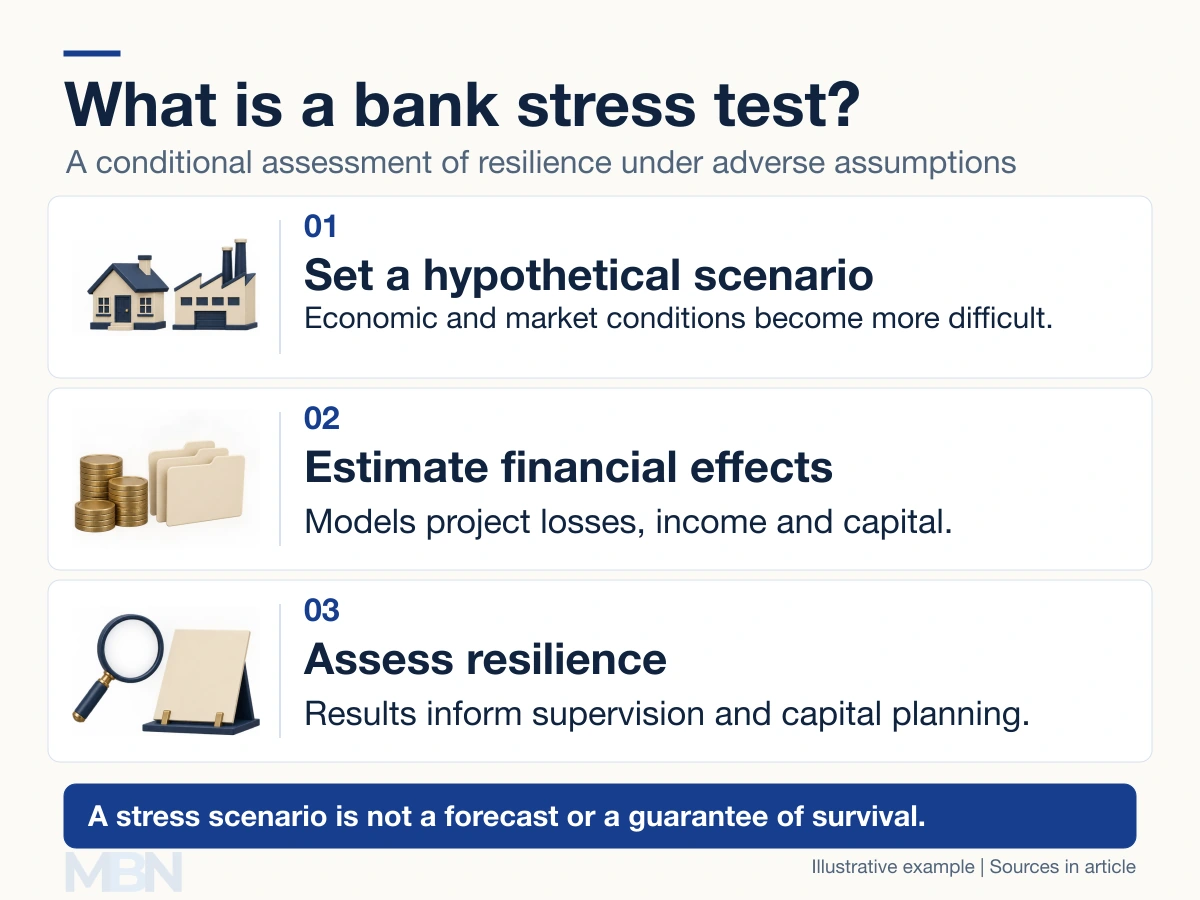
How the exercise works
Supervisors or banks specify assumptions for conditions such as unemployment, output, interest rates and property prices. Models translate those assumptions into possible loan defaults, trading losses, income and other changes.
The Federal Reserve explains that supervisory scenarios are hypothetical stresses rather than forecasts. A severe scenario asks what could happen to banks under those conditions, not whether the authority expects those conditions to occur.
A test may combine several shocks. A rise of two percentage points in an interest rate, for example, differs from a 2% proportional rise. The scenario’s units, timing and starting values matter.
A simple capital example
Suppose a fictional bank starts with $12 million of qualifying capital and $100 million of risk-weighted assets. Its capital ratio is 12%. If modeled effects reduce capital by a net $5 million while risk-weighted assets stay unchanged, the ratio falls to 7%.
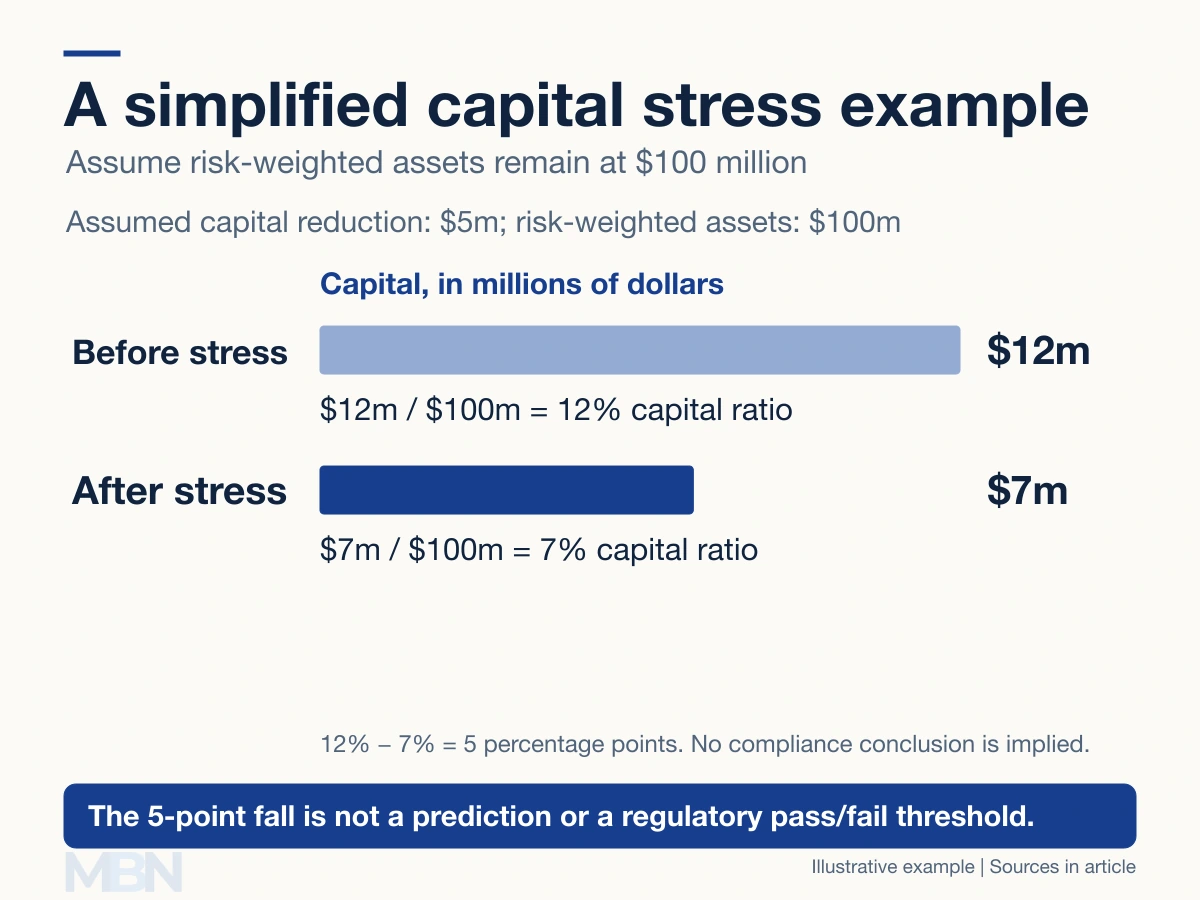
The decline is five percentage points. It is not a five-percent proportional fall, and the assumed 7% result does not by itself determine a regulatory pass or failure. Actual requirements depend on the capital measure, bank, buffers and applicable framework.
Recent exercises are dated evidence
In its June 24, 2026 results, the Federal Reserve reported that the large banks tested were positioned to withstand its severe-recession scenario and continue lending. The scenario included a 39% fall in commercial property prices and a 30% fall in house prices.
The Fed said the 2026 results would not change large-bank capital requirements, which would remain in place until 2027. Those scenario figures were hypothetical shocks, not realized price falls. The 2026 scenario publication sets out the underlying assumptions. A favorable result applies to the institutions, models and scenario examined.
The Bank of England published its 2025 Bank Capital Stress Test results on December 2, 2025. UK prudential supervision involves the Bank and the Prudential Regulation Authority, or PRA; the former Financial Services Authority is not the current regulator.
The EBA’s 2025 EU-wide exercise covered 64 banks from 17 EU and European Economic Area countries. Its results contribute to supervisory assessment rather than constituting a universal guarantee about all European banks.
What a stress test cannot establish
Results depend on data quality, models, assumed relationships and the shocks selected. A different crisis can expose risks the scenario did not capture. Staff training and operational crisis exercises can support resilience, but they are not synonymous with a quantitative capital stress test.
Historical discussion of accountability
In this earlier Brookings Institution video, Paul Tucker discusses how public stress-test results can improve supervisory accountability. It is historical commentary, not a presentation of current test results or rules.
Last checked and updated on November 6, 2026 by the MBN editorial team.