
A bank is a regulated financial institution that commonly accepts deposits, provides credit and processes payments. The legal meaning and permitted activities vary by country; central banks have a different public-policy role from ordinary customer-facing banks.
The International Monetary Fund (IMF) identifies deposit-taking and lending as common commercial bank activities. A bank deposit is a claim against the bank, rather than a customer’s separate pile of cash kept untouched in a vault.
What banks do for customers
Transaction accounts, often called checking or current accounts, support receipts and payments. Savings and term deposits have different access and interest arrangements. Some checking accounts pay interest; fees and account features vary.
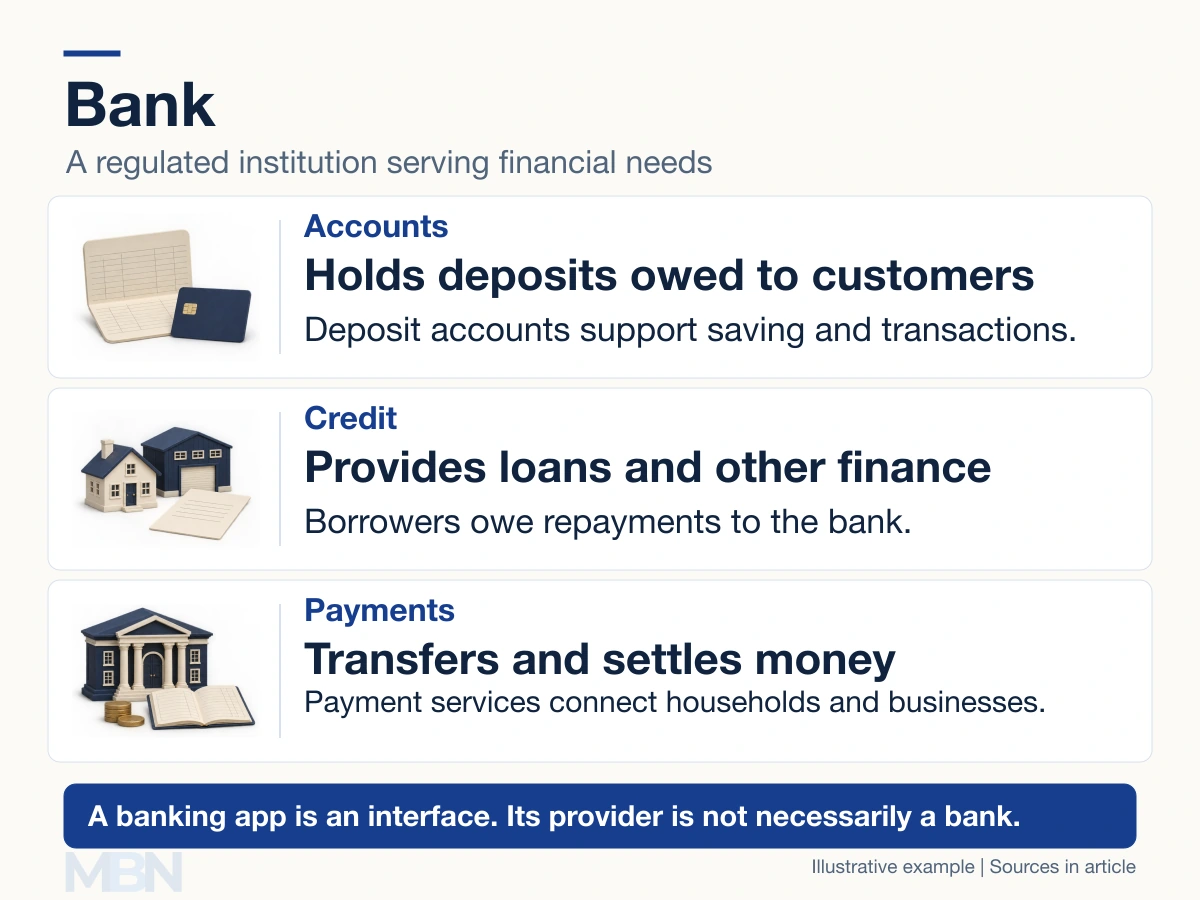
Banks lend to households and businesses through products such as mortgages, business credit and personal loans. They can also provide cards, foreign exchange and other authorized services. A banking group may include several different regulated businesses.
How bank lending creates deposits
The Bank of England explains that a bank making a loan normally creates a matching deposit in the borrower’s account. It does not simply pass a particular saver’s existing deposit to the borrower.
For example, crediting a $10,000 loan produces both a loan asset and a deposit liability on the bank’s balance sheet. The borrower has spending power and an obligation to repay. The bank still needs funding, capital and liquidity, and must manage the risk of nonpayment.
Banks can earn interest and service fees, but funding costs, operating expenses and loan losses reduce profits. Taking deposits and lending therefore does not guarantee a profit.
Different banking roles
Retail banking serves individuals; business and corporate banking serve organizations. Investment banking includes securities issuance and transaction advice. These activities can coexist within a financial group and are not an exhaustive legal classification of every bank.
A central bank conducts monetary policy and supports the monetary system. Its tasks and governance are set by law. It generally serves banks and public institutions rather than offering ordinary retail accounts.
Why capital and liquidity matter
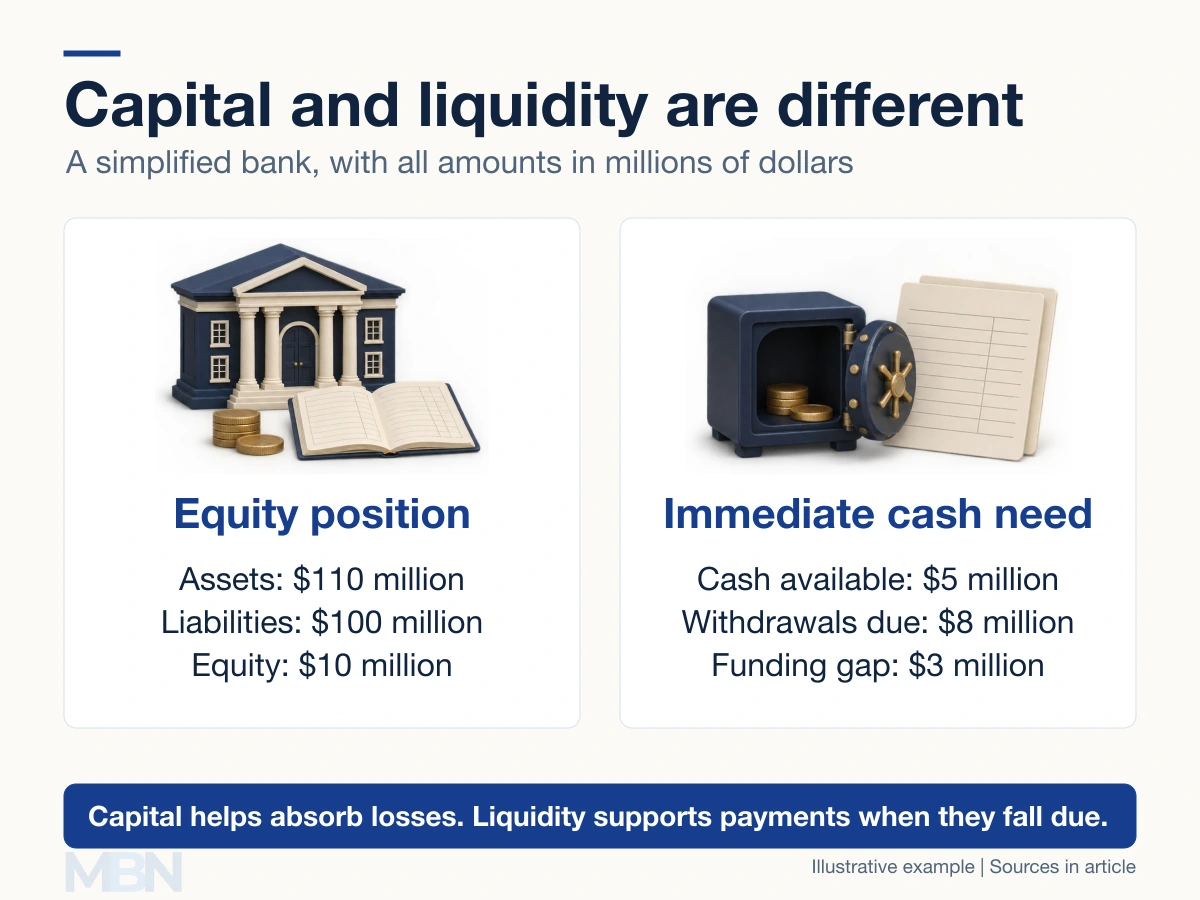
Capital and liquidity address different risks. Capital provides capacity to absorb losses; liquidity concerns meeting payments when due. They are related, but are not interchangeable.
Suppose a bank has $110 million in assets and $100 million in liabilities, leaving $10 million in equity. If only $5 million is immediately available as cash and $8 million of withdrawals fall due, it needs another $3 million of liquidity. A positive equity figure alone does not settle those withdrawals.
Supervision, deposit protection and failure-resolution arrangements vary by jurisdiction and do not remove every risk.
The FDIC also distinguishes banks from nonbank financial apps. An app’s branding alone does not establish where deposits are held or what protection applies.
A brief historical perspective
Banking institutions have developed over centuries. Monte dei Paschi di Siena traces its origins to 1472, beginning as a charitable pawn-lending institution. Bank of Montreal began business in 1817. These histories illustrate different origins without implying that age guarantees a bank’s present financial strength.
Last checked and updated on November 10, 2026 by the MBN editorial team.