
A commercial bank is a deposit-taking institution that provides services such as loans, transaction accounts and payments to households and businesses. Its permitted activities depend on the country and its banking authorization.
The International Monetary Fund (IMF) identifies accepting deposits and providing finance as common commercial banking services. The term can also refer more narrowly to a banking group’s business-customer division, so context matters.
What a commercial bank does
A checking account, commonly called a current account in the United Kingdom, supports everyday payments. Savings and term-deposit accounts serve different saving needs. Fees, access rules, interest and minimum balances depend on the product rather than a universal ranking of account types.
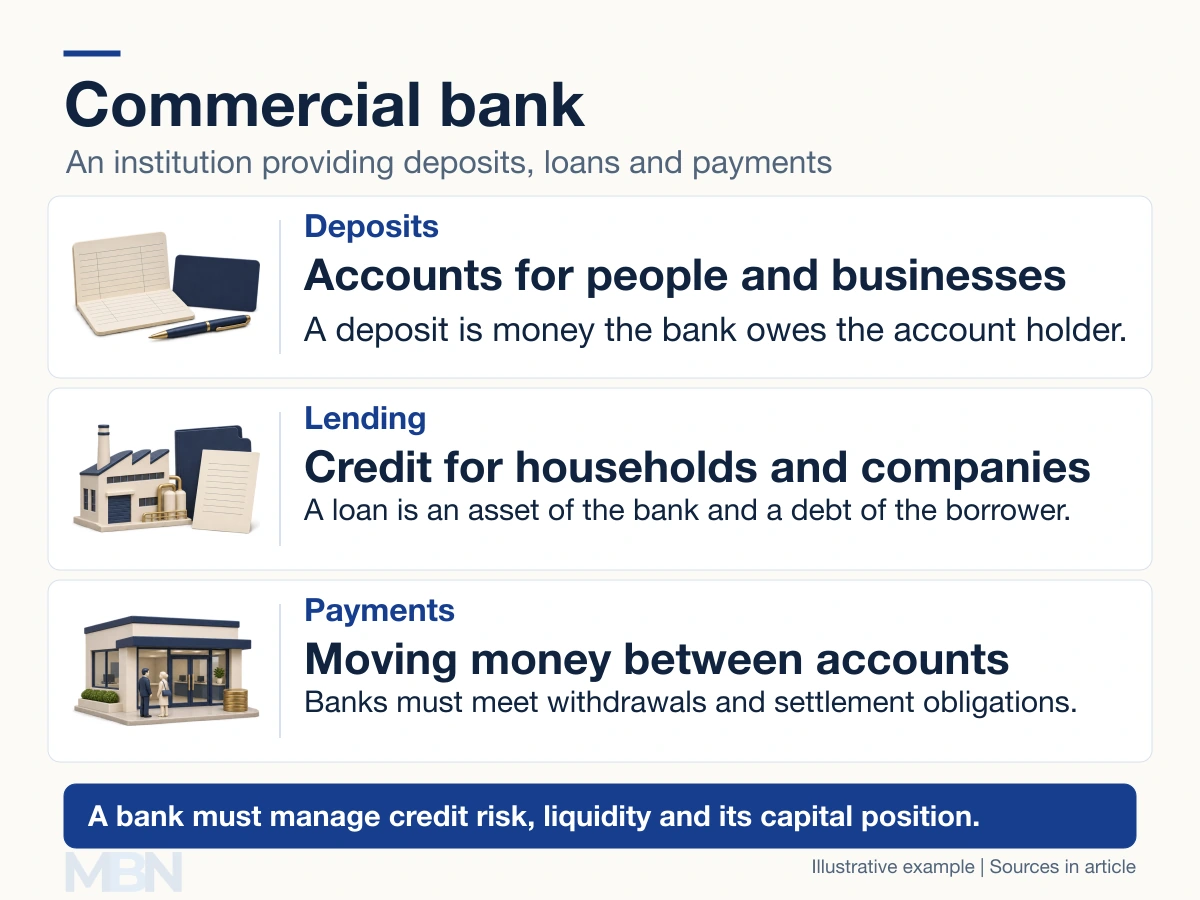
A bank may provide mortgages, business credit, personal loans, cards and foreign-exchange services. For example, a small manufacturer might use its bank for payroll payments, customer receipts and a loan to buy equipment.
A customer deposit is a bank liability: money owed to the account holder. A loan is generally a bank asset: a claim on the borrower’s future repayments.
How lending and deposits are connected
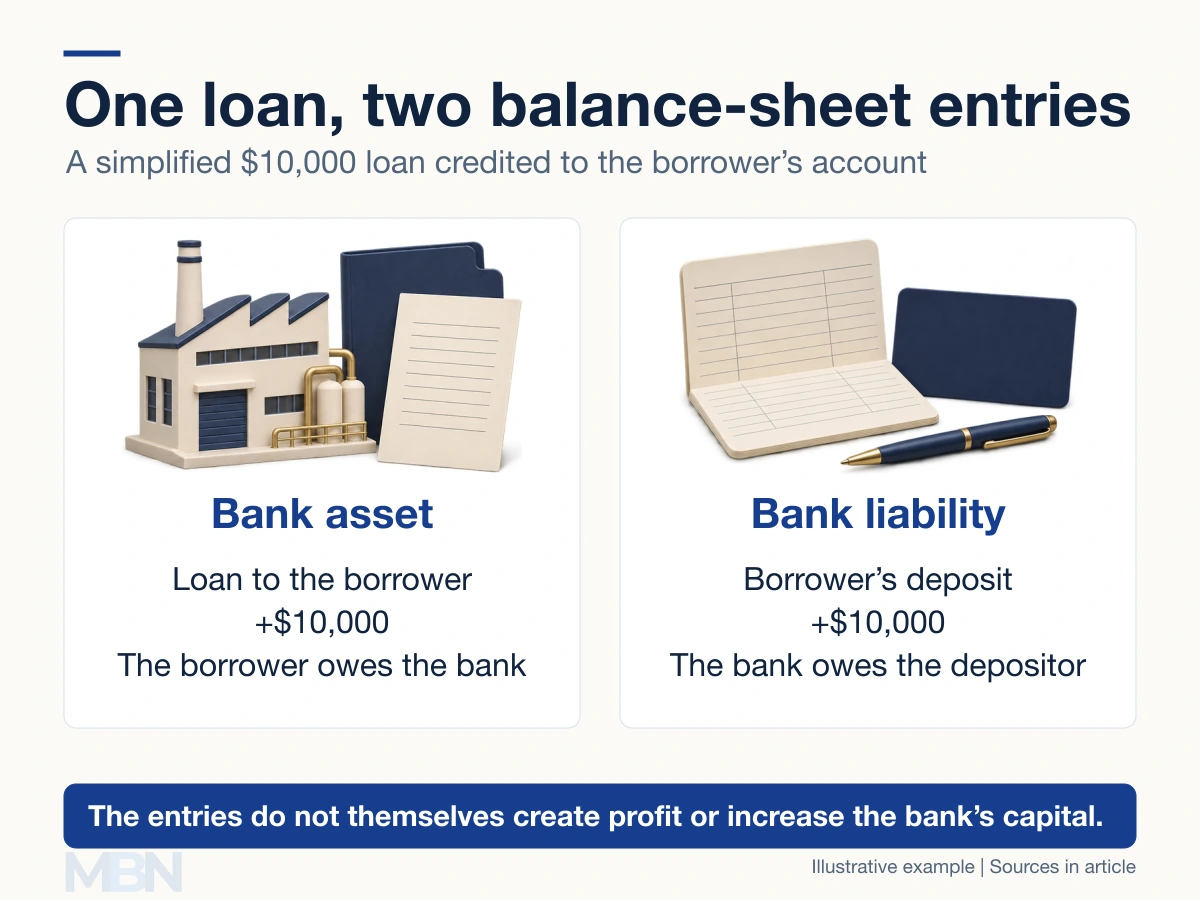
The Bank of England explains that when a bank makes a loan and credits the borrower’s account, it creates a matching deposit. It does not simply take a particular saver’s existing deposit and pass that same balance to the borrower.
For a simplified $10,000 loan, the bank records a $10,000 loan asset and a $10,000 deposit liability. The borrower gains a usable deposit but also owes $10,000. These accounting entries do not themselves produce bank profit or additional capital.
Deposits still matter as funding. If the borrower pays someone at another bank, the lending bank must settle that payment and manage its funding position. The Bank of England’s fuller explanation distinguishes deposit creation from the constraints that limit lending.
As an IMF presentation on bank money creation explains, profitability, credit risk, withdrawals and liquidity and capital requirements constrain lending. Creating deposit money does not give a bank unlimited spending power.
How it earns income
Banks earn interest on lending and investments and may charge for services. Interest paid on deposits and other borrowing, operating costs and credit losses reduce earnings. A higher loan rate is therefore not the same as an equally large profit margin.
Commercial and investment banking
Investment banking includes helping issuers raise money through securities and advising on transactions. A financial group can contain both commercial banking and securities businesses, often in separate regulated entities.
In the United States, the 1999 Gramm-Leach-Bliley Act changed restrictions on affiliations among banks, securities firms and insurers. It did not remove all banking regulation. Banking structures and names vary internationally; commercial and investment banks are not an exhaustive classification of every financial institution.
Last checked and updated on November 10, 2026 by the MBN editorial team.