
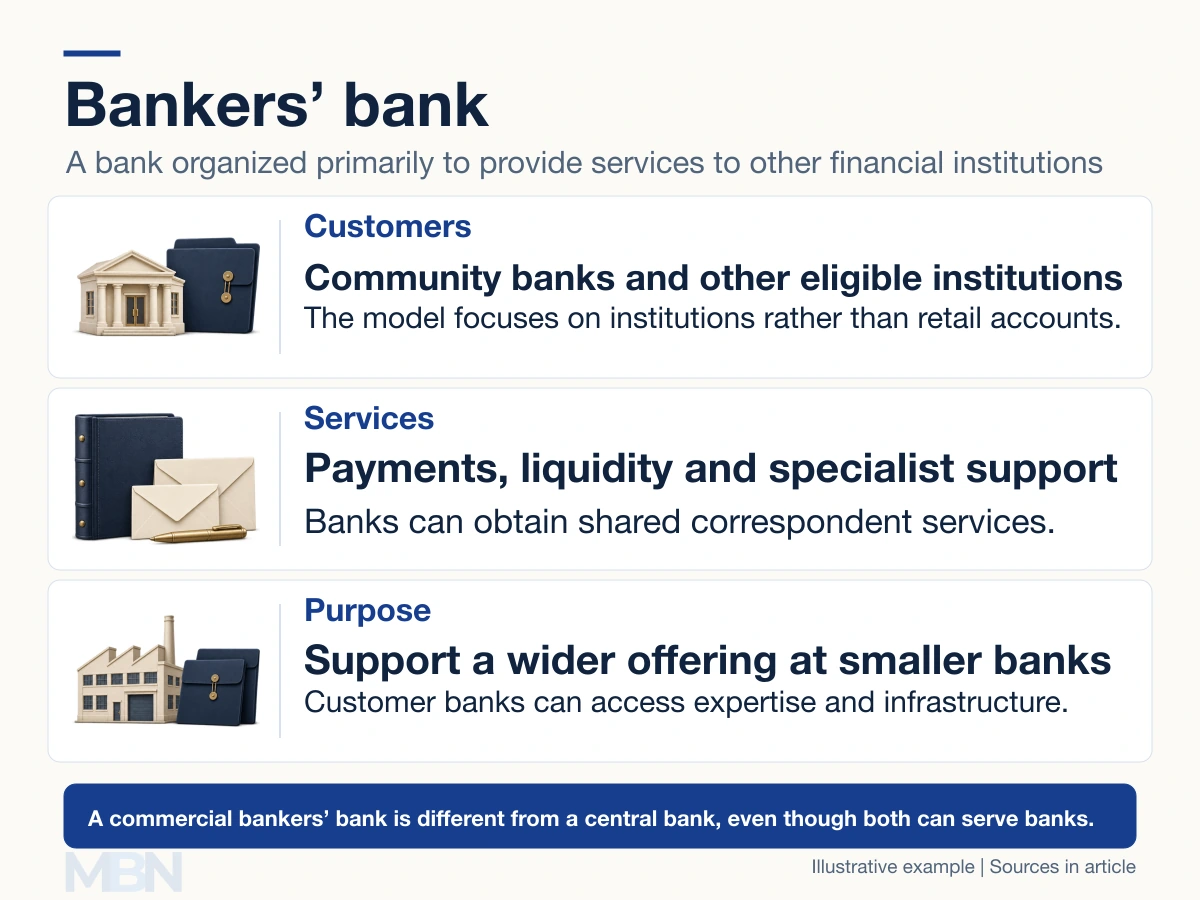
A bankers’ bank is a bank organized primarily to serve other financial institutions, especially community banks. In the US model, it is generally owned by the institutions it serves and provides wholesale services rather than ordinary retail banking to the public.
It can help smaller banks access payment infrastructure, liquidity and specialist expertise without building every capability themselves. The customer’s local bank remains the institution providing the retail account or business relationship.
What services does it provide?
Federal Reserve research published in January 2026 describes bankers’ banks as supporting community banks and participating in interbank funding markets. Their lending can provide liquidity support to other depository institutions, rather than functioning like a conventional retail loan book.
Services can include correspondent accounts, payment processing, securities-related services, borrowing arrangements and loan participations. The exact offering depends on the institution. For example, The Bankers Bank lists payment, lending and other correspondent services.
A correspondent bank supplies services to another bank. Bankers’ banks are one form of correspondent provider; larger commercial banks can also provide correspondent services without being bankers’ banks.
How a loan participation works
Suppose a community bank originates a $5 million business loan and sells a $2 million participation to another institution. The originating bank retains $3 million, or 60% of the exposure; the participant takes $2 million, or 40%.
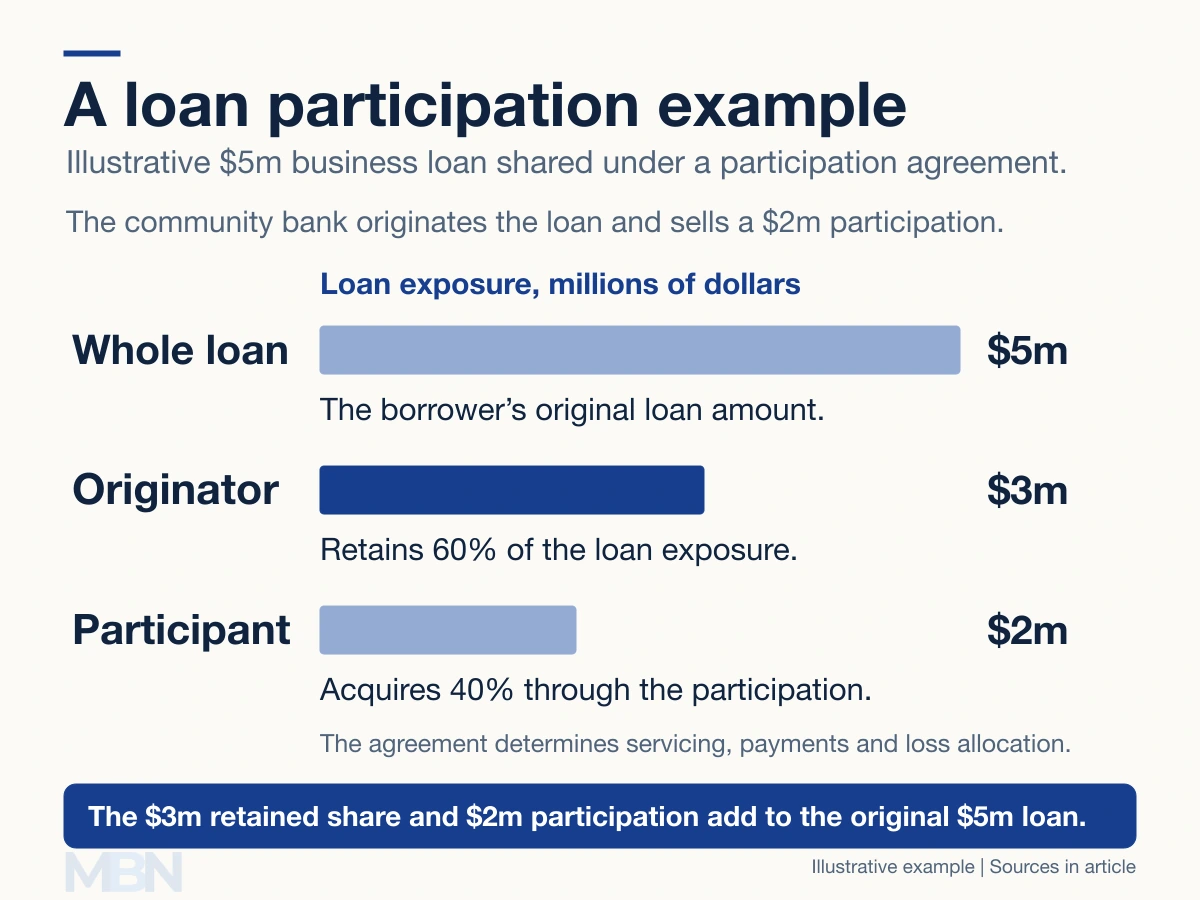
This arrangement can spread exposure and allow the originating bank to serve a larger financing need. It does not make the borrower safer or eliminate losses. The participation agreement determines servicing, payment rights and how losses are allocated.
The participant must assess the credit and its contractual position. Participation should also be distinguished from the borrower taking two unrelated loans: the institutions are sharing an interest in the underlying financing.
Who owns it and who can be a customer?
Community-bank ownership is central to the business model. The Bankers Bank describes itself as owned by community banks, for example. That structure can align its service offering with shareholder banks, but it does not guarantee lower prices or superior performance.
Formal definitions vary with the purpose of a rule. The Federal Reserve’s Regulation D interpretation permits specified limited business with certain nonbank customers, including eligible related organizations and bank personnel. Saying that every bankers’ bank can serve only community banks, without exceptions, is too absolute.
How it differs from a central bank
A central bank is sometimes called a “bank for banks” because it provides reserve accounts, settlement services or eligible lending facilities. It also has public responsibilities that a commercial bankers’ bank does not have.
The Federal Reserve System’s functions include monetary policy and financial stability. A privately owned bankers’ bank is a commercial service provider, not a national monetary authority, even where some of their banking services appear similar.
Last checked and updated on November 11, 2026 by the MBN editorial team.