
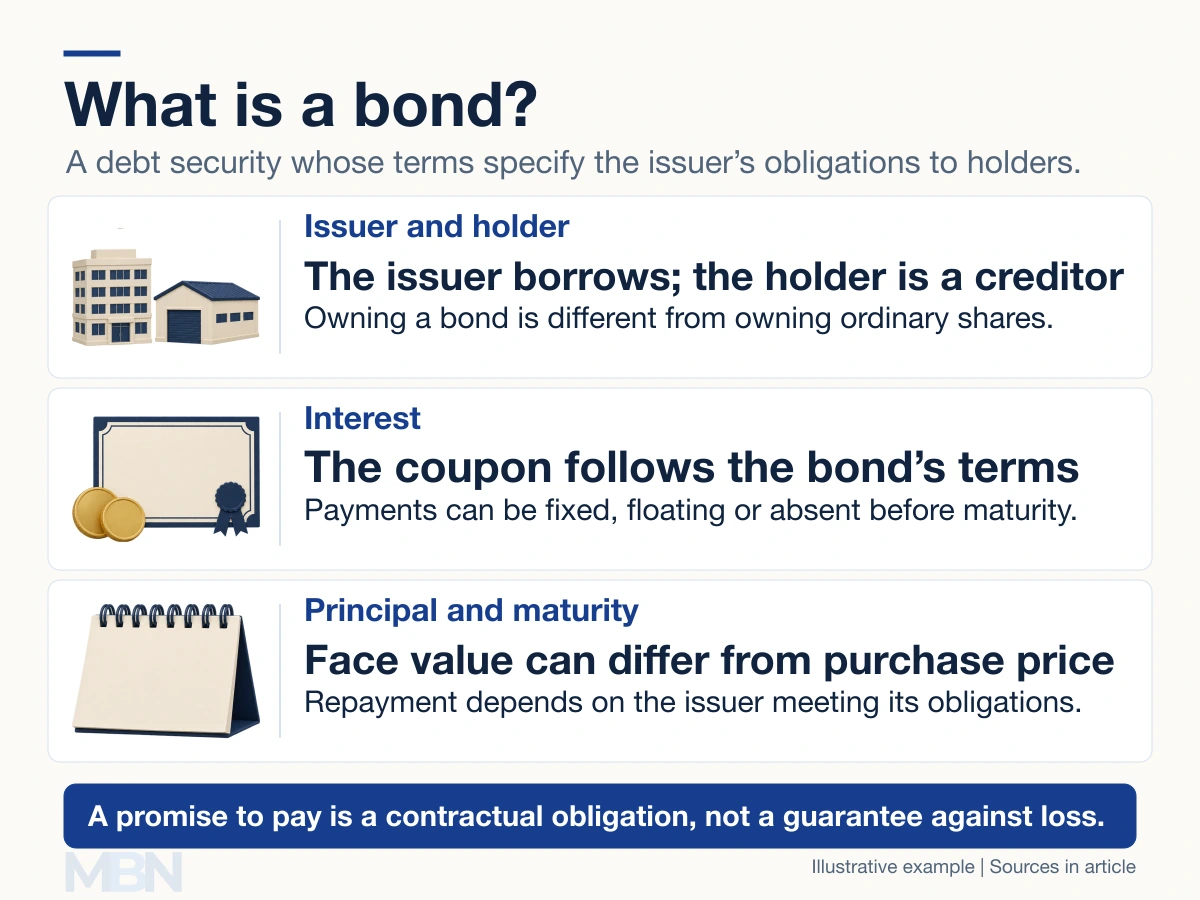
A bond is a debt security. Its issuer borrows money and undertakes specified payment obligations to bondholders. The terms identify matters such as interest, principal, maturity and repayment priority. Those promises do not eliminate the risk of loss.
Investor.gov distinguishes bondholders, who are creditors, from shareholders, who hold equity. Buying an existing bond from another investor transfers the security; it does not necessarily provide fresh money to the issuer.
Who issues bonds, and why?
Companies, national governments and local public bodies issue debt to finance operations, investment or refinancing. The purpose and repayment backing depend on the issuer and security.
The UK Debt Management Office defines a gilt as a sterling-denominated UK government bond. US Treasury securities are obligations of the US government. These labels should not be treated as universal descriptions of every government-related security.
What do coupon, principal and maturity mean?
The coupon is the interest payment under the terms. A fixed-rate bond pays interest based on its face value; floating-rate payments reset under a stated formula. A zero-coupon bond makes no periodic coupon payments and is commonly bought at a discount.
Face value, also called par value, is distinct from the market price. Maturity is the scheduled principal repayment date. Some bonds can be called, meaning repaid early under specified terms.
Payment structures vary. The UK’s former undated gilts had no fixed final redemption date; the last were redeemed in July 2015. Bond documents determine whether and when repayment is due.
A bond bought below face value
Assume our fictional bond has $1,000 face value, a 5% annual coupon, semiannual payments and two years remaining. Bought immediately after a coupon date for $950, it pays $25 every six months.
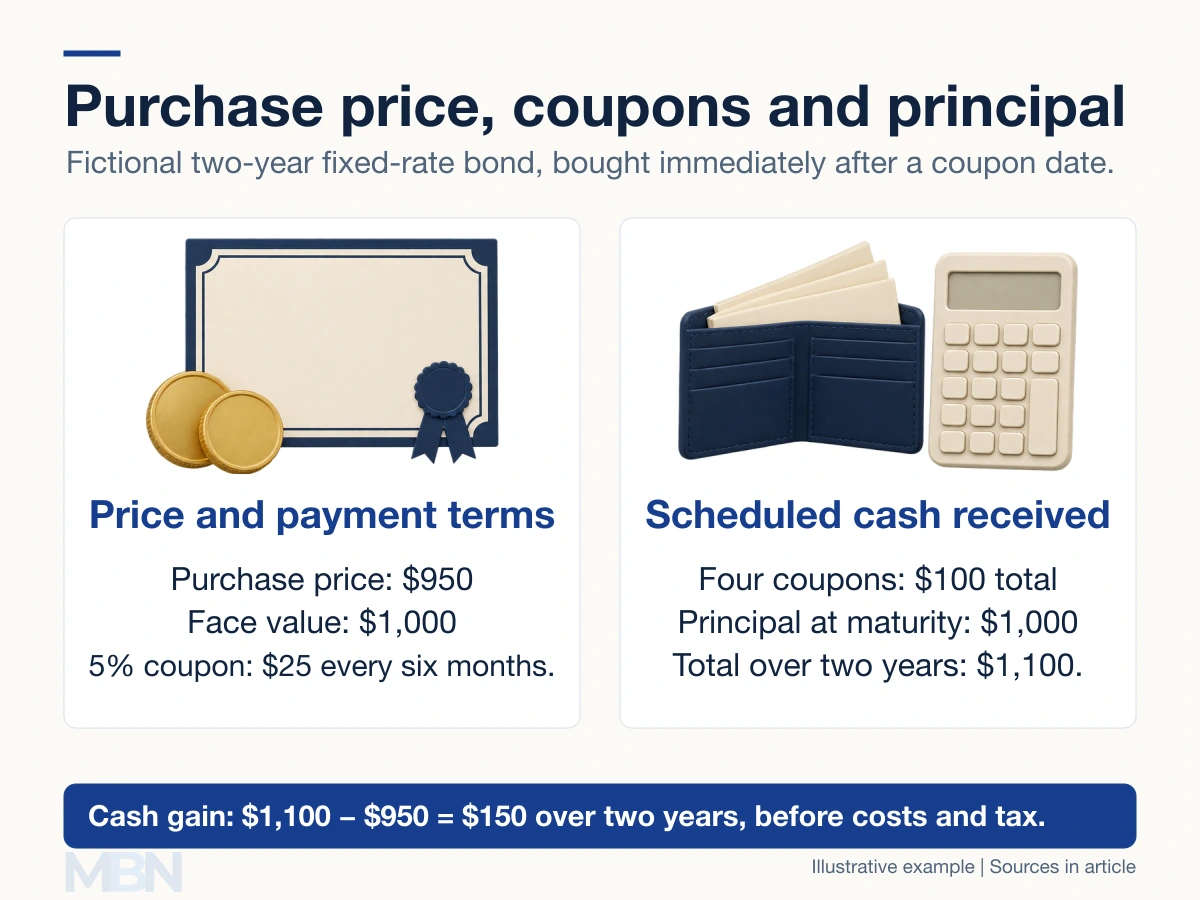
Four coupons total $100. Adding $1,000 principal produces $1,100 of scheduled receipts. If every payment is made, the cash gain is $150 before fees and tax, without reinvestment. That is about 15.79% of the $950 purchase price over two years, not an annual rate.
The issuer repays $1,000 principal in this example, rather than the investor’s $950 purchase price. Our yield explainer distinguishes coupon income, current yield and yield to maturity.
Why can bondholders lose money?
FINRA explains that default can cause loss of all or a substantial part of an investment. A legal obligation to pay does not ensure the issuer has enough money. Collateral and repayment priority affect recoveries.
The SEC’s interest-rate-risk bulletin explains why fixed-rate bond prices generally fall when market rates rise. Selling before maturity can produce a loss even when payments remain current. Inflation can reduce purchasing power, and an illiquid bond can be difficult to sell.
A call can end expected coupon payments early. Currency movements can affect a foreign-currency investment. Credit quality, duration and terms therefore matter more than a blanket statement that bonds are always safer than shares.
What are high-yield bonds?
High-yield corporate bonds are below investment grade and carry greater estimated default risk. Their higher promised yields compensate for risk; they do not guarantee superior realized returns. Ratings can change.
Is a surety bond the same thing?
No. The Surety and Fidelity Association of America describes a surety bond as a three-party guarantee arrangement. It concerns another party’s performance or payment obligations, rather than the investment-security mechanism explained above.
Last checked and updated on November 3, 2026 by the MBN editorial team.