
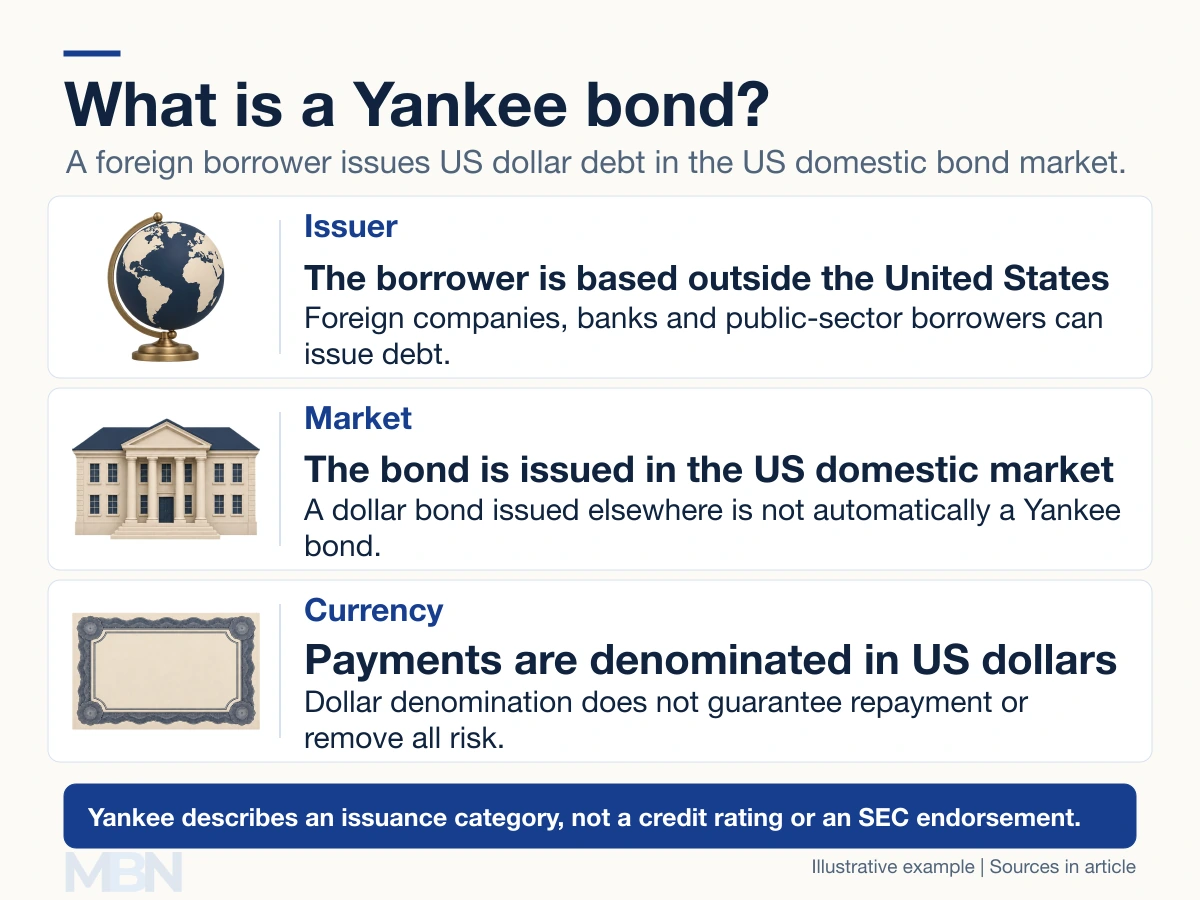
A Yankee bond is a US dollar-denominated bond issued by a foreign borrower in the US domestic bond market. The label describes the issuer, market and currency, rather than a particular credit rating or investment strategy.
The BIS foreign-issue glossary explains this classification. A non-US borrower can access US investors without requiring them to buy a bond denominated in the borrower’s home currency.
How a Yankee bond works
The borrower raises dollars and owes the interest and principal specified in the bond terms. As with other bonds, maturity, payment frequency, priority, guarantees and any early-redemption rights depend on the issue.
An offering can contain separate series with different maturities or coupons. These are not necessarily securitization tranches that absorb losses in a prescribed order. Neither a billion-dollar minimum size nor a fixed issuance timetable defines a Yankee bond.
Registration is not credit approval
Public offerings commonly use SEC registration, while applicable exemptions can support other transactions. The SEC explains that registration concerns disclosure, not whether an investment is good.
The SEC does not guarantee repayment or approve an issuer’s creditworthiness through a rating agency. A credit rating is a separate assessment, and it is not a guarantee either. The Yankee label alone does not make a bond investment-grade, high-yield or safer than another issuer’s debt.
Yankee, Samurai and Eurobond are different labels
The BIS distinguishes foreign domestic-market issues from other international debt securities. A Samurai bond is a yen-denominated foreign issue in Japan. It is not defined by the borrower having Japanese roots.
Eurobond refers to an international bond-market structure. It is not simply another name for a Yankee bond, and it does not mean a bond must be denominated in euros. ICMA’s survey definitions distinguish Eurobonds from domestic-market securities.
Does a dollar bond eliminate currency risk?
It removes the need to convert a promised dollar payment into dollars for a dollar-based holder. But exchange rates can still affect the foreign borrower’s ability to pay and the bond’s market price. A fund disclosure filed with the SEC explains this direct-versus-indirect distinction.
Suppose a fictional issuer owes a $60,000 annual coupon on a $1 million bond paying 6%. If it funds that payment from euros, it needs €48,000 at $1.25 per euro. At $1 per euro, it needs €60,000, 25% more, assuming no hedge or dollar income.
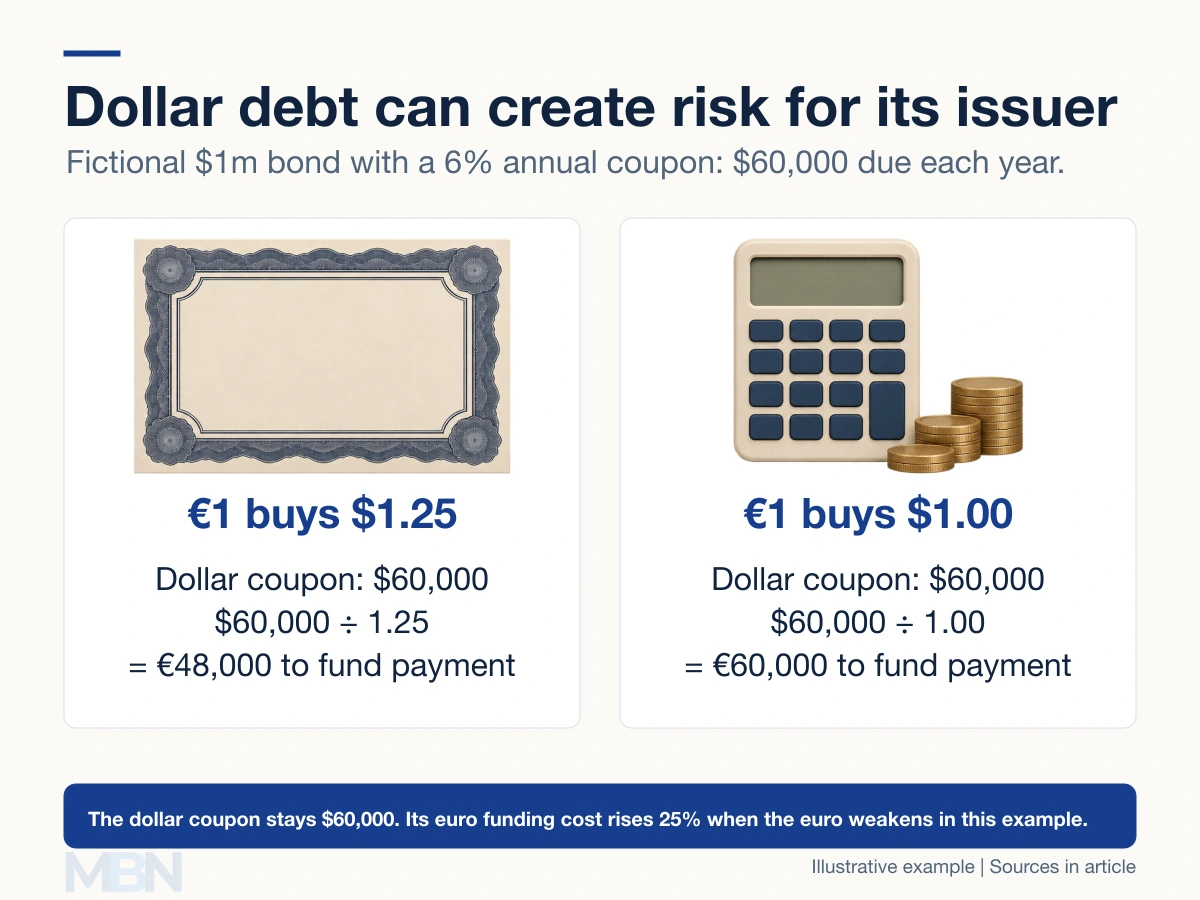
A holder measuring returns in a currency other than dollars can also face direct exchange-rate changes. Dollar denomination therefore does not remove currency risk for every investor or issuer.
What other risks remain?
Issuer default, interest-rate changes, limited liquidity, political developments and enforcement issues can affect returns. The SEC’s corporate-bond materials explain core bond risks. Foreign-issuer exposure can broaden a portfolio, but it does not guarantee diversification benefits, a higher yield or outperformance.
Last checked and updated on November 4, 2026 by the MBN editorial team.