
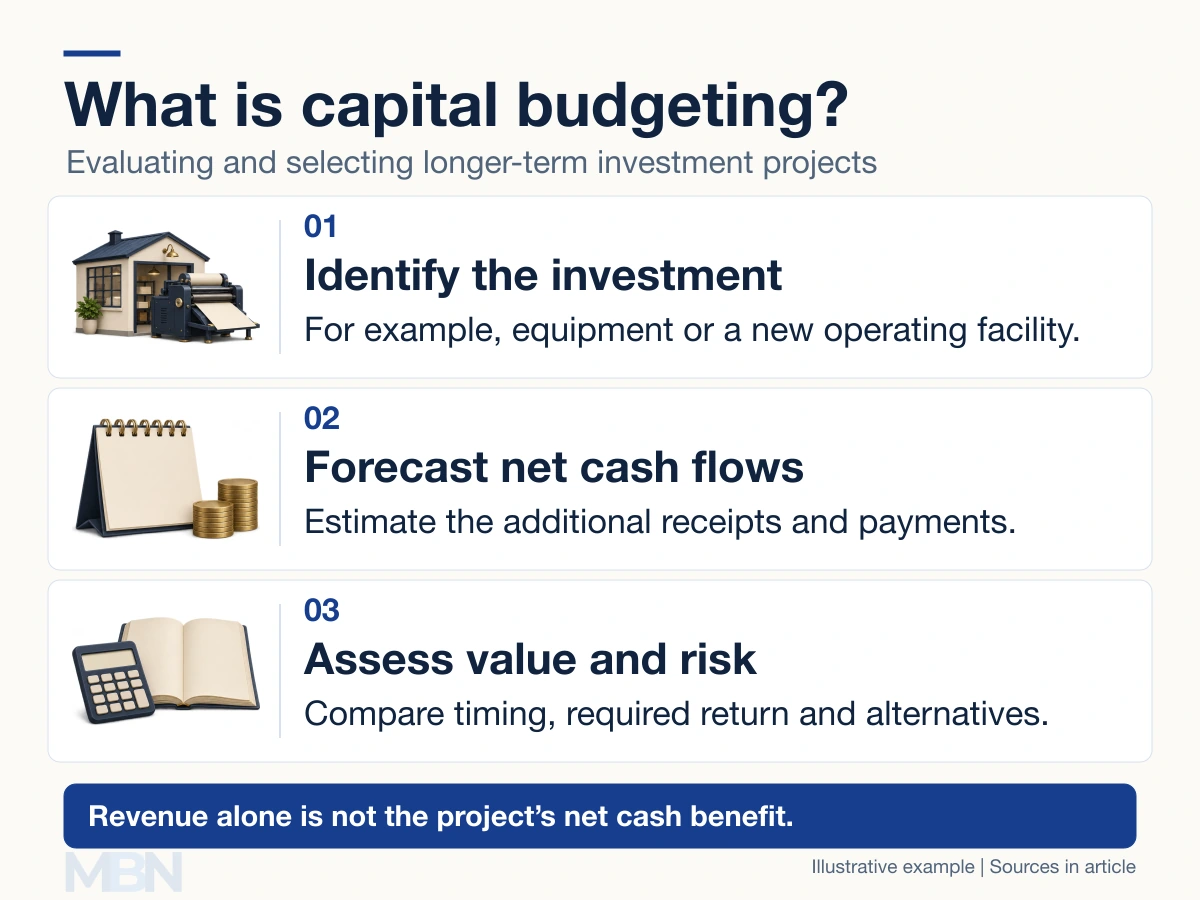
Capital budgeting is the process of evaluating and selecting longer-term investment projects. A business compares the money a project requires with the future cash benefits it is expected to produce, allowing for timing and risk.
Projects can include equipment, facilities, new products or research and development. A company may aim to increase shareholder value; a public or nonprofit organization may also assess service delivery and other objectives.
Start with relevant cash flows
The financial appraisal focuses on future cash flows that change because the project is undertaken. ACCA’s relevant-cost guidance distinguishes these from sunk costs, which have already been incurred.
Additional receipts, operating costs, taxes, working capital and eventual disposal proceeds may matter. Depreciation is an accounting charge rather than a direct cash payment, although tax consequences can affect cash flows.
For example, spending $1 million now and receiving $1.26 million net after one year gives a simple one-year return of 26%, or 0.26. But $1.26 million of sales revenue alone does not establish that return: any further project costs must also be considered.
Net present value
Net present value, or NPV, subtracts the initial investment from the present value of future net cash flows. Discounting converts future amounts into comparable amounts today using a required return appropriate to the project.
ACCA’s investment-appraisal guidance explains the treatment of relevant cash flows, tax, inflation and discounting. A positive NPV indicates expected value above the required return under the assumptions used. It is not a guaranteed profit.
A checked two-year example
Suppose a machine requires $100,000 today and produces $60,000 net cash inflow at the end of each of the next two years. Assume those net amounts already include all relevant project payments, there is no final disposal value, and the annual discount rate is 10%.
The year-one present value is $60,000 ÷ 1.10 = $54,545.45. The year-two value is $60,000 ÷ (1.10 × 1.10) = $49,586.78. Total present value is $104,132.23, giving an NPV of $4,132.23 after the $100,000 outlay.
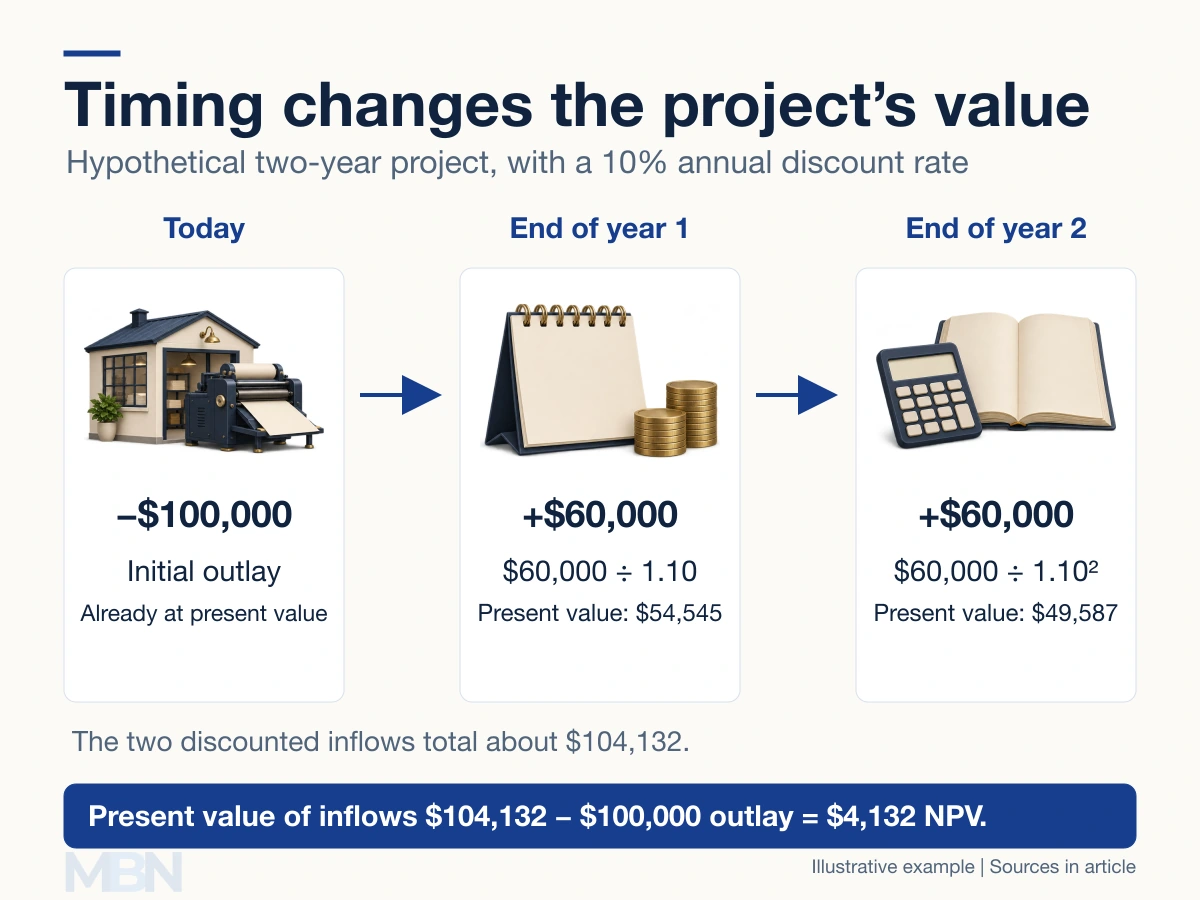
If each annual net inflow fell to $50,000, the same calculation would give an NPV of approximately negative $13,223. This sensitivity illustrates how assumptions can change the assessment.
Other appraisal methods
Payback measures how long it takes cash inflows to recover the initial outlay. Simple payback ignores the time value of money and cash flows after the cutoff. Accounting rate of return uses accounting profit, so it answers a different question from a cash-flow calculation.
The internal rate of return, or IRR, is a discount rate that makes NPV zero. ACCA explains the method and its limitations. Some cash-flow patterns can produce multiple IRRs, and percentage rankings can conflict with value comparisons between projects.
The required return and the decision
The opportunity cost of capital reflects returns required for a comparable risk. Comparing a risky operating project with any convenient bond yield can be misleading. ACCA’s cost-of-capital discussion explains the importance of an appropriate discount rate.
Appraisal assumptions should treat inflation, financing and tax consistently. Funding availability, competing projects, operational capacity and legal or strategic requirements can also constrain the decision. Financial analysis helps show the trade-offs; it cannot remove uncertainty.
Last checked and updated on November 5, 2026 by the MBN editorial team.