
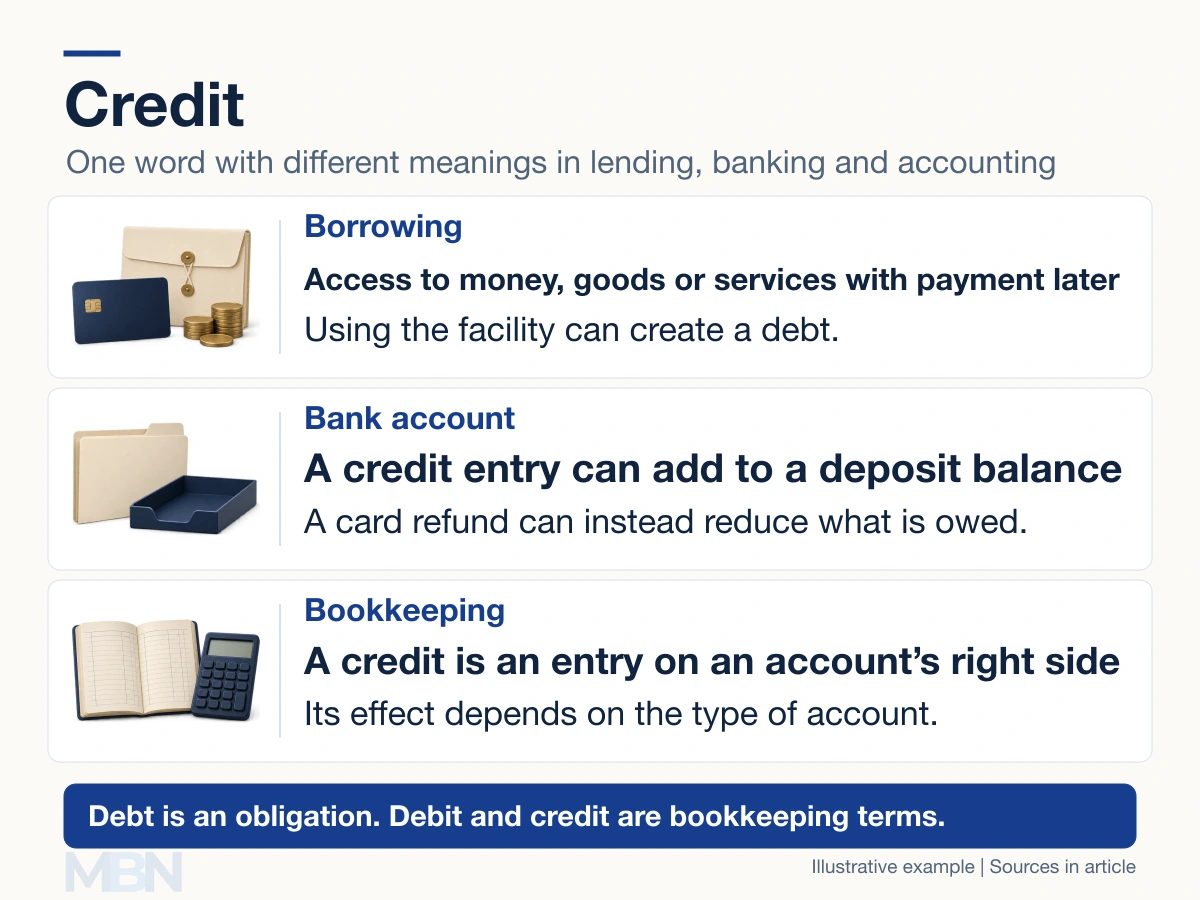
Credit commonly means an arrangement allowing someone to obtain money, goods or services now and pay later. It also has specific meanings in bank statements and bookkeeping. Those meanings are related, but they are not interchangeable.
A lender or supplier extending credit is a creditor. The borrower or customer owing payment is a debtor. Debt is the obligation created when credit is used, rather than the opposite of credit.
What forms can borrowing take?
An installment loan provides an amount repaid under an agreed schedule. A revolving facility allows repeated borrowing and repayment within a limit, subject to the agreement. A supplier can also extend trade credit by allowing a business customer to pay an invoice later.
The FDIC distinguishes installment and revolving loans, which can be secured or unsecured. Secured credit is backed by specified collateral. Unsecured credit does not have that particular asset security, but the obligation to repay remains.
Borrowing terms can include interest, fees, repayment dates and conditions for default. A period without interest does not necessarily remove all costs or conditions.
How do credit limit and available credit differ?
A credit limit is the permitted borrowing ceiling under a facility. Available credit is the portion currently usable. With a $4,000 limit and a $1,800 balance, a simple calculation gives $2,200 available.
That calculation assumes no pending holds, unposted charges or other restrictions. Chase explains that pending transactions and payment processing can affect available credit. Available credit is borrowing capacity, rather than cash savings or income.
A limit is not guaranteed to rise with good payment behavior. The CFPB explains that card issuers can generally increase or reduce limits, subject to applicable protections and terms.
What does a bank-account credit mean?
A credit to a deposit account normally increases its balance, for example when a payment is received. The bank records deposits as amounts it owes its customer, so its perspective differs from the customer’s own bookkeeping.
A credit on a credit-card account can instead reduce the balance owed, as with a refund. If credits exceed the amount due, a card can show a credit balance. The account type matters when interpreting the entry.
What is a credit in accounting?
In double-entry bookkeeping, a debit is an entry on the left side of an account and a credit is an entry on the right. Debits and credits do not universally mean money out and money in.
Suppose a business receives a $1,000 loan into its bank account with no fees. It debits cash by $1,000 to increase the asset and credits loan payable by $1,000 to increase the liability. ICAN’s accounting study text illustrates this paired recognition of cash and a loan liability.
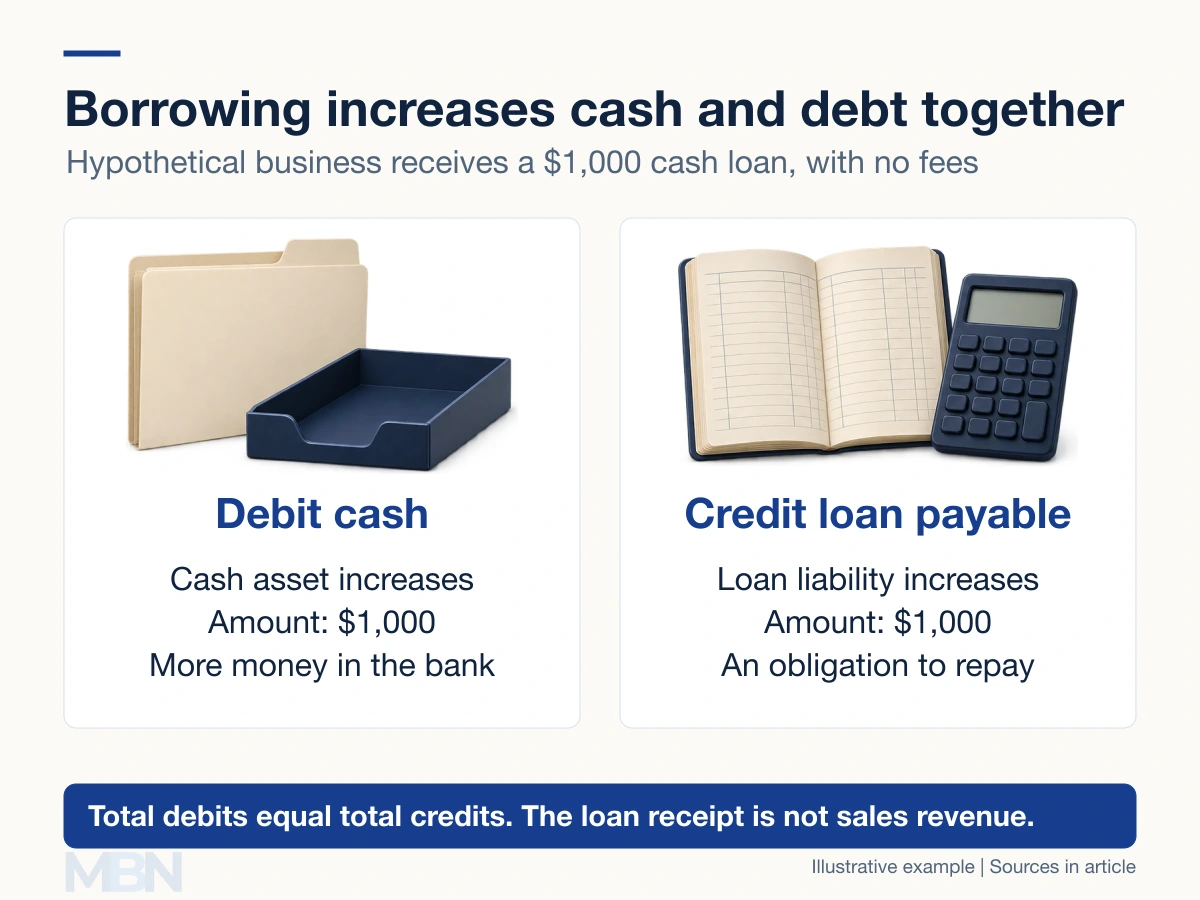
The transaction increases both assets and liabilities; it does not create sales revenue or profit. Later interest expense and repayment need their own entries. Total debits and credits across each recorded transaction must balance.
How is access to credit assessed?
Lenders can consider repayment history, income, existing obligations, collateral and the proposed terms. A credit score is one input, rather than a complete measure of affordability or a guarantee of approval.
Rules vary by country. In the United States, lenders generally cannot base decisions on age alone or reject qualifying income merely because of its source. The relevant legal exceptions and loan criteria matter. Broad claims that age or homeownership always determines a credit limit are misleading.
Last checked and updated on November 10, 2026 by the MBN editorial team.