
A creditor is a person, business or other entity owed money. The party that owes the money is the debtor. The debt can arise from a loan, goods or services supplied, unpaid wages, taxes or another obligation.
A bank lending money is a creditor, but not every creditor is a lender. An employee owed earned wages or a supplier waiting for payment has not necessarily lent cash.
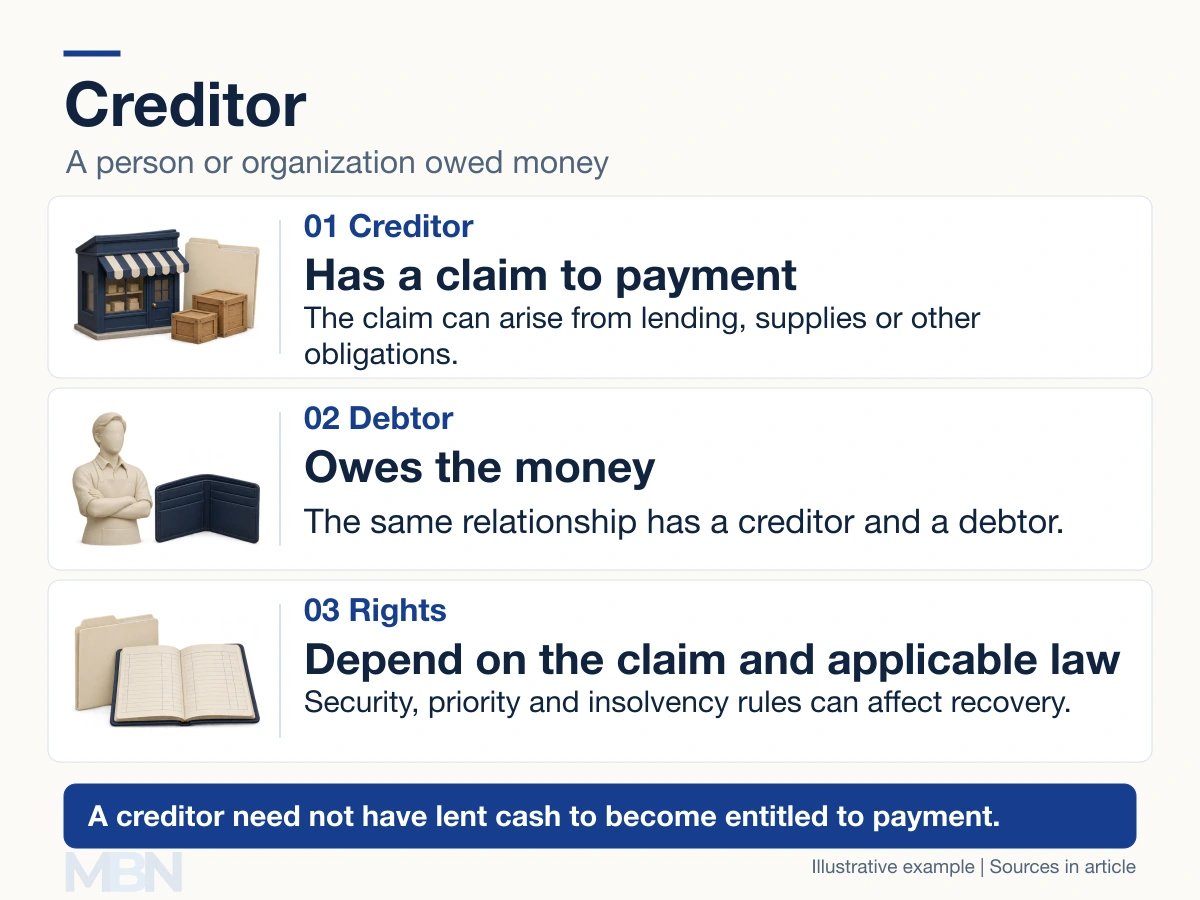
A supplier and customer example
Suppose a hypothetical supplier delivers $2,000 of stock to a retailer on 30-day credit. Until payment, the supplier is the creditor and the retailer is the debtor. The supplier records a trade receivable; the retailer records a trade payable.
When the retailer pays the full amount, the invoice is settled. A debtor can have many creditors at once, with different due dates, terms and rights.
The US Courts bankruptcy glossary defines creditors and claims in the context of US bankruptcy proceedings. A disputed claim still requires assessment; a demand for payment does not by itself prove that the amount is valid.
Secured creditors
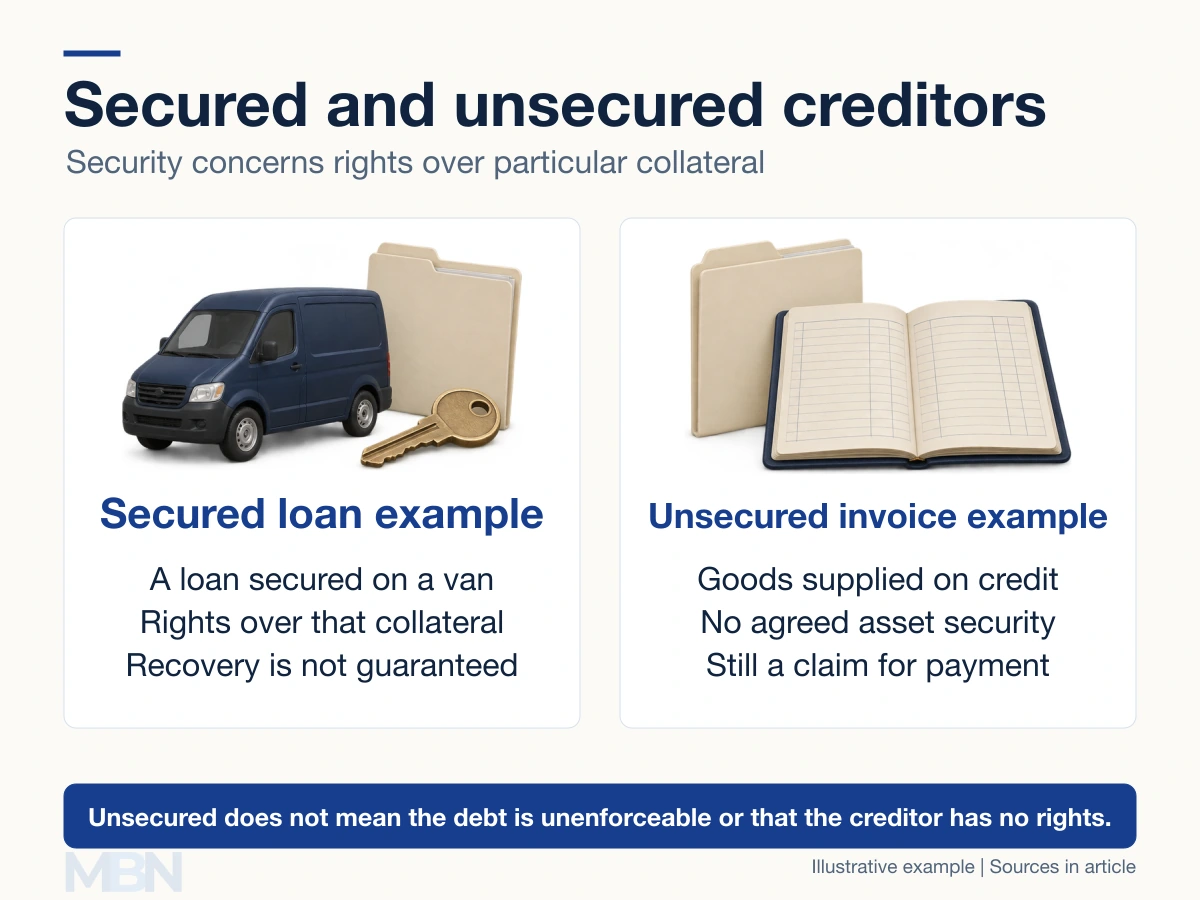
A secured creditor has a security interest in specified property supporting the debt. For example, a lender may hold security over a financed delivery van. The precise enforcement rights depend on the security, its validity and priority, and applicable law.
Collateral does not guarantee full repayment. Its value may fall, enforcement can involve costs, and other claims or legal restrictions can affect what is recovered.
Unsecured creditors
An unsecured creditor lacks the special collateral rights attached to a secured claim. An ordinary supplier invoice without security is an example. It is wrong to say unsecured creditors have no legal recourse to a debtor’s assets.
They may be able to sue, enforce a judgment or claim a distribution in an insolvency process, subject to the relevant rules. The US Courts distinguishes unsecured claims from rights against particular collateral.
What happens in insolvency?
Creditor claims can rank differently. Security, statutory priorities, the assets available and the type of procedure affect payments. Some unsecured claims can have priority over other unsecured claims.
Insolvency proceedings can also restrict individual collection action. For example, Australia’s ASIC explains the position in company liquidation. Shareholders generally receive a residual distribution only after creditor claims and relevant costs have been addressed. Full recovery is not assured.
Creditors in a company’s accounts
Amounts owed are classified according to their nature. Supplier trade balances normally appear in accounts payable; loans, taxes and wages may appear in separate liability categories. The absence of a promissory note does not turn every obligation into accounts payable.
A debt collector is also a different role. It may collect for a creditor or own a debt it purchased, depending on the arrangement. The CFPB explains debt collection in the US consumer context.
Last checked and updated on November 10, 2026 by the MBN editorial team.