
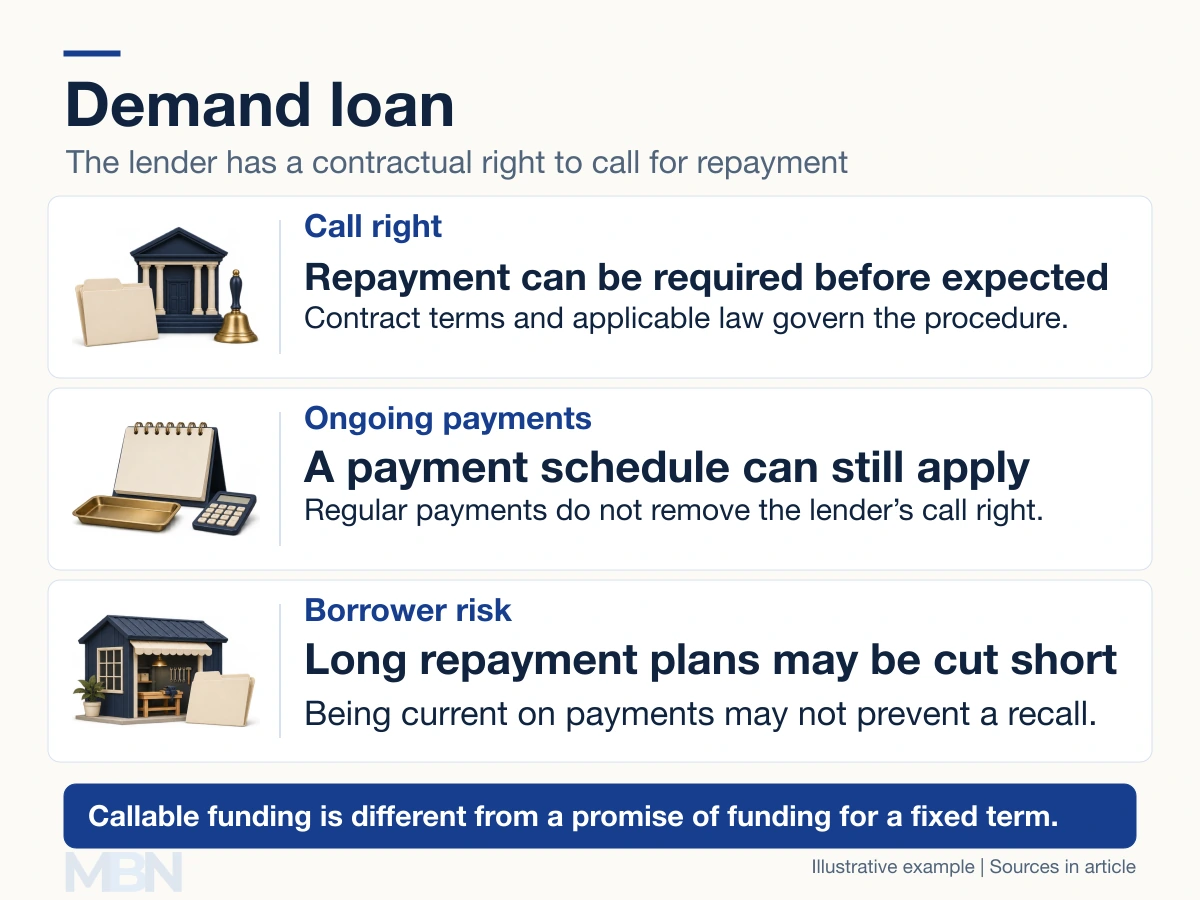
A demand loan gives the lender a contractual right to require repayment of the outstanding balance rather than wait for a fixed final repayment date. Exercising that right is often called calling in or recalling the loan.
The repayment procedure, any required notice and the borrower’s protections depend on the agreement and applicable law. The term does not mean every lender can seize assets instantly or disregard legal requirements.
How does a demand loan work?
The borrower receives money or draws on an agreed facility. Interest and other terms are specified in the contract. The loan may require regular interest payments, principal repayments or both, while preserving the lender’s right to demand the remaining balance.
A scheduled repayment plan therefore does not necessarily guarantee that the funding will remain available for that whole period. Canada’s development bank BDC explains that a demand loan can be recalled even when the borrower is meeting the agreement’s terms.
Can it have a maturity date or installments?
A pure demand note may state no fixed payment date. However, a document can combine payment dates with an earlier demand right. In the US, Uniform Commercial Code section 3-108(c) expressly recognizes instruments payable on a fixed date that are also payable on demand before that date. State law and the particular instrument determine the legal result.
It is therefore inaccurate to say that every demand loan has no payment schedule or cannot mention a maturity date. Maturity is the date a debt falls due; amortization describes the process of reducing principal through repayments. They are different features of a loan.
An example of a repayment demand
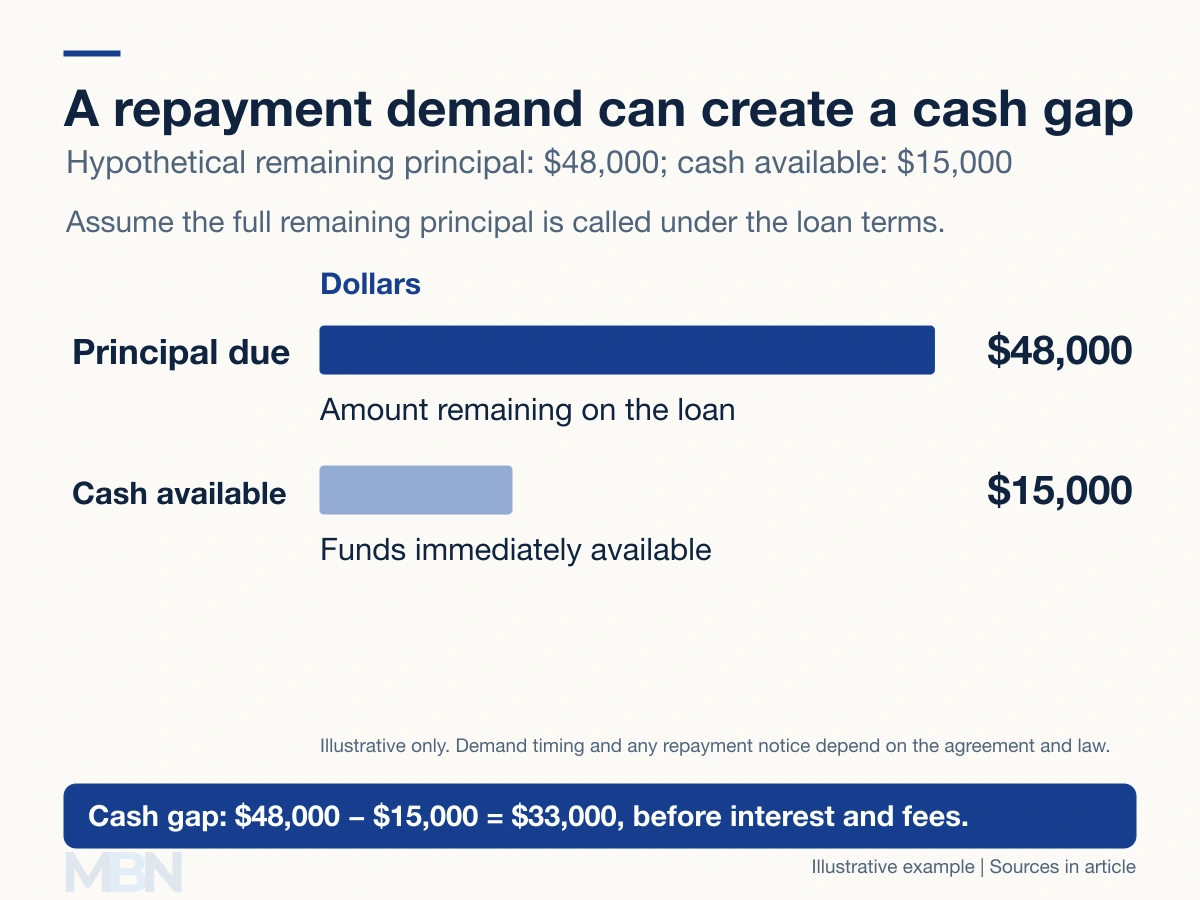
Suppose a business borrows $60,000 and has repaid $12,000 of principal. It has $48,000 principal left. If its lender makes a valid demand for that balance, the business must meet the applicable repayment requirement, including any interest or fees due.
If only $15,000 cash is immediately available, the principal alone creates a $33,000 cash gap. Equipment or inventory may have value without being readily convertible into cash. New finance may also be difficult to arrange when lenders are cautious.
Demand loans and committed term loans
A committed term loan is generally available for the agreed term while its conditions are met. It can still contain acceleration clauses that make debt due early after specified events, such as a payment default. That is different from a broad demand right that need not depend on a missed payment.
Neither an established relationship with a lender nor a profitable business removes a contractual call right. BDC notes that recalls can reflect the lender’s portfolio decisions as well as concerns about a particular borrower.
Security, rates and related terms
A demand loan can be secured or unsecured. Collateral supports repayment if the borrower defaults, but does not by itself make the loan committed for a fixed term. The rate and any early-repayment charges must be established from the contract rather than inferred from the word demand.
A demand note is a written promise documenting a payable-on-demand obligation. Call loans are related terminology. Brokerage and securities-backed credit can have demand features, as illustrated by Merrill’s margin lending agreement, but broker loan is not an interchangeable label for every demand loan.
CIBC’s lending glossary distinguishes demand, installment and interest-only arrangements. These describe different aspects of borrowing, so more than one can apply to the same facility.
Last checked and updated on November 10, 2026 by the MBN editorial team.