
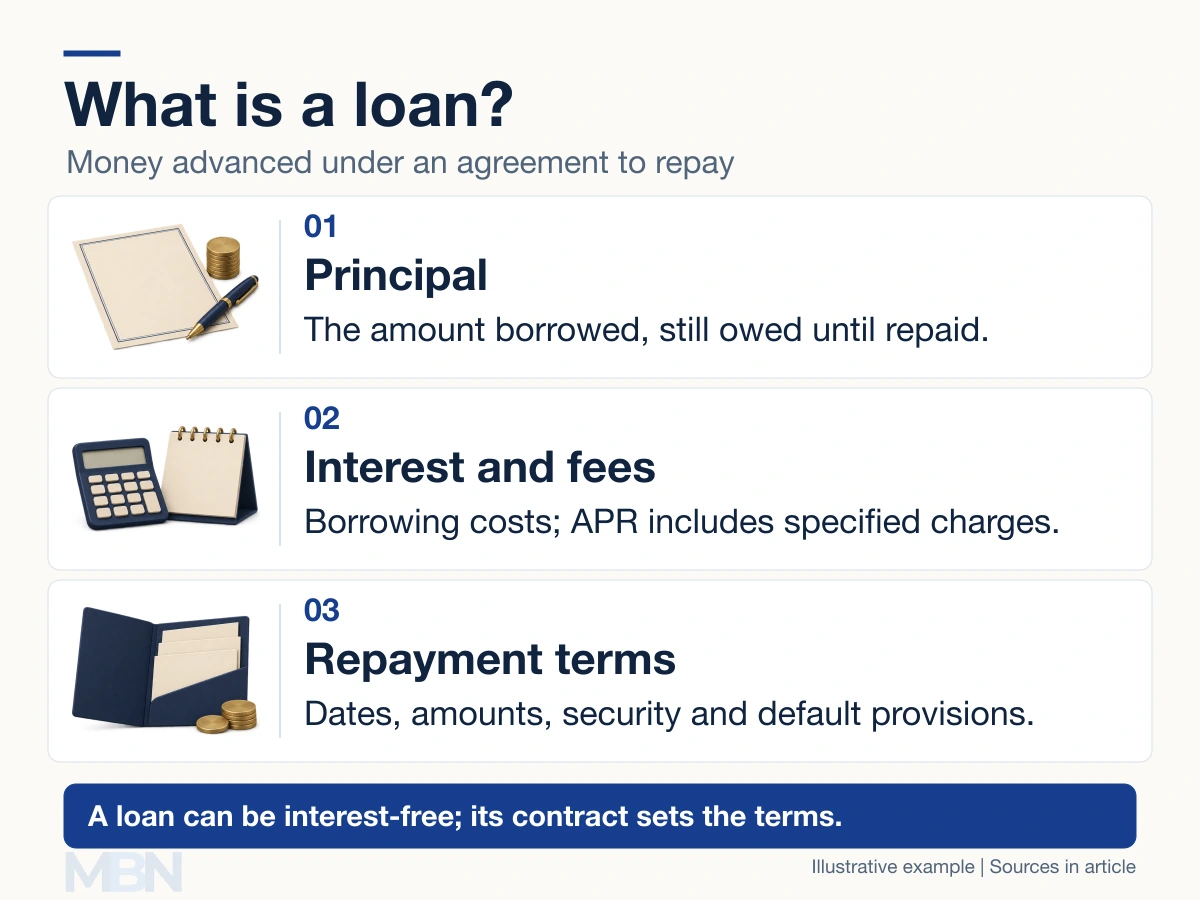
A loan is money advanced by a lender to a borrower under an agreement to repay it. The borrower usually pays interest and may pay fees, although some loans are interest-free.
The amount borrowed is the principal. A loan agreement sets repayment dates, borrowing costs and what happens if the borrower fails to pay. Banks, credit unions, businesses, governments and individuals can all lend money. A loan is a form of credit.
Interest rate and APR
The interest rate determines the interest charged on a loan balance. The annual percentage rate (APR) expresses the cost of credit on an annualized basis and includes specified fees as well as interest. The Consumer Financial Protection Bureau explains the difference for US loans; the charges included and calculation rules depend on the product and jurisdiction.
A fee deducted from the advance can leave the borrower receiving less cash than the principal they must repay. APR is not simply the annual interest payment divided by the original loan amount, and it should not automatically replace the contract rate in a payment formula.
Loan types describe different features
An installment loan is repaid through scheduled payments. A revolving facility allows borrowing and repayment within a credit limit, subject to its terms. The FDIC’s explanation of loans notes that either arrangement can be secured or unsecured.
A secured loan gives the lender rights over specified collateral, such as a home or vehicle. Enforcement depends on the agreement and applicable legal process. An unsecured loan has no such pledged collateral, but the lender may still pursue lawful collection or a court judgment.
A demand loan is repayable when the lender makes a valid demand under its terms. Demand status does not require a floating interest rate. Fixed and variable rates are another separate way to classify loans.
Subsidized loans receive help with costs. For example, US Direct Subsidized Loans have government-paid interest during specified eligible periods, including enrollment at least half-time. “Soft” or concessional loans offer favorable terms compared with conventional financing. The World Bank’s International Development Association provides concessional credits as well as grants.
A guarantee gives the lender an additional claim against a guarantor if the specified conditions are met. It does not cancel the borrower’s repayment obligation. Security, a guarantee and a subsidy can appear in the same transaction.
A fixed monthly payment example
For a fully amortizing fixed-rate loan with equal end-of-month payments, the formula is M = L × r ÷ [1 − (1 + r)^(-n)]. M is the monthly payment, L the principal, r the monthly interest rate expressed as a decimal, and n the number of payments. The ^ symbol means “raised to the power of.”
Suppose a hypothetical borrower receives $10,000 at a 6% nominal annual interest rate, divided into a 0.5% monthly rate, over 12 months with no fees. The calculated payment is about $860.66 a month. Before payment rounding, total repayments are about $10,327.97, including $327.97 interest.
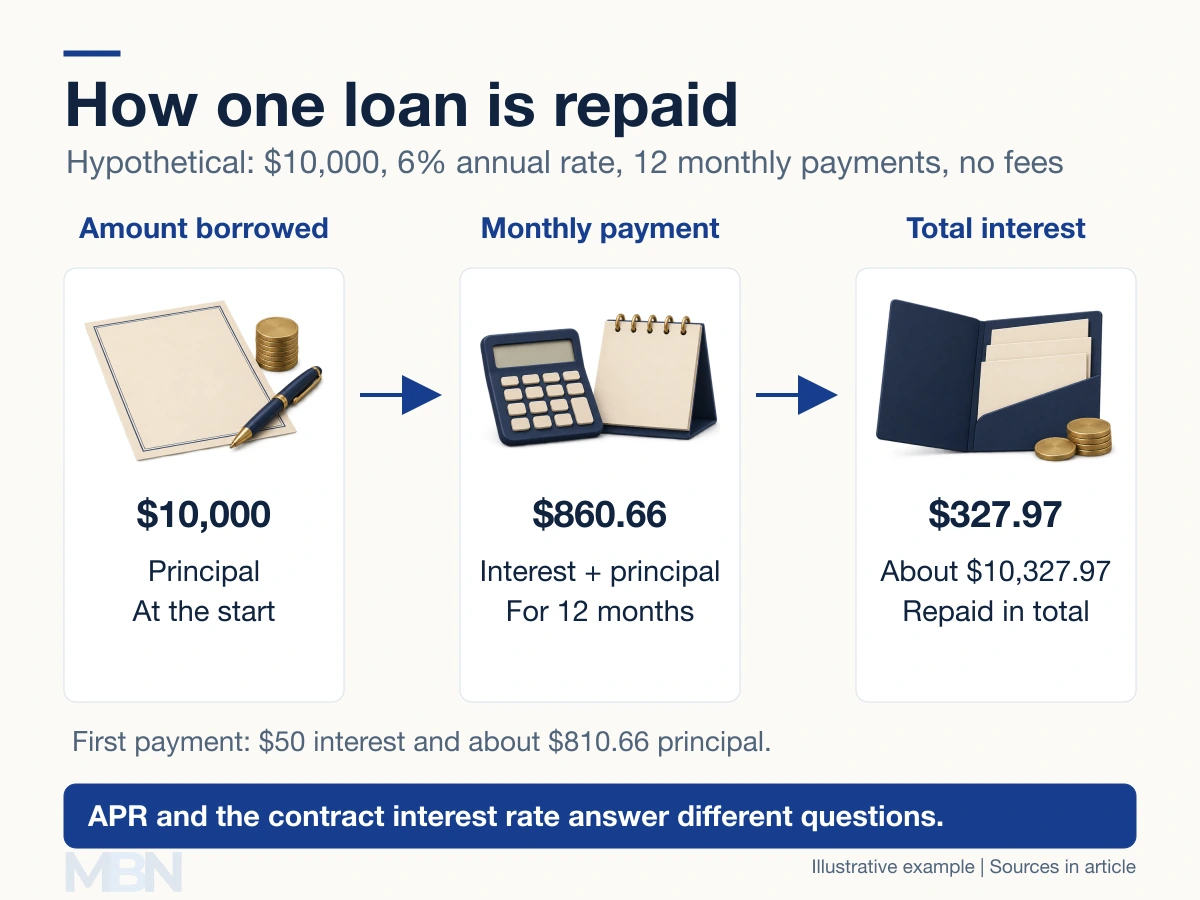
The first month’s interest is $10,000 × 0.005 = $50. About $810.66 of the first payment reduces principal. Later interest charges decline as the balance falls. The CFPB describes this repayment process as amortization. At a zero interest rate with no fees, equal payments would simply be L ÷ n.
What the agreement establishes
Loan documents specify matters such as the rate, fees, term, payment timing, permitted use and any early-repayment or default provisions. Not every loan has equal installments: some have interest-only periods or a large final payment.
Lenders assess repayment capacity and credit risk using information appropriate to the product. Credit records, income, existing obligations, collateral and business cash flow may be relevant. The “Cs of credit” are a teaching framework, not one mandatory formula used by every lender.
Last checked and updated on November 5, 2026 by the MBN editorial team.