
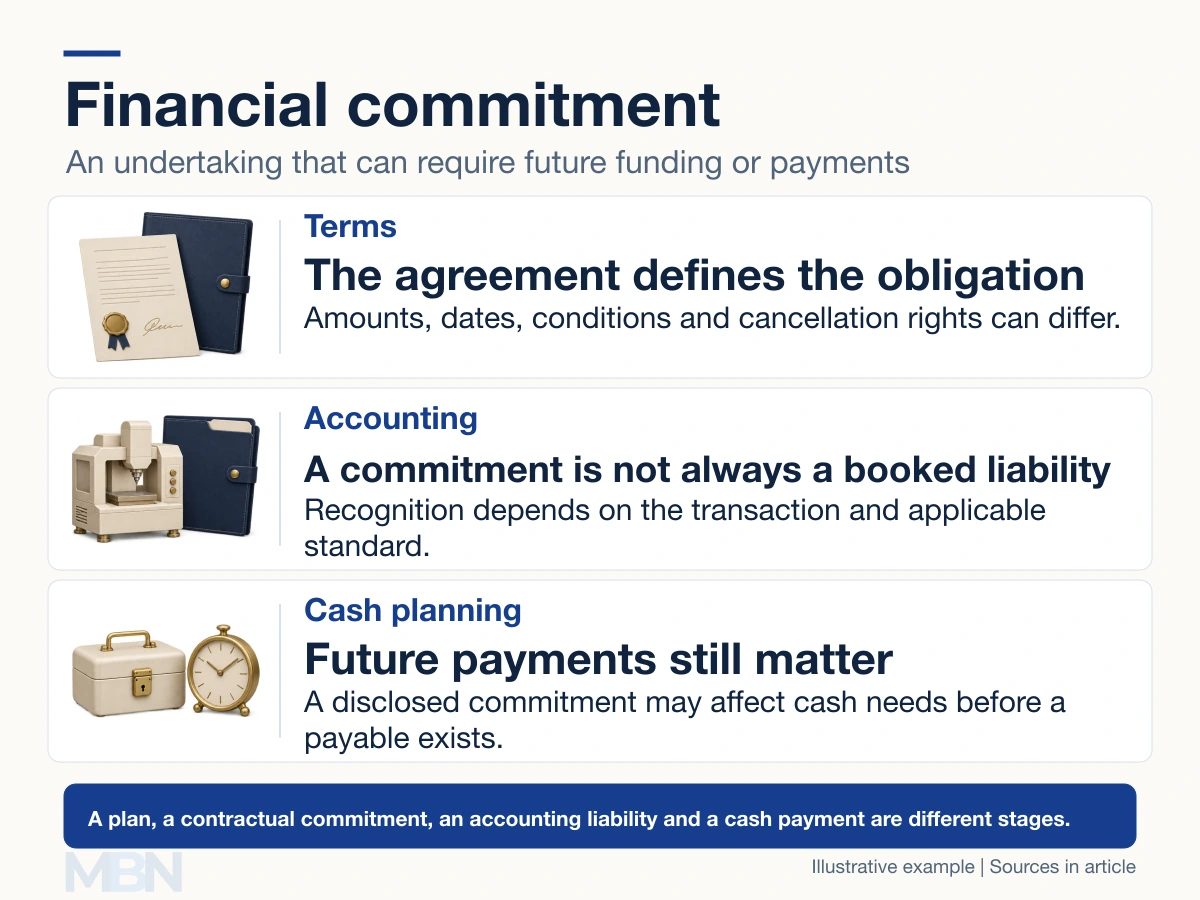
A financial commitment is an undertaking that can require future funding or payments. It may be a contract to buy equipment, an agreement to repay a loan, a promise to contribute capital or another responsibility involving money. Its amount, timing and conditions determine what has actually been committed.
The term also has an everyday meaning, such as supporting a family. That broad use does not establish that an accounting liability exists or that a promise is legally enforceable.
What the agreement commits someone to do
A supplier agreement may require payment when goods are delivered or after a stated credit period. A cancellation clause, condition precedent or variable price can change the amount and timing. A purchase order should not automatically be treated as an unconditional, enforceable debt without examining its terms.
A loan facility can commit a lender to make funds available subject to conditions. The borrower’s obligation to repay funds already drawn differs from an unused borrowing limit. Undrawn facilities may still involve fees or other obligations.
Does every commitment create a liability?
No. A normal purchase contract under which neither party has performed, often called an executory contract, does not automatically produce a payable. Recognition depends on the relevant accounting rules and facts.
Under IAS 37, a provision is a liability of uncertain timing or amount. Recognition requires a present obligation from a past event, a probable outflow of resources and a reliable estimate. Future operating plans alone are insufficient.
An onerous contract, where unavoidable costs exceed expected benefits, can require a provision. Specific standards govern other transactions, including financial instruments under IFRS 9. An unused loan commitment therefore needs its own assessment, rather than a blanket rule.
A purchase example
Suppose a business agrees to buy a $20,000 machine. There is no deposit, neither party has performed, and the contract is not onerous. The contract creates a future purchase commitment but does not automatically create a $20,000 payable at signing.
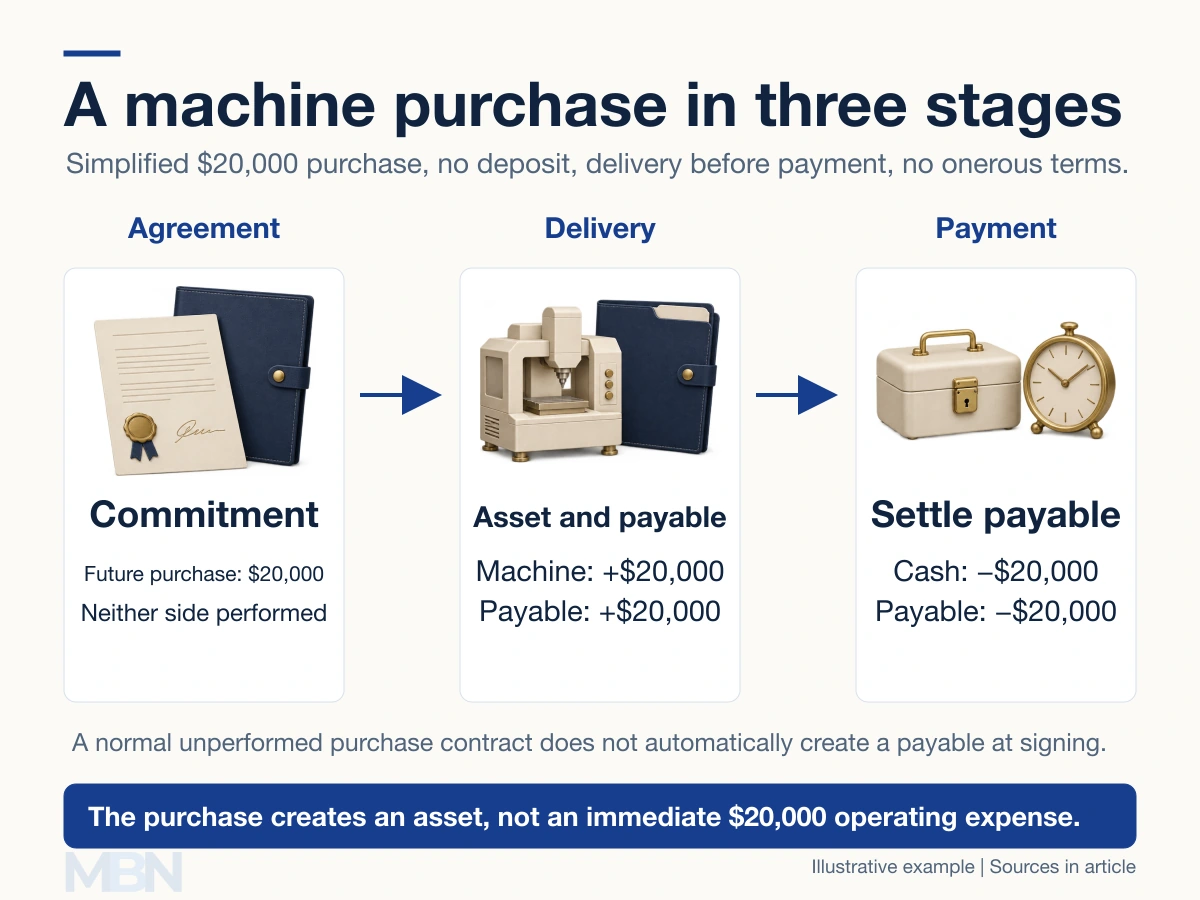
When delivery and the asset-recognition conditions are met, the simplified entry records a $20,000 machine asset and a $20,000 payable. When payment occurs, cash and the payable each fall by $20,000. Depreciation and other later expenses are separate questions.
Disclosure can still be required before delivery. IAS 16 includes disclosure of contractual commitments to acquire property, plant and equipment. An amount absent from the balance sheet is not necessarily absent from the financial-statement notes.
Why commitments matter for cash planning
Future payments can limit funds available for other uses even before they become current payables. A cash forecast therefore includes payment schedules, conditions and cancellation costs, rather than relying only on today’s bank balance or recognized debt.
The CFPB’s cash-flow-budget explanation illustrates why timing matters for households too. A monthly total can look affordable while particular weeks remain short of cash. A commitment’s financial consequences depend on when payments fall due and what resources are available then.
Last checked and updated on November 11, 2026 by the MBN editorial team.