
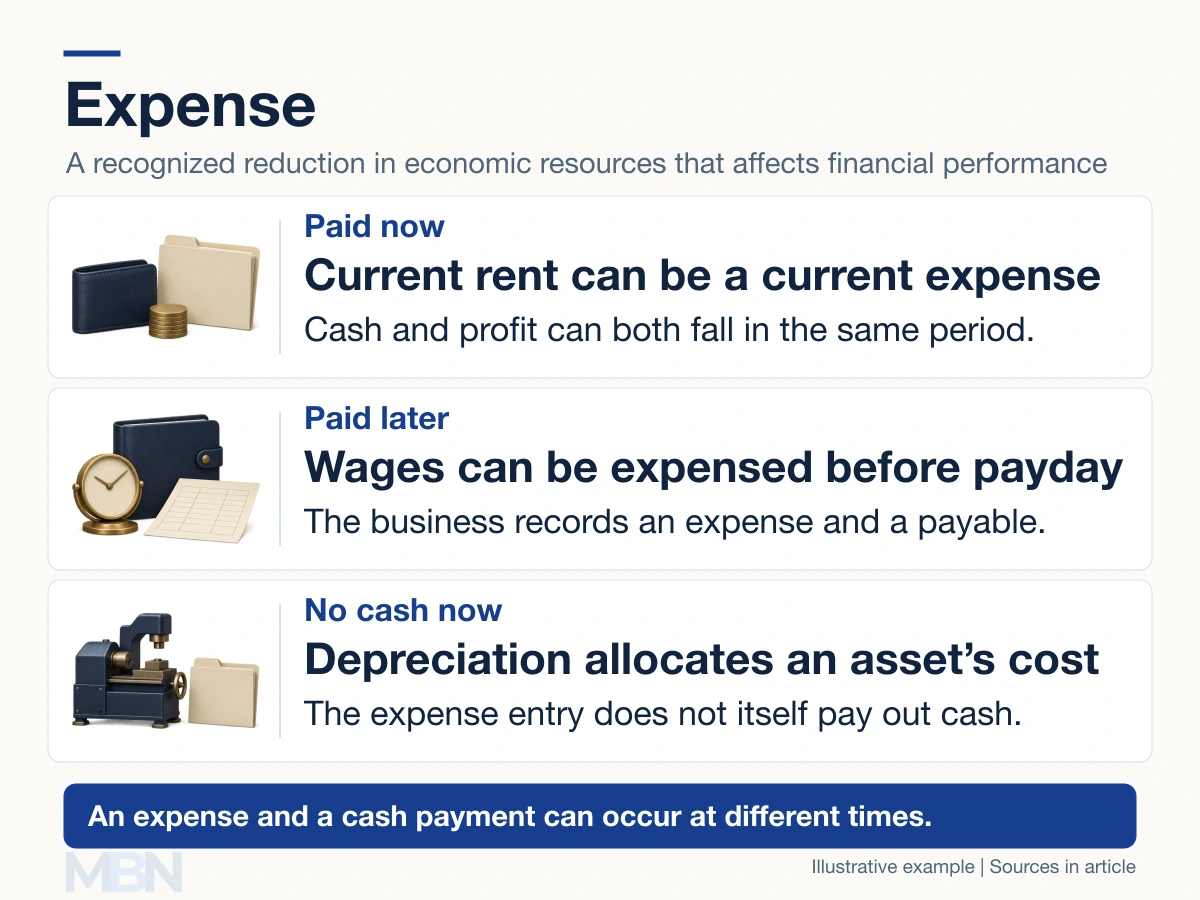
In accounting, an expense is a recognized cost or other reduction in economic resources that reduces financial performance for a period. It can arise when an asset is used up or loses value, or when a liability is incurred. It does not always involve a cash payment at the same time.
The IFRS Conceptual Framework defines expenses through decreases in assets or increases in liabilities that reduce equity, excluding distributions to owners. Paying a dividend is therefore different from incurring a business expense.
Expenses and cash payments
Under accrual accounting, the relevant recognition rules determine when a cost becomes an expense. Paying $600 for the current month’s office rent can produce both a cash payment and a $600 rent expense in that month.
Wages earned by employees this month but paid next month create a current expense and a payable. Paying the payable later reduces cash and the liability; it does not create a second expense for the same work.
Depreciation is a different pattern. It recognizes the allocation of a long-lived asset’s cost without a new cash payment for that entry. OpenStax explains accrued expenses, prepayments and depreciation through adjusting entries.
In double-entry bookkeeping, a simple expense entry normally debits an expense account and credits an asset or liability account. An expense need not both reduce assets and increase liabilities in the same entry.
Expenditure can create an asset first
Expenditure describes spending or an obligation incurred to obtain something. Depending on what is acquired and the accounting rules, it can be recognized as an expense immediately or recorded as an asset and expensed later.
Suppose a machine qualifies for capitalization at $12,000 and is bought for cash. The initial entry reduces cash and records equipment. Assuming a five-year useful life, zero residual value and straight-line depreciation, a full year’s depreciation is $2,400.
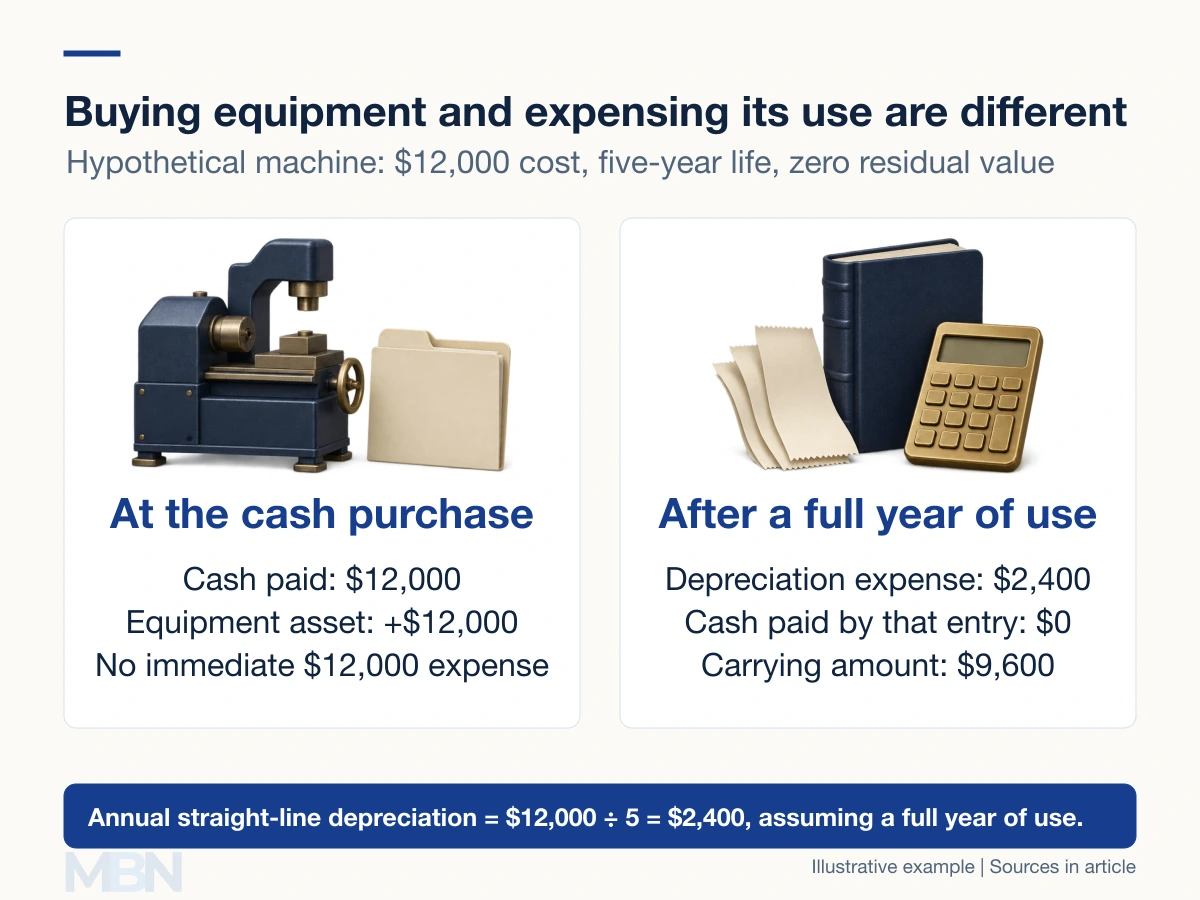
After that full year, accumulated depreciation is $2,400 and the machine’s carrying amount is $9,600, assuming no impairment or other adjustment. OpenStax explains why capitalization and depreciation separate acquisition cost from period expense.
Inventory provides another example. Goods held for sale are normally an asset until sold, when their assigned cost becomes cost of goods sold. A prepaid insurance premium becomes an expense as the coverage is consumed. Paying loan principal generally reduces a liability, while interest is accounted for separately.
Types of expenses
Cost of goods sold relates to the goods a business sells. Other operating expenses can include administration, selling costs, rent and relevant depreciation. The presentation may group expenses by their nature, such as wages, or by function, such as distribution.
Financing costs and income tax expenses are often presented separately. Their classification depends on the business and reporting framework. Amortization is not automatically non-operating: amortization of a software license used in ordinary operations can be part of operating costs.
An airline’s expenses can include fuel consumed, crew wages, airport charges, maintenance and depreciation. Buying an aircraft that qualifies as a long-lived asset is generally capitalized rather than immediately expensed in full. Ticket sales are revenue, not a cost merely because tickets were sold.
The cash-flow statement uses different categories
A cash-flow statement groups cash movements into operating, investing and financing activities. It is not simply a list of expenses. Cash purchases of equipment are generally investing outflows, and loan-principal repayments are generally financing outflows.
Interest-payment classification depends on the applicable accounting rules. OpenStax compares US GAAP and IFRS cash-flow classifications. Noncash depreciation does not appear as a cash payment; an indirect operating-cash reconciliation adjusts for it.
Expense reports and tax deductions
An employee expense report records business-related costs for review, accounting and possible reimbursement. Dates, amounts, business purpose, receipts and approval help identify what was incurred. Reimbursement depends on the employer’s policy and the applicable rules, not the report’s existence alone.
An accounting expense is not automatically tax deductible. In the United States, the IRS describes the ordinary-and-necessary test for business deductions, alongside restrictions and capitalization rules. Other jurisdictions apply their own requirements; travel and meals do not all qualify without limits.
As a verb, to expense an item means to recognize it as an expense. In everyday workplace speech, it can also mean submitting a cost for reimbursement. The accounting entry, reimbursement approval and tax treatment remain separate questions.
Last checked and updated on November 11, 2026 by the MBN editorial team.