
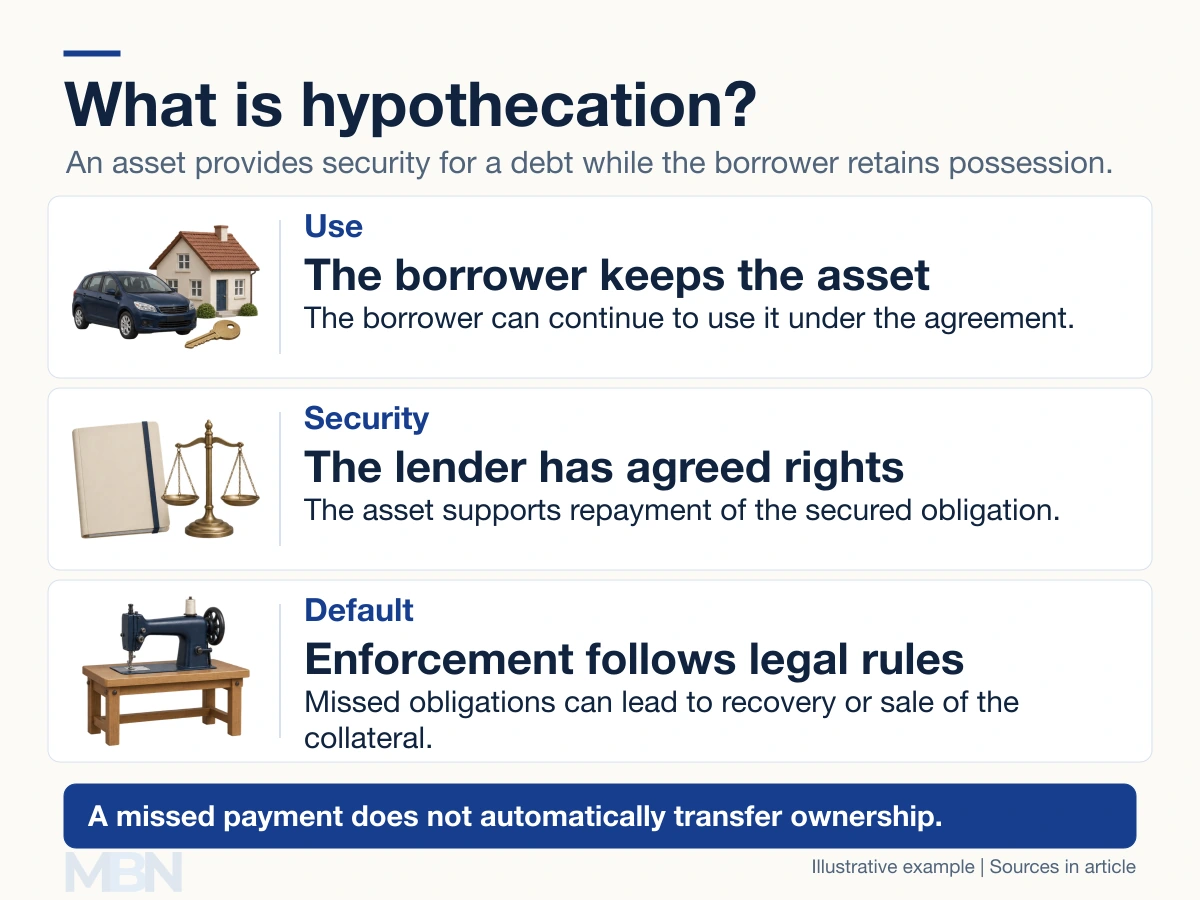
Hypothecation means providing an asset as security for a debt while retaining possession of it. The lender obtains rights over the asset under the agreement and applicable law, while the borrower can normally continue using it.
A financed car or business machine can illustrate the idea: it supports repayment, but remains in the borrower’s use. Cambridge Dictionary describes the financial term in relation to assets pledged as security.
What does the lender receive?
The lender receives security rights, rather than simply becoming the asset’s owner. The asset is called collateral because it can provide a source of recovery if the secured debt is not paid.
The legal arrangement might be described as a mortgage, charge, lien, security interest or hypothec, depending on the country and transaction. These terms are related, but they are not interchangeable in every legal system. A lien is not universally limited to immovable property.
A borrower keeping possession also does not mean having unrestricted freedom to sell or further pledge the asset. The agreement and applicable law determine what the borrower may do.
What happens if the borrower defaults?
Default means failing to meet an obligation under the loan terms. It does not automatically turn the asset into the lender’s property. Repossession, foreclosure or sale can involve notices, waiting periods, court procedures or other legal conditions.
For a US example, Uniform Commercial Code section 9-610 provides for a secured party’s disposal of collateral after default and requires commercial reasonableness. It is a model provision adopted through state law, not a universal rule for every mortgage or country.
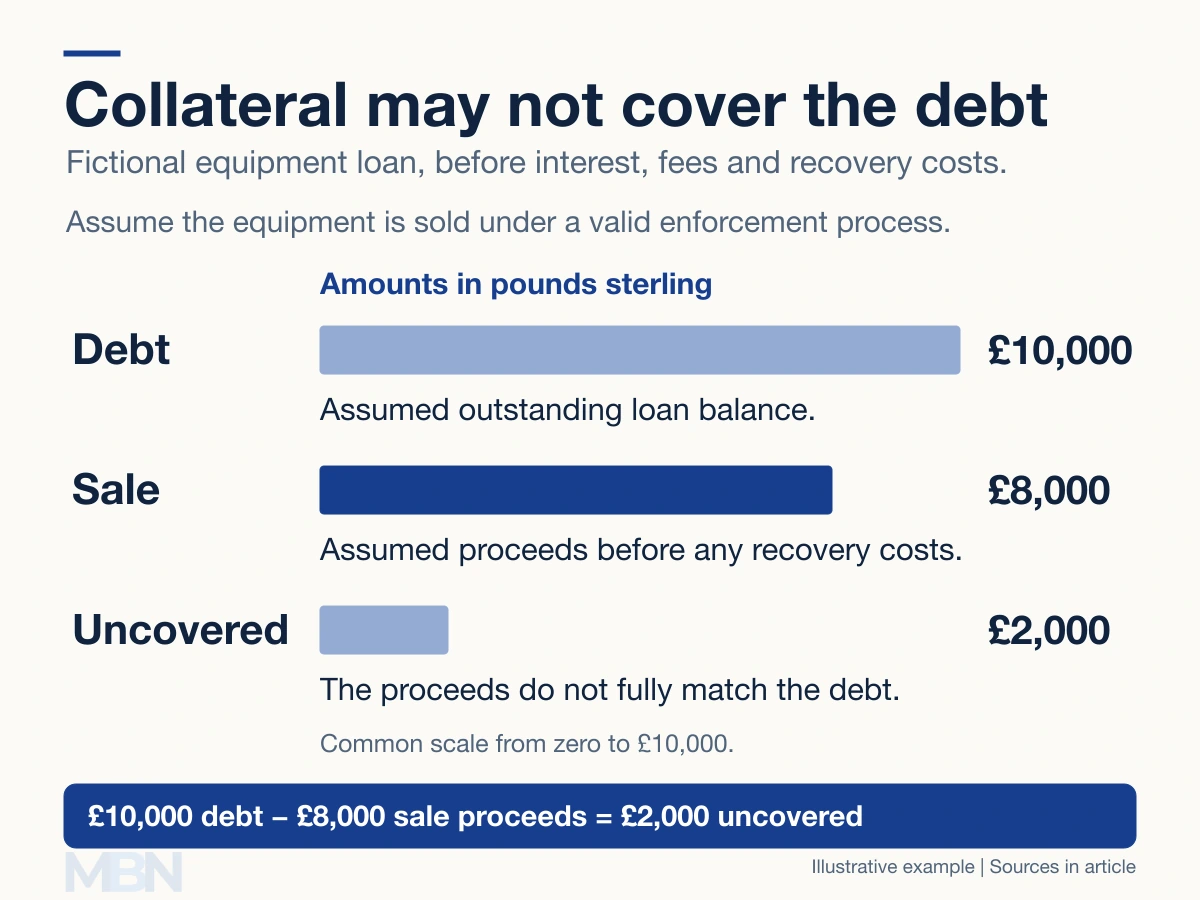
Collateral can also be worth less than the debt. Suppose a fictional business owes £10,000 secured on a machine, and a valid enforcement sale raises £8,000 before costs. There is a £2,000 gap between the debt and proceeds. Any further recovery, or entitlement to a surplus in a different case, depends on the governing rules.
Can one asset secure more than one debt?
It can in some arrangements, but the priority of competing claims matters. Priority is the order in which creditors’ rights rank. It is not safe to assume that the first loan agreement always wins.
For example, UCC section 9-322 considers filing and perfection in its general priority rules, with exceptions elsewhere in the code. Perfection means taking the legally required steps to protect a security interest against certain competing claims. Other jurisdictions have their own systems.
How is hypothecation used in investing?
In a margin account, a broker lends money and securities support the loan. If their value falls, the investor’s equity, meaning the value remaining after the debt, also falls.
FINRA margin disclosure rules explain that a firm may sell securities to protect its loan and can do so without first contacting the customer. A margin call should therefore not be described as guaranteeing a fixed period before a sale.
What is rehypothecation?
Rehypothecation is a receiving party’s reuse of collateral in another transaction, such as securing its own borrowing. It depends on the arrangement and the relevant legal and regulatory limits.
Bank of England research explains how collateral reuse can support funding but also link institutions’ exposures. It is a separate issue from the original borrower merely continuing to use a financed asset.
What does hypothecation mean in taxation?
Tax hypothecation has a different meaning: earmarking revenue for a specified purpose. A hypothetical levy reserved for maintaining roads is an example. No borrower is pledging a car or building in that usage.
The House of Commons Library uses the term for assigning tax receipts to particular ends. How binding or flexible such an arrangement is depends on its design; earmarking alone does not guarantee a particular level of service.
Last checked and updated on November 2, 2026 by the MBN editorial team.