
Payroll is the process of calculating employees’ earnings, making required deductions, paying employees and recording and reporting those amounts. The word can also mean the employee-pay records, the total wage bill or the team responsible for this work.
A payroll run connects information about work and pay with accounting, payments and legal obligations. A business using only genuine independent contractors may have supplier payments without an employee payroll; worker status depends on the applicable rules, rather than a label alone.
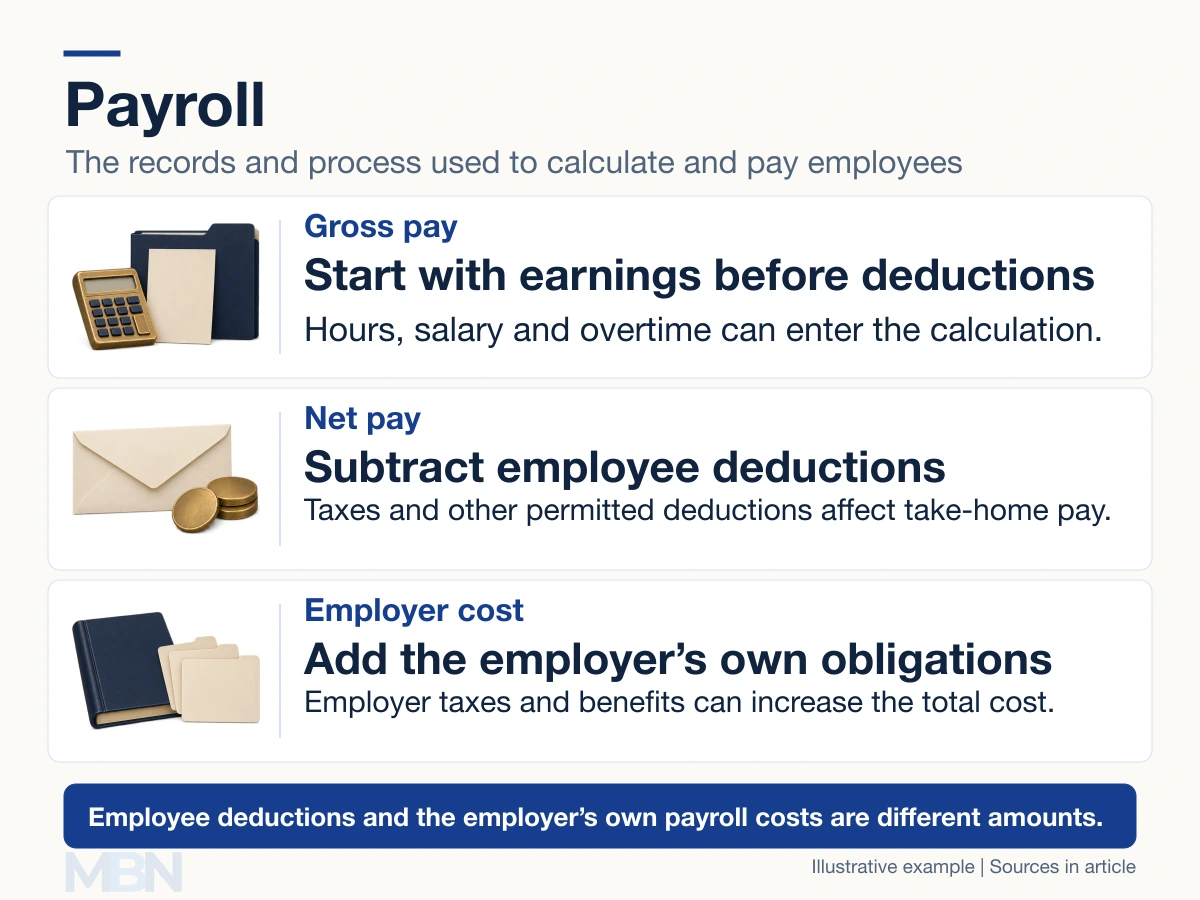
How a payroll run works
The calculation starts with the pay period and relevant information, such as salary, hours worked, overtime, commissions, leave and adjustments. Gross pay is the employee’s earnings before deductions.
Employee deductions can include tax withholding, social-insurance contributions, pension or benefit contributions and other deductions allowed or required by law. Net pay is what remains to be paid to the employee after the relevant deductions and adjustments.
The employer also records its own taxes or contributions, sends payments to employees and other recipients, and makes required reports. A payslip, bank transfer and tax filing are related outputs, rather than the same task.
The US Department of Labor describes wage-and-hour records required for covered employees, including hours, earnings, deductions and payment dates. Requirements vary by jurisdiction and worker category.
Why employer cost differs from take-home pay
Suppose a worker earns $3,000 in a pay period. With illustrative employee deductions of $600, net pay is $2,400. If the employer has another $300 of taxes or contributions, its total cost is $3,300.
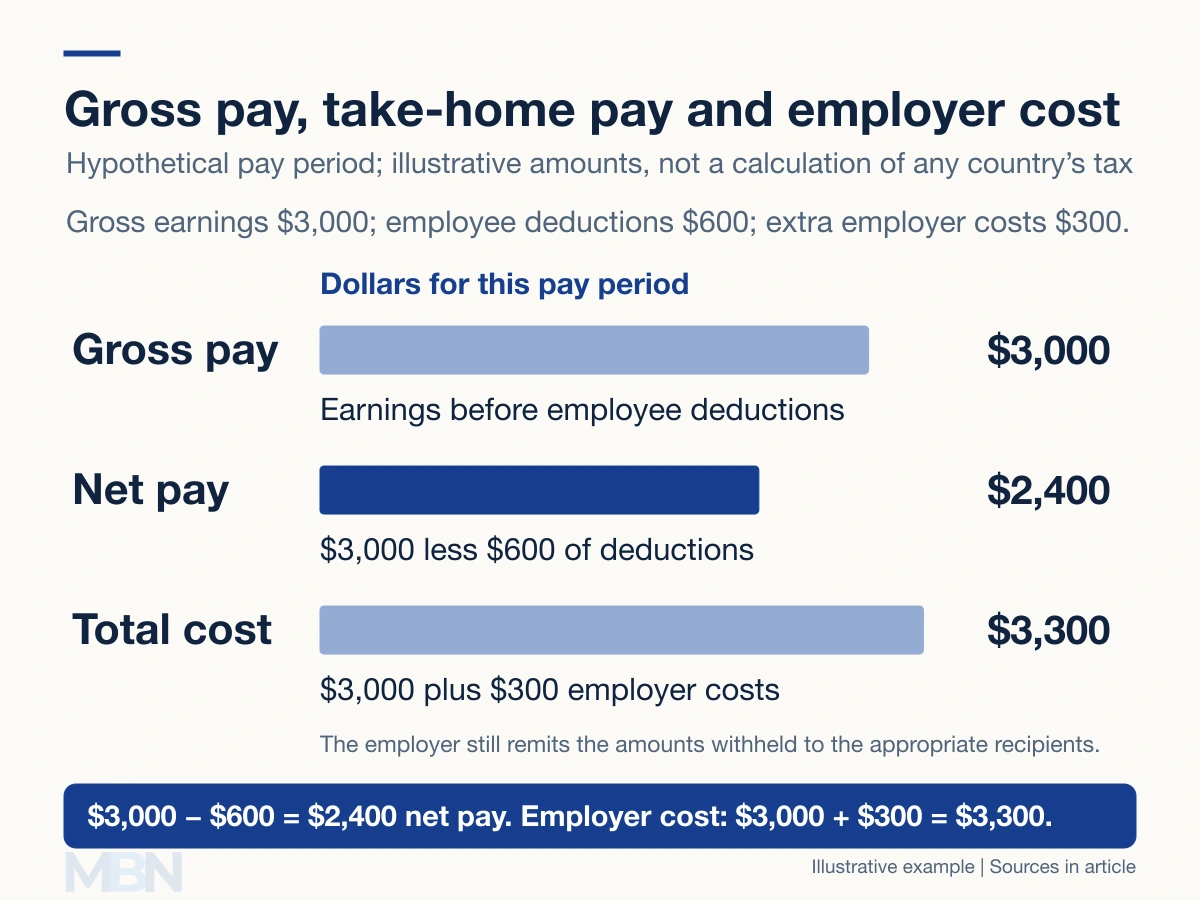
The $600 withheld is not an extra wage expense on top of the $3,000. It is part of gross earnings directed to tax authorities or other recipients instead of the employee’s bank account. Amounts awaiting remittance create liabilities.
Accounting also distinguishes when wages are earned from when cash is paid. Unpaid wages can be accrued as an expense and liability; some labor costs enter the cost of inventory or another asset under the relevant accounting rules.
UK payroll and PAYE
PAYE means Pay As You Earn. Employers use it to report pay and collect applicable Income Tax and National Insurance through payroll. Employees can see gross pay: UK payslips must show pay before and after deductions and explain the deductions required by the rules.
Software can calculate pay, maintain records and submit reports. HMRC’s Basic PAYE Tools is available for employers with fewer than ten employees, although its features do not replace every payroll function. Using software or an outside provider does not remove the employer’s responsibilities.
US payroll taxes in 2026
The IRS employer guide for 2026 distinguishes federal income-tax withholding from employment taxes. For covered wages, Social Security tax is generally 6.2% each for employer and employee, up to the 2026 annual wage base of $184,500.
Regular Medicare tax is generally 1.45% each, without a wage-base ceiling. Employers must also withhold 0.9% Additional Medicare Tax on wages they pay above $200,000 in a calendar year, without an employer match. The employee’s final liability can depend on filing status and other earnings.
Federal unemployment tax is generally an employer tax. State and local obligations, exceptions and other rules can also apply. Consequently, describing every payroll tax as one evenly split 15.3% charge is incomplete.
Payroll and human resources
Human resources maintains information about employment, compensation and leave; payroll turns relevant information into calculations and payments. Accurate records and clear payslips help explain changes in take-home pay and reveal errors that require correction.
Last checked and updated on November 11, 2026 by the MBN editorial team.