
Replacement cost is the current amount needed to replace an asset with one providing comparable function, capacity or quality. It answers what replacement would cost today, rather than what the existing asset originally cost or what it could sell for.
The estimate must identify what is being replaced and the relevant costs. Replacing a building, restocking merchandise and settling an insurance claim involve different assumptions.
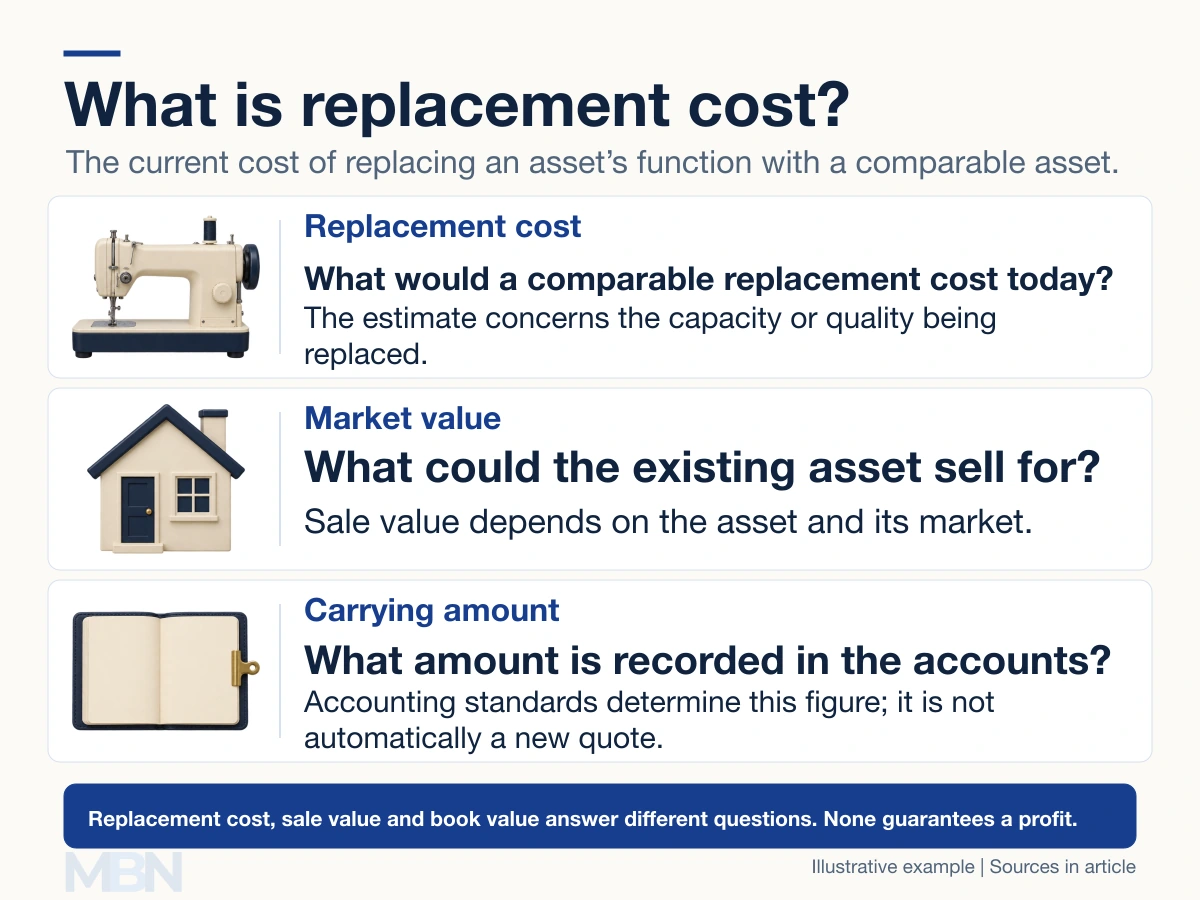
Replacement cost and market value
Market value concerns the price obtainable in the relevant market. It is not simply another name for retail price, and it is not automatically higher or lower than replacement cost.
A used machine might sell for $800 while a comparable new machine costs $2,000. The figures describe different transactions. The gap does not represent an immediately available profit.
For buildings, the Royal Institution of Chartered Surveyors explains that reinstatement cost is not a market valuation. A rebuilding estimate can include demolition, professional fees and construction requirements. A property’s sale price also reflects its land and location.
What does replacement-cost insurance mean?
The NAIC compares replacement-cost and actual-cash-value coverage. Replacement-cost coverage generally uses the cost of repair or replacement with like kind and quality, without deducting depreciation. Depreciation is the reduction attributable to age, use or wear.
Actual cash value commonly reflects replacement cost less depreciation, but the legal valuation method can depend on the jurisdiction and policy. Neither description guarantees an unrestricted payment: the loss must be covered, limits must be sufficient and applicable deductibles still matter.
A deductible is the part of a covered loss borne by the policyholder. Replacement-cost cover does not mean an insurer pays the full replacement estimate regardless of that amount.
A worked insurance example
Assume a covered item costs $3,000 to replace. For this example, depreciation is $900 and the deductible is $500. On an actual-cash-value basis, the assumed payment is $3,000 minus $900 minus $500, or $1,600.
On a replacement-cost basis, the potential total is $3,000 minus $500, or $2,500, if the claim meets the policy’s conditions. The $900 difference is not necessarily paid immediately.
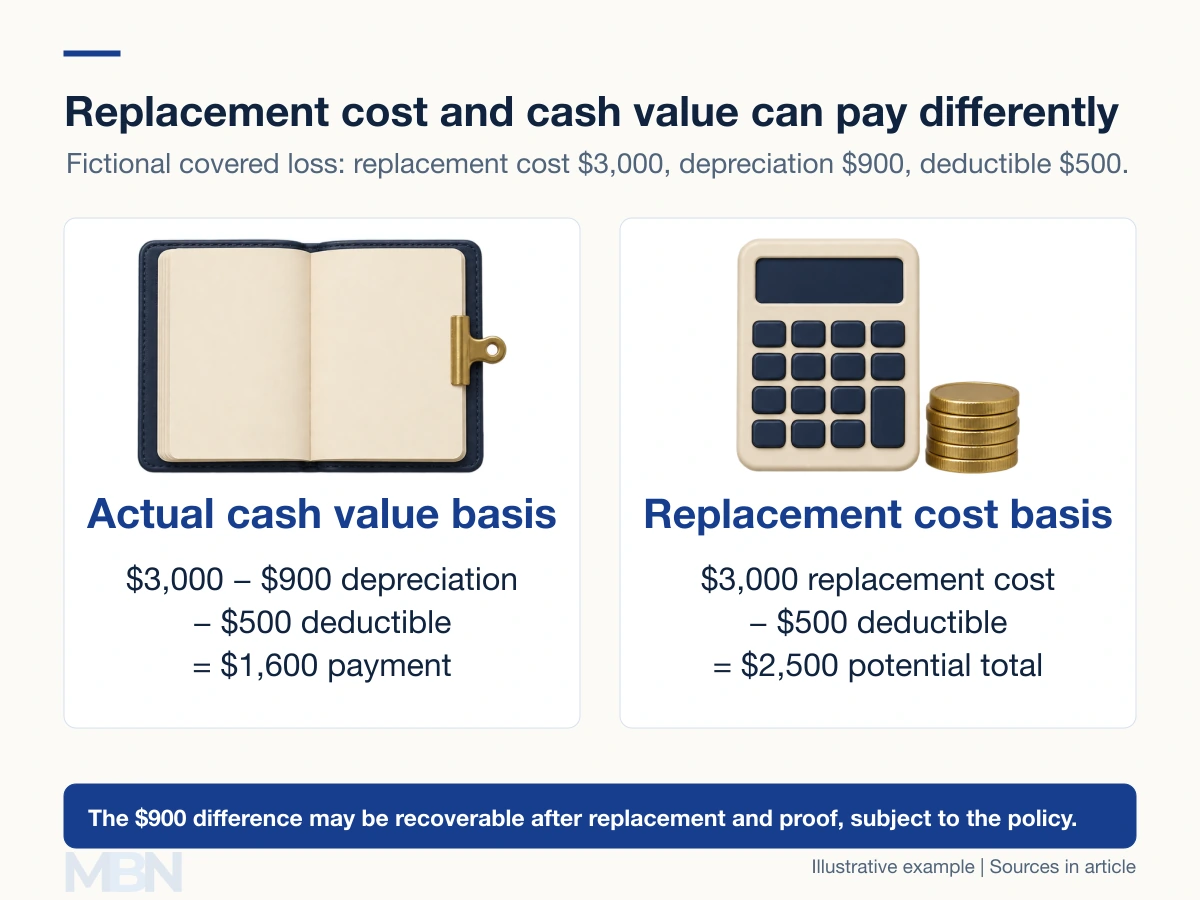
The North Carolina insurance regulator explains recoverable depreciation: the insurer may initially pay actual cash value, then release an additional amount after repair or replacement and submission of receipts. Deadlines, actual expenditure and policy terms can affect recovery.
Replacement cost is not automatically book value
A carrying amount is the value recorded in the accounts under the applicable accounting rules. A new supplier quote does not automatically replace that figure.
For example, IAS 2 governs inventory accounting under IFRS, an international financial-reporting framework. Under its lower-of-cost-and-net-realizable-value rule, ordinary inventory costing $40 is not written up to $50 simply because $50 is now needed to restock it. If its net realizable value is $35, it is measured at $35, assuming the usual rule applies.
Net realizable value means the expected selling price less completion and selling costs. Replacement cost can inform purchasing and pricing decisions, but it does not establish either the accounting profit or the final insurance settlement.
Last checked and updated on November 4, 2026 by the MBN editorial team.