
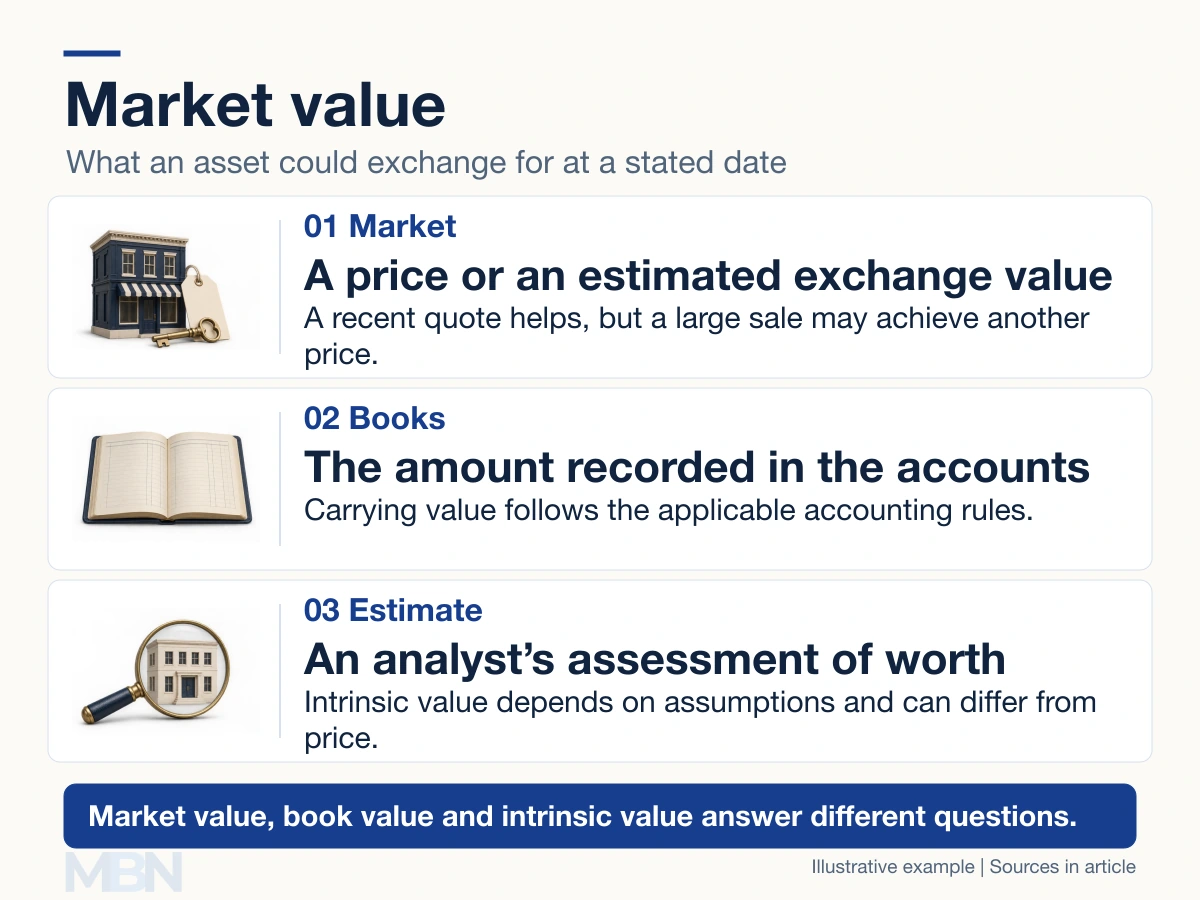
Market value is the amount an asset could exchange for in the market at a particular date. For actively traded securities, quoted prices provide evidence of value. For property or an unlisted business, a valuation usually requires an estimate.
A transaction price is what one trade actually achieved. A valuation may instead estimate an exchange under specified conditions. The valuation date, asset, market and assumptions therefore matter.
How market value is determined
For a frequently traded share, the latest price is an accessible reference. It does not guarantee that every holding can be sold at that price. Bid and offer prices, the size of the order and market liquidity, meaning the ease of trading, can affect the amount achieved.
A property or private business may have no continuously quoted price. Valuers can use comparable transactions, expected cash flows and asset information. An asking price is evidence of what a seller wants, not proof of what a willing buyer would pay.
Technical definitions also differ. For example, IFRS 13 fair value concerns an orderly transaction between market participants at the measurement date. Tax, lending and other valuation rules may specify different assumptions. These terms should not automatically be treated as interchangeable.
A company’s market capitalization
For a listed company, market capitalization is the market value of its outstanding shares. The Investor.gov definition gives the basic calculation: current share price multiplied by shares outstanding.
Suppose a hypothetical company has one million ordinary shares outstanding at $30 each. Its market capitalization is $30 million. If the price rises to $33 with the share count unchanged, market capitalization becomes $33 million. Different share classes require their respective prices and outstanding counts.
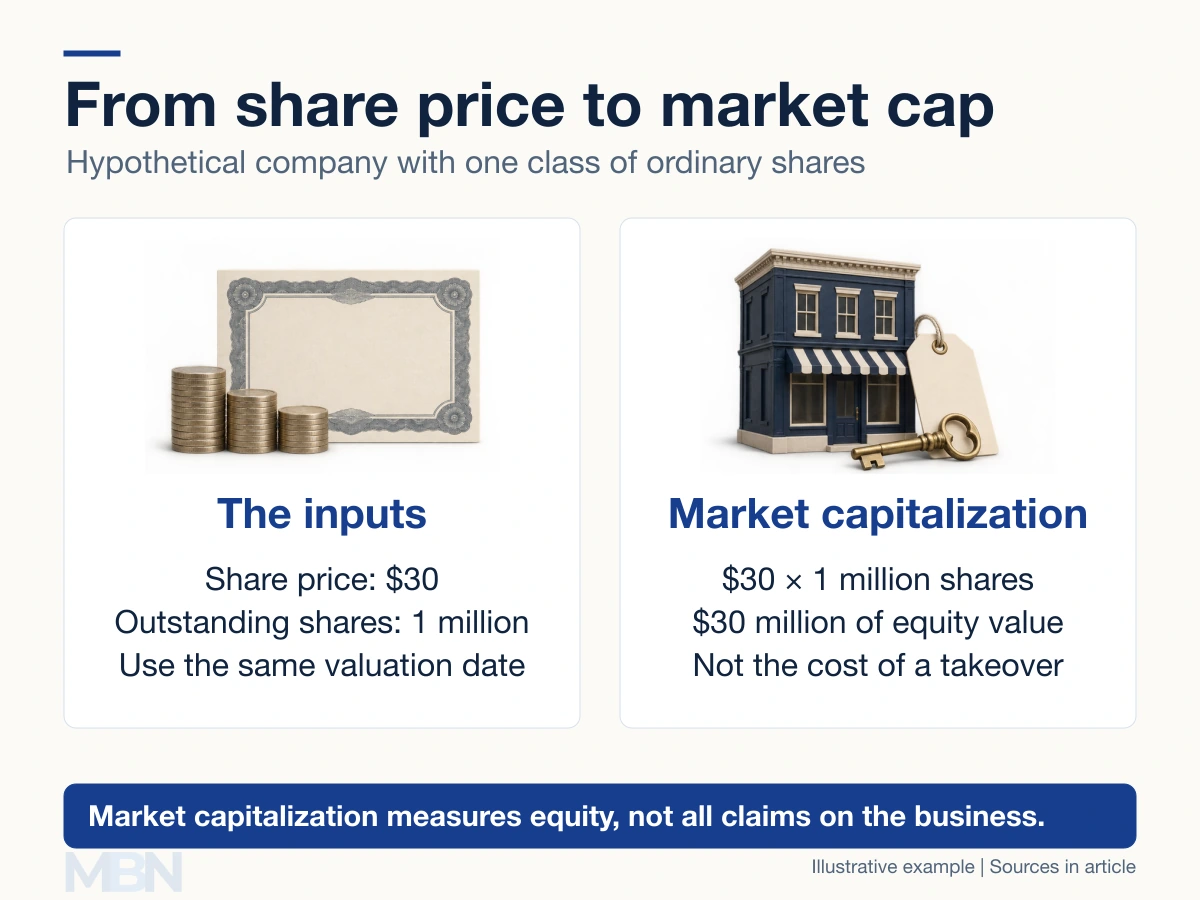
Market capitalization represents equity value. It is not automatically the value of the operating business or the price a buyer would pay to take control. Enterprise value commonly adjusts equity value for debt and cash, with other adjustments depending on the business and convention used.
Market value versus book value
Book value, or carrying amount, is the amount recorded under accounting rules. It does not necessarily remain at the original purchase price. Depreciation, impairment, improvements and permitted revaluations can change an asset’s carrying amount. IAS 16 explains cost and revaluation models for property, plant and equipment.
For example, a machine might have a carrying amount of $40,000 but an estimated resale value of $55,000. The $15,000 difference is not necessarily a realized profit. An actual sale, selling costs and the applicable accounting and tax rules determine the resulting gain.
Why market value changes
Expected earnings, interest rates, risk and supply and demand can change valuations. Paying a dividend does not automatically increase a company’s market value: cash leaves the company, while investors receive the distribution. Investor.gov explains the related ex-dividend price effect.
Finally, market size measured by annual sales is a different use of the word market. Sales of 935 machines at $1 million each would total $935 million in sales value, not establish the market capitalization of their manufacturer.
Last checked and updated on November 10, 2026 by the MBN editorial team.