
Risk concerns uncertainty and its possible consequences. In everyday use, it usually means the possibility of harm or loss. In business risk management, it can also describe uncertainty that affects objectives positively or negatively. Probability alone does not tell the whole story.
The ISO 31000 framework addresses opportunities as well as threats. The OECD’s explanation of the standard describes risk through uncertainty’s effect on objectives. The relevant definition therefore depends on the context.
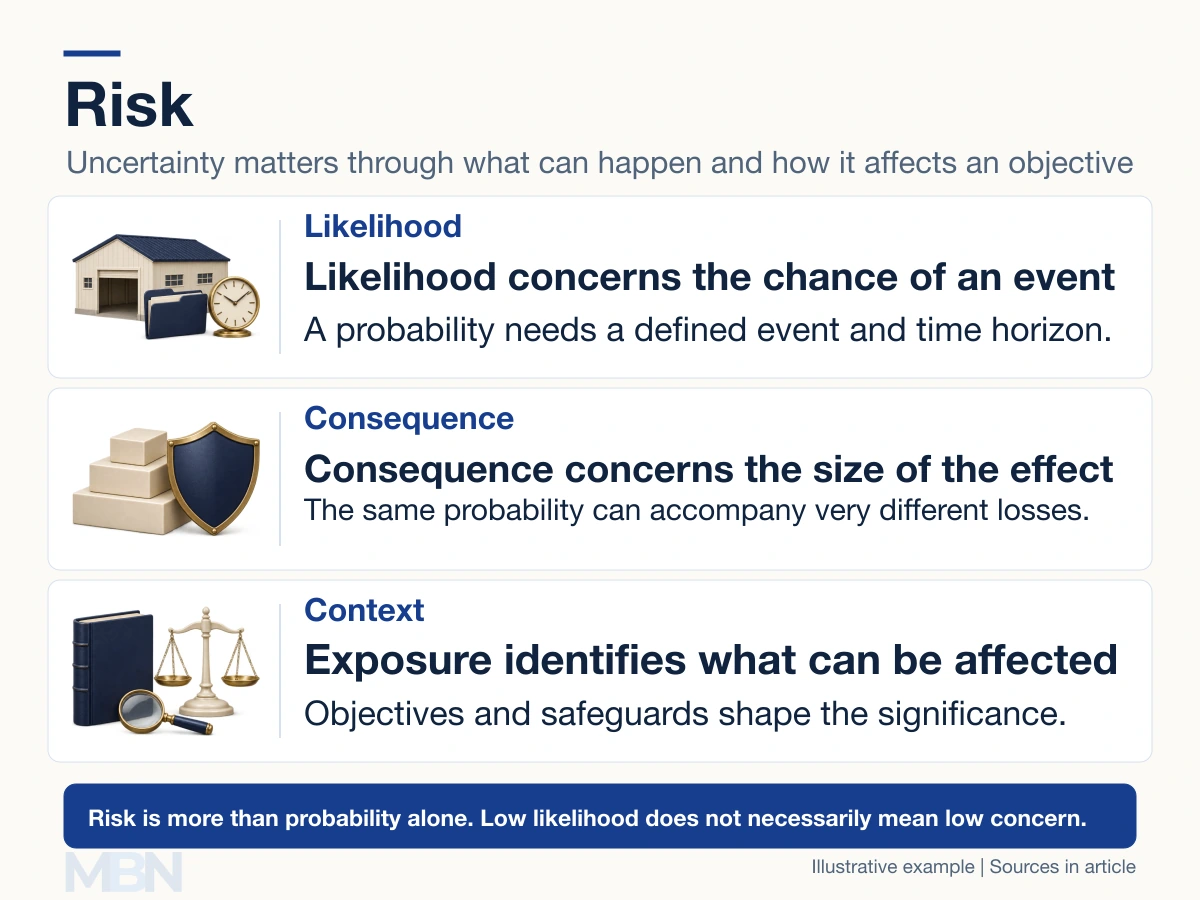
Likelihood, consequence and exposure
Likelihood concerns how plausible an event is, often expressed as a probability for a specified period. Consequence concerns the size and nature of its effect. Exposure concerns what could be affected. NIST’s risk glossary combines likelihood and adverse impact in several of its definitions.
A hazard is a potential source of harm, such as water on a warehouse floor. Risk concerns possible outcomes in the actual circumstances, including who is exposed, safeguards and the severity of a fall. A hazard and a probability are not interchangeable.
Some risks can be reduced, transferred or avoided, but prevention cannot guarantee that every uncertain event disappears. Safeguards can fail, and transferring financial loss does not necessarily remove the underlying disruption.
Risk in finance
The SEC describes financial risk through uncertain returns and potential harm. An investment may lose principal, generate less income than expected or become difficult to sell. A volatility measure includes both upward and downward return variation, while a downside measure focuses on adverse outcomes.
Higher risk can lead investors to demand a higher expected return, but taking it does not guarantee a reward. A high quoted yield may partly reflect the possibility that promised payments will not be made.
Capital, market and interest-rate risk
Capital risk concerns losing invested principal. Market risk concerns adverse price movements, including equities, bonds, currencies and commodities. Interest-rate risk includes the effect of changing rates on prices, income and funding costs, not only the possibility of rates rising sharply.
Conventional fixed-rate bond prices generally fall when market yields rise. Longer maturity can increase sensitivity, but coupon structure and duration also matter. Duration estimates a bond’s sensitivity to yield changes. Inflation risk concerns a loss of purchasing power. The SEC’s bond guide explains these distinctions.
Credit, country and settlement risk
Credit risk concerns a borrower or counterparty failing to meet an obligation, or deteriorating in credit quality. Default is failure to pay or perform as required. Sovereign risk concerns a government’s obligations; country risk is broader and can include political, legal, economic and transfer restrictions.
Exchange-rate risk concerns changes in the currency value of assets, liabilities or cash flows. The SEC explains additional risks in international investing. There is no single country benchmark appropriate to every exposure.
Settlement risk concerns agreed cash or securities failing to arrive when due. It can include losing principal after one party has performed while the other has not. Delayed settlement can also create liquidity pressure. The Federal Reserve describes the risks in payment and settlement systems.
Liquidity, refinancing and reinvestment risk
Funding liquidity risk concerns meeting cash and collateral obligations when due. Market liquidity risk concerns selling or closing a position promptly without an unacceptable price impact. A solvent business can still face an immediate cash shortage. Basel guidance explains funding liquidity and related market pressures.
Refinancing risk is the possibility that maturing debt cannot be replaced, or can be replaced only on worse terms. Reinvestment risk concerns cash received being reinvested at a lower return, as the Municipal Securities Rulemaking Board explains. It can affect coupons, maturities and early repayments.
Operational and underwriting risk
The Basel framework defines operational risk through losses from failed processes, people, systems or external events. A payment outage can create operational and liquidity problems together.
For an insurer, underwriting risk includes claims and expenses exceeding expectations relative to premiums. The Washington insurance regulator’s glossary defines underwriting loss. In securities issuance, an underwriter committed to purchase shares can instead face losses from selling them on unfavourable terms. The contract determines the exposure.
Why an average loss is not enough
Consider a 10% annual chance of losing £10,000 and a 1% annual chance of losing £100,000. Assume each event can happen at most once during the year, with no loss otherwise. Each has an expected loss of £1,000.
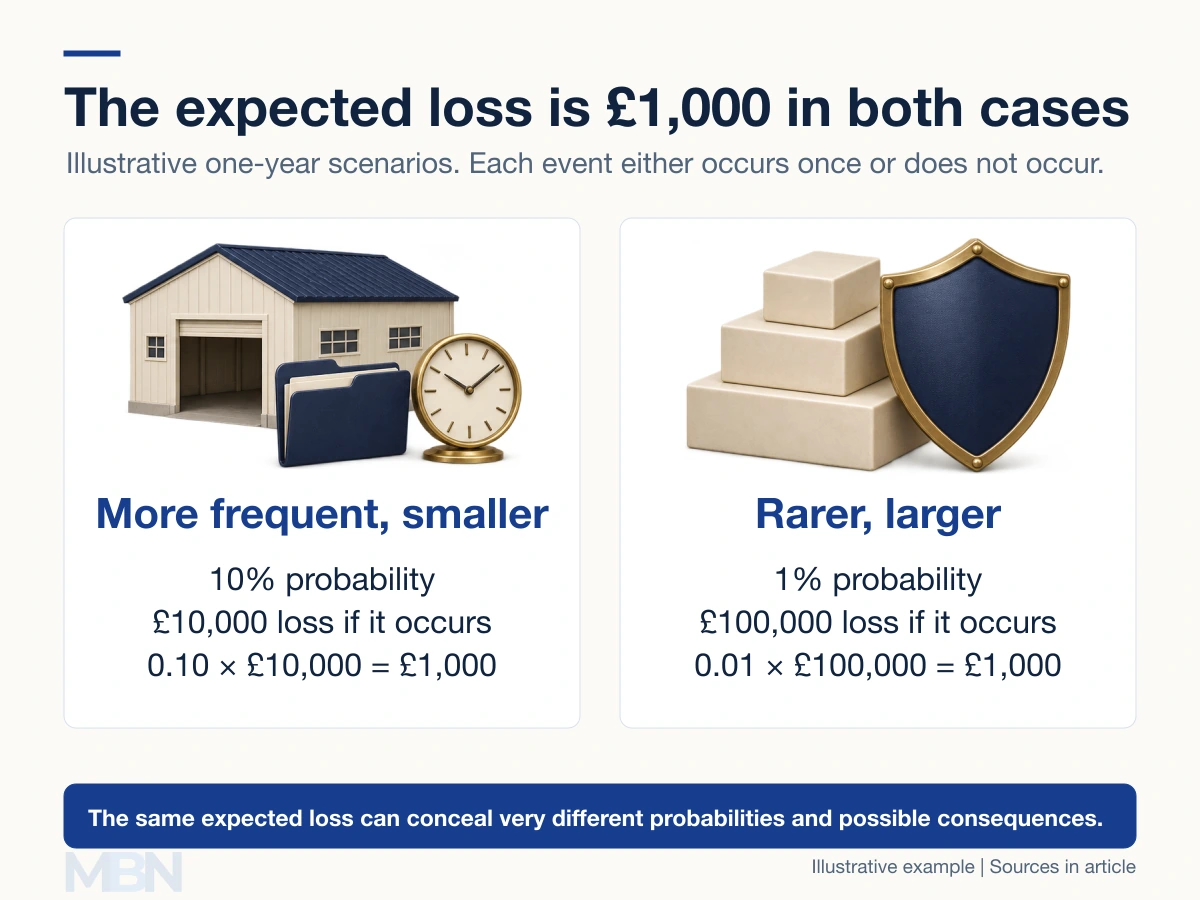
The rarer loss may be much harder to absorb. Expected loss does not describe the whole range of outcomes, maximum exposure, timing or connection to other risks. Estimated probabilities can also be wrong.
Risk preferences and management
People differ in their preferences for uncertainty and their financial capacity to bear losses. Willingness to take risk does not establish ability to recover from it.
Risk management involves identifying, analysing, evaluating, treating and monitoring uncertainty in its context. It informs decisions and contingency arrangements. It cannot ensure uninterrupted operations, perfect forecasts or an investment return.
Last checked and updated on November 11, 2026 by the MBN editorial team.