
Share capital is capital associated with a company’s issued shares. In a nominal-value system such as the UK’s, issued share capital is based on the shares’ nominal value, not automatically the full price investors paid.
People sometimes use the term more broadly for money contributed through shares or for a company’s share structure. The meaning must be clear. Nominal share capital, total issue proceeds and stock-market value are different figures.
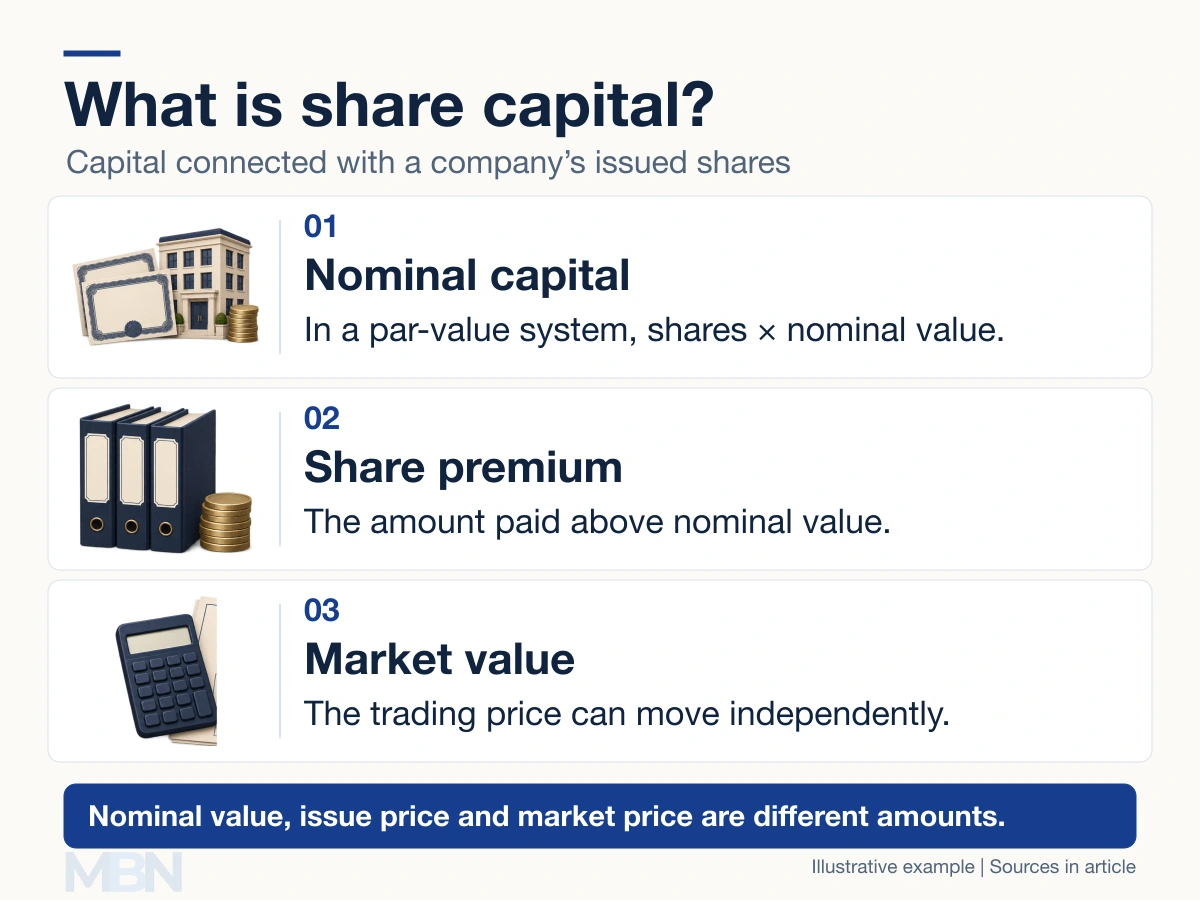
Nominal value is not the issue price
Section 542 of the UK Companies Act 2006 requires shares in a limited company with share capital to have a fixed nominal value. A share with $1 nominal value can be issued for $30. The $1 is a legal capital amount, not a statement that the share could only be worth $1.
Under section 610, premiums on share issues are generally transferred to a separate share premium account. Consequently, multiplying the number of shares by their full issue price does not necessarily calculate the nominal share capital account.
Rules differ elsewhere. Delaware corporate law permits stock with or without par value and has its own capital rules. A UK nominal-value formula should not be presented as a universal accounting instruction.
A checked share issue example
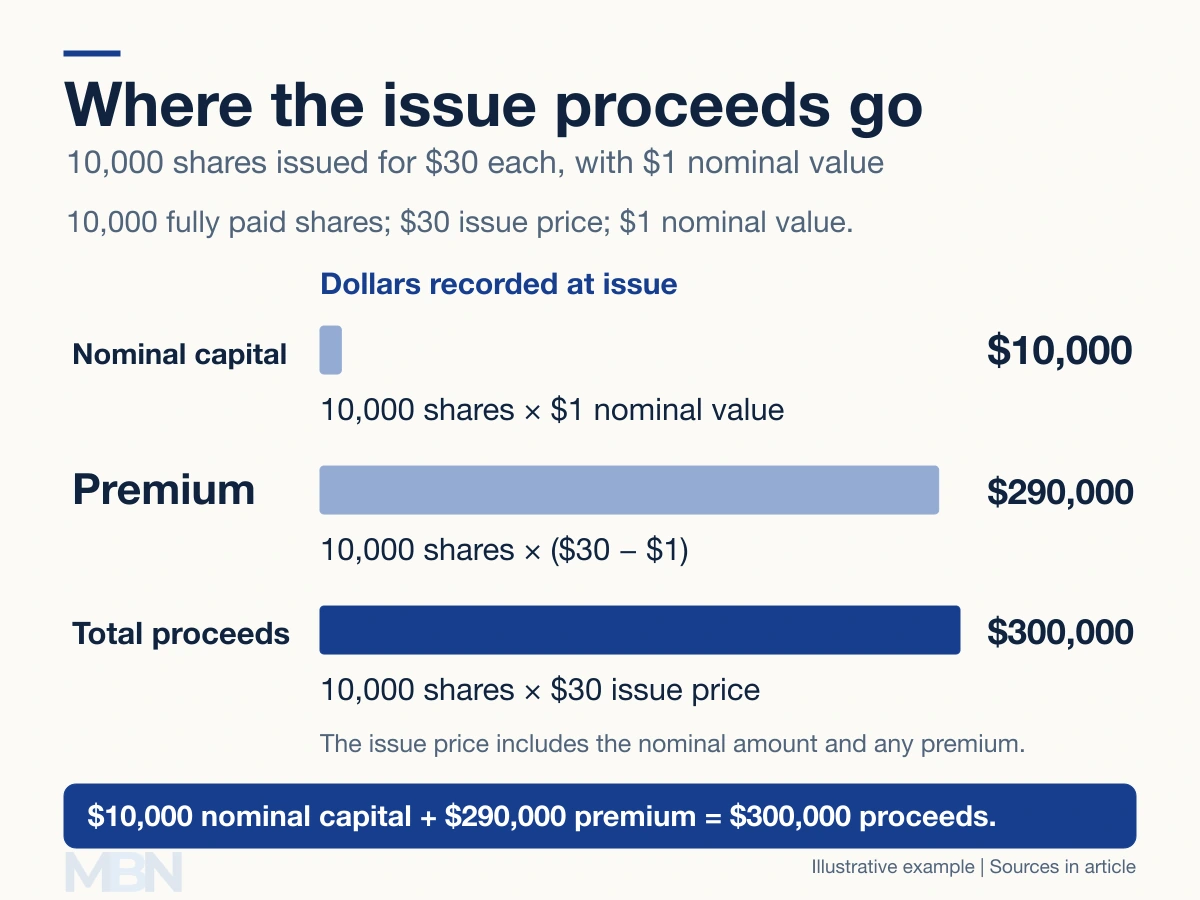
Suppose a hypothetical company issues 10,000 fully paid ordinary shares for $30 each, with a nominal value of $1 each. Ignoring issue costs, the company receives $300,000.
Under the nominal-and-premium approach illustrated here, nominal share capital is 10,000 × $1 = $10,000. Share premium is 10,000 × $29 = $290,000. Together they equal the $300,000 contributed.
If those same 10,000 shares later trade at $70, their aggregate market value is $700,000, assuming all are outstanding. That price change does not itself add $400,000 to the company’s cash or change its recorded nominal capital.
Shares issued and shares traded
A new issue by the company can raise funds for the company. A later sale between two investors ordinarily transfers money between those investors, rather than raising fresh share capital for the issuer.
Issued shares and outstanding shares are also different concepts. Shares repurchased and held in treasury can remain issued while being excluded from outstanding shares. The applicable company law and accounts determine the treatment.
New shares can be issued for noncash consideration where permitted. For example, shares may be exchanged for a business or other property. This still requires proper valuation and legal and accounting treatment.
Share capital is only part of equity
The SEC’s financial-statement guide explains shareholders’ equity as the residual after liabilities are deducted from assets. Total equity can include contributed capital, retained earnings and other reserves. It is not simply the share capital figure.
Share rights also matter. Ordinary and preference shares can have different voting, dividend and redemption provisions. As HMRC explains under IAS 32, some instruments legally called preference shares are financial liabilities because of their contractual obligations. The name alone does not establish equity classification.
Why the distinction matters
Share capital can change through new issues and other lawful capital transactions. It is not a live measure of a company’s selling price, cash balance or financial strength. Understanding it alongside assets, liabilities and the rest of equity gives a more useful picture.
Last checked and updated on November 5, 2026 by the MBN editorial team.