
Stress testing examines how a bank, investment portfolio or business would cope with adverse conditions. It applies assumed shocks, such as a recession, market-price falls or funding withdrawals, and estimates their financial effects.
The aim is to expose vulnerabilities before the conditions occur. A hypothetical stress loss is neither a loss already incurred nor a prediction that the scenario will happen.
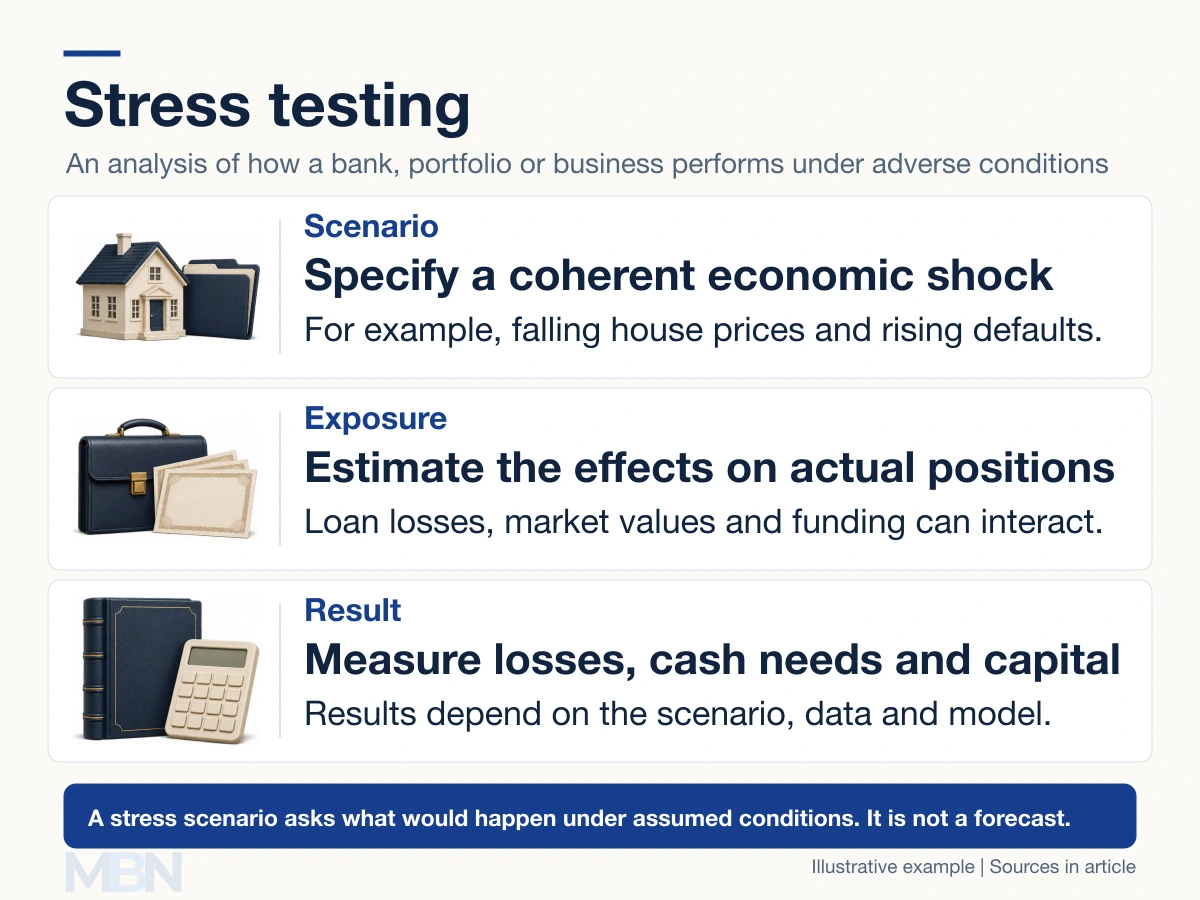
How a stress test works
An analyst starts with financial exposures, specifies a scenario and models the resulting changes in income, losses, cash flows and capital. A sensitivity test may change one input, such as an interest rate. A scenario test combines related developments, such as unemployment rising while property prices fall.
Credit risk concerns borrowers failing to repay. Market risk concerns changes in asset prices and other market factors. Liquidity risk concerns meeting payments when due, including when funding disappears or assets cannot be sold quickly without a large discount.
Capital absorbs losses; liquidity supports payments. A capital stress test does not automatically establish that funding would remain available. Portfolio tests can similarly reveal concentrated exposures that are less apparent in ordinary conditions.
The Basel Committee’s principles treat stress testing as a risk-management and supervisory tool, supported by governance, appropriate data, documented methods and use of the results.
A simplified bank example
Suppose a bank has $12 million of Common Equity Tier 1, or CET1, capital and $100 million of risk-weighted assets. CET1 is the highest-quality regulatory capital; risk-weighted assets adjust exposures for regulatory measures of risk. Its CET1 ratio is 12%.
Assume a stress produces a $5 million net loss that reduces CET1 directly, with everything else unchanged. Capital falls to $7 million and the ratio to 7%. That is a fall of 5 percentage points.
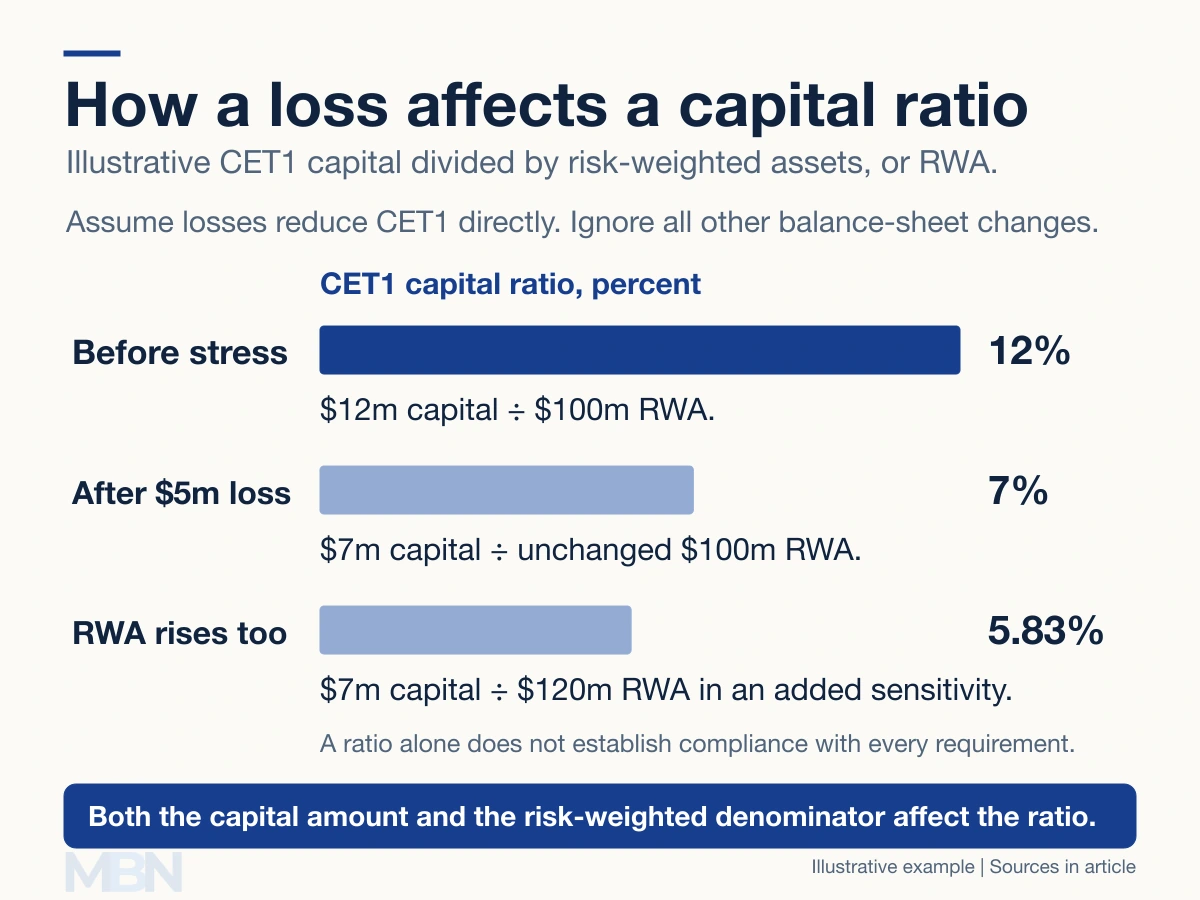
If the remaining capital is $7 million but risk-weighted assets increase to $120 million, the ratio falls further to about 5.83%. Actual tests model more moving parts, including revenues, provisions and changes over time. These figures are teaching assumptions.
Regulatory tests and their limits
US supervisory stress-test requirements depend on the institution and regulatory framework. The Federal Reserve’s 2026 documentation identifies covered bank holding companies, savings and loan holding companies and foreign-bank intermediate holding companies with at least $100 billion in assets. Frequency and obligations depend on the applicable rules and institution category.
Company-run requirements are separate. For example, the FDIC’s 2026 release applies to covered institutions with more than $250 billion of total consolidated assets. These thresholds should not be combined into one universal rule.
The Bank of England’s approach from 2025 expects a major Bank Capital Stress Test every other year, with other assessments in intervening years and exploratory exercises for different risks. The former annual framework is not the current general description.
Results depend on the shocks chosen, exposure data, model relationships and assumed management responses. They can inform capital buffers, contingency planning and risk limits. Strong performance under one scenario does not prove resilience to every possible crisis.
Outside finance, stress testing has a related meaning. An IT stress test, for example, examines how a system behaves under extreme workload or resource constraints, including whether it fails and recovers safely.
Last checked and updated on November 11, 2026 by the MBN editorial team.