
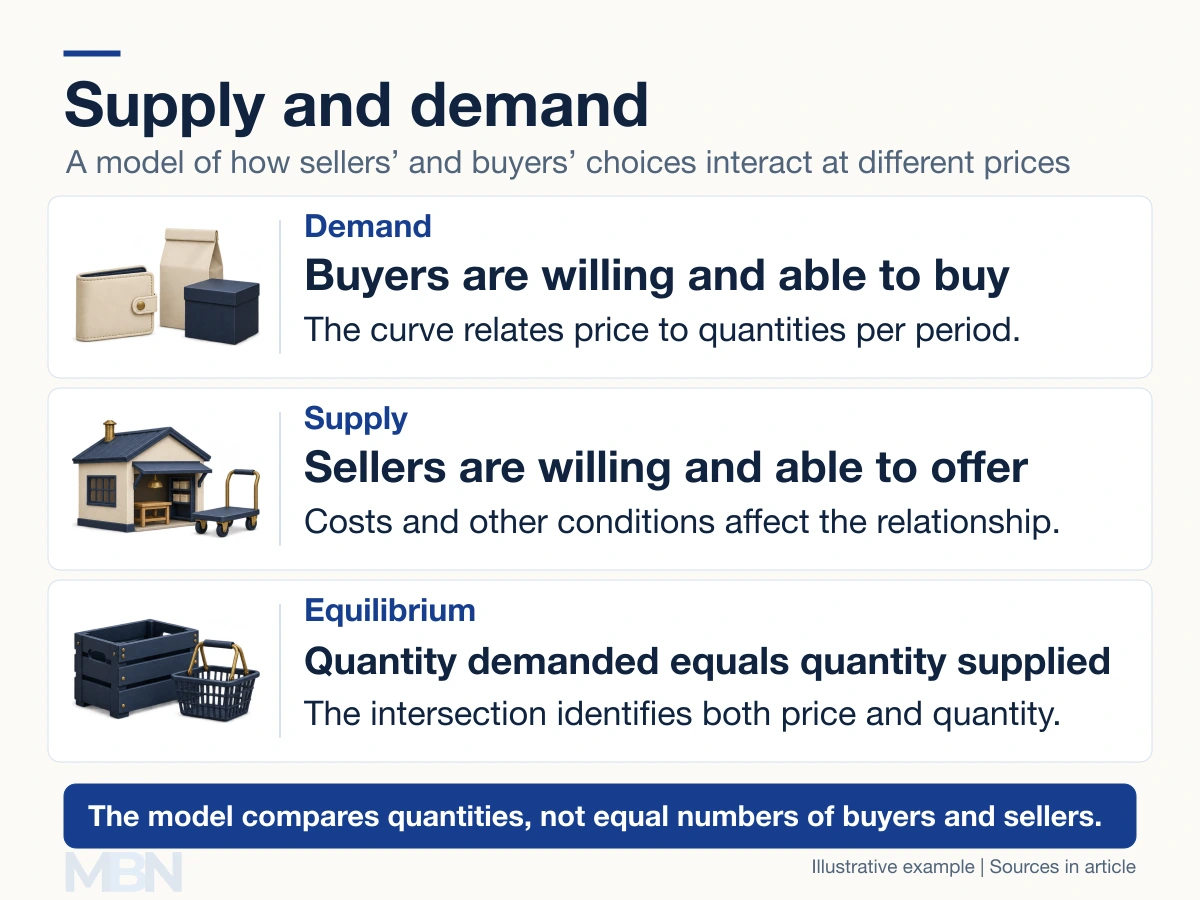
Supply and demand describe how sellers’ offers and buyers’ purchases relate to price. In a basic competitive-market model, their interaction determines an equilibrium price and quantity.
Demand concerns the quantities buyers are willing and able to buy at different prices. Supply concerns the quantities sellers are willing and able to offer. Both need a defined product, market and time period.
Finding the equilibrium
Suppose a hypothetical weekly market has quantity demanded equal to 12 minus the price in dollars, and quantity supplied equal to that price. At $6, buyers demand 6 units and sellers offer 6 units.
This is equilibrium: quantity demanded equals quantity supplied. The intersection identifies both a price and a quantity. It does not mean that the number of buyers equals the number of sellers, or that prices can never change.
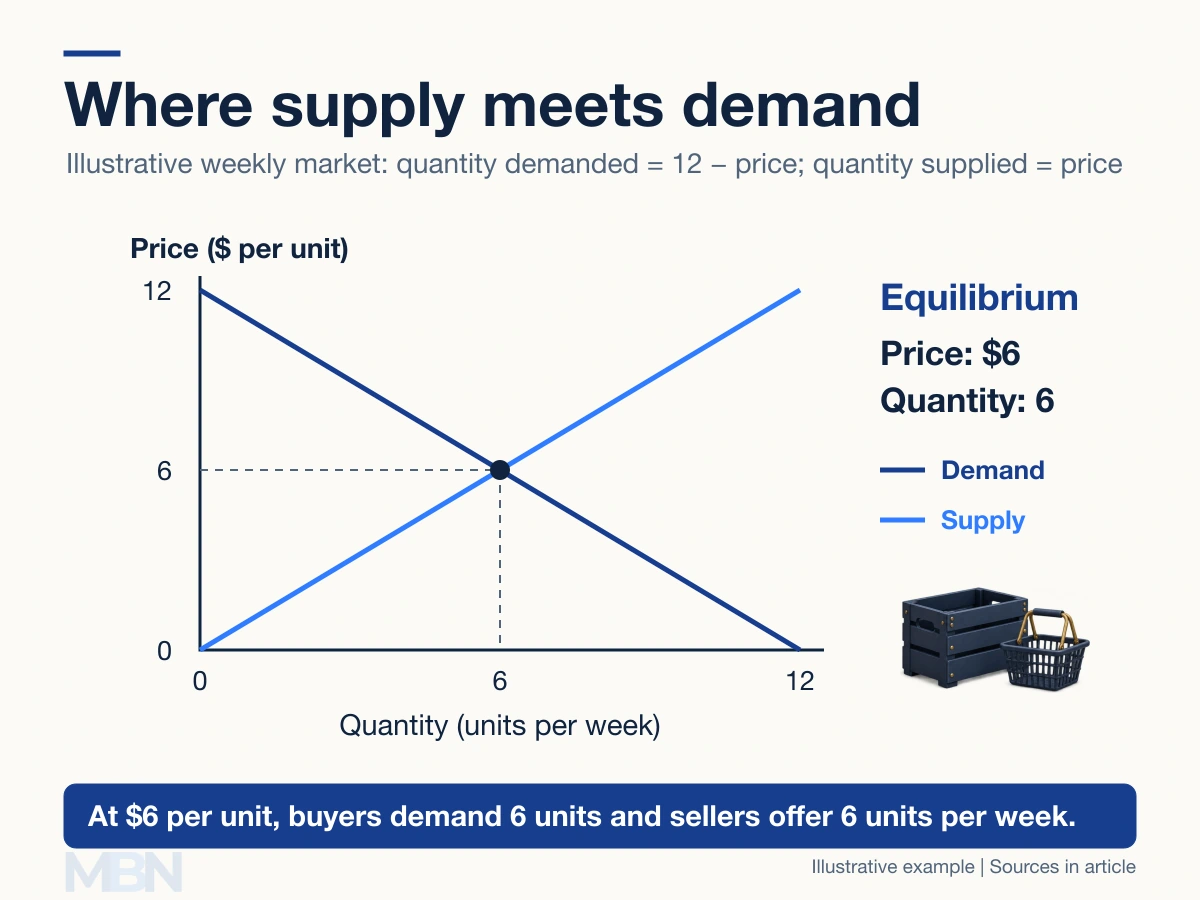
OpenStax explains how the two schedules interact. At $4 in this example, buyers demand 8 units while sellers offer 4, creating a shortage of 4 units at that price. At $8, sellers offer 8 units while buyers demand 4, creating a surplus of 4 units.
These gaps can create pressure for price adjustment where prices are free to respond. Contracts, regulation, adjustment costs or rationing can prevent an immediate move to equilibrium. A shortage is not proof that a price must rise at once.
What happens when a curve shifts?
With an upward-sloping supply curve and downward-sloping demand curve, an increase in demand alone raises equilibrium price and quantity. A decrease in demand alone lowers both.
An increase in supply alone lowers equilibrium price and raises quantity. A decrease in supply alone raises price and lowers quantity. Each result holds the other curve unchanged; these are conditional model results, not universal predictions for every market.
Demand and supply can shift at the same time. If both increase, equilibrium quantity rises in the standard model, but the price outcome depends on their relative effects. Observing a price rise alone cannot identify which curve moved.
What perfect competition assumes
Perfect competition assumes many buyers and sellers, a homogeneous product, relevant information and free entry and exit. Individual participants take the market price as given. There is no requirement for equal buyer and seller counts.
A price-taking firm can still face a changing market price when costs, demand or other conditions change. Monopoly power, product differences and bargaining can require different models.
What the basic model leaves out
Taxes can create a gap between the price buyers pay and sellers receive. A binding price ceiling or floor can prevent the market from clearing, as price-control analysis illustrates. Supply and demand remain useful concepts even when prices are regulated.
Equilibrium also does not by itself establish fairness or account for pollution and other effects on third parties. Institutions, information, market power and distribution matter when assessing real outcomes.
Last checked and updated on November 10, 2026 by the MBN editorial team.