
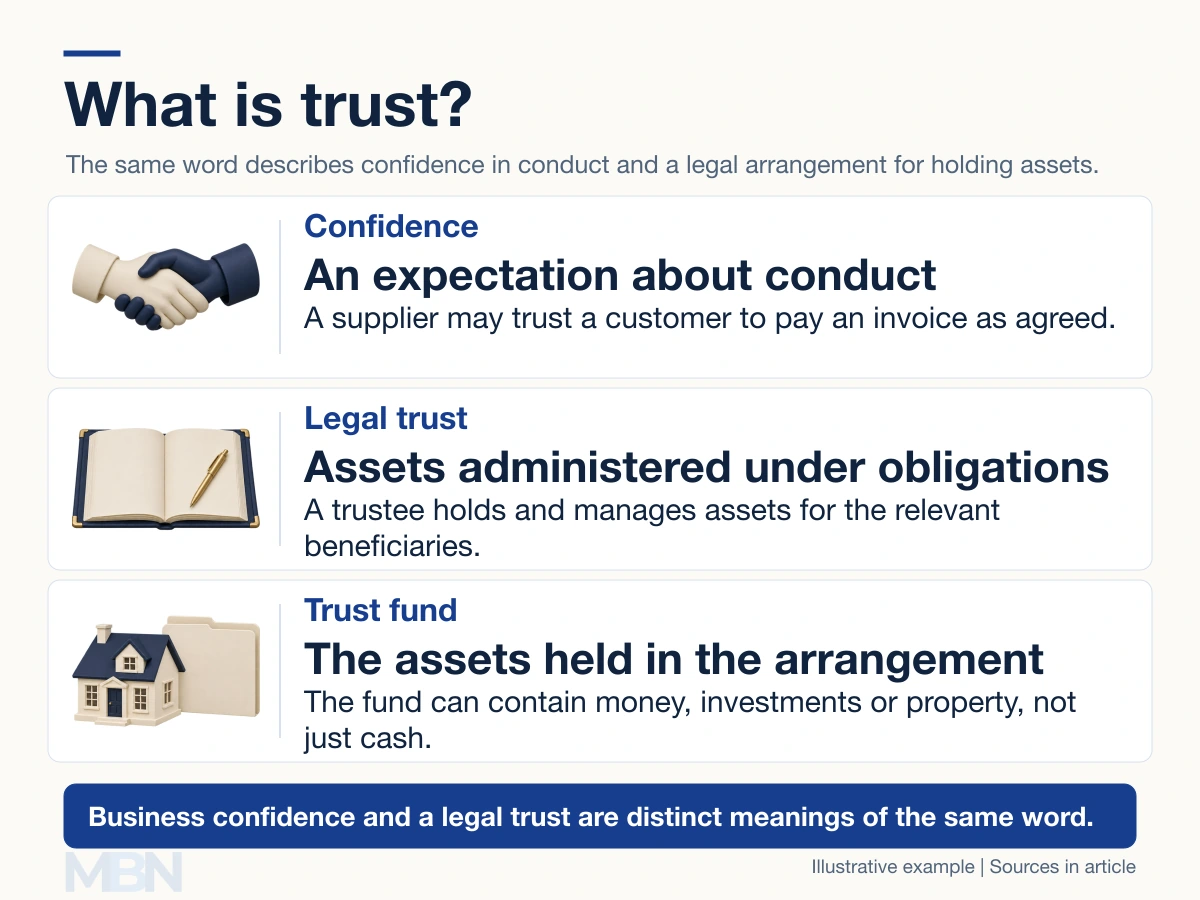
Trust can mean confidence that a person or organisation will behave as expected. In law, a trust is an arrangement under which assets are held and administered for beneficiaries. These meanings are related by an idea of responsibility, but they describe different things.
A customer can trust a business without creating a legal trust. A trust fund, meanwhile, is the money or other assets held within a trust arrangement.
Trust in business relationships
The OECD’s 2017 measurement guidelines describe trust in terms of expectations about positive behaviour. This can concern another person or an institution. Its updated 2026 guidelines address trust in public institutions and the factors associated with it.
In a fictional business example, a supplier delivers goods before payment because it expects an established customer to honour the invoice. The supplier still faces the risk that payment will not arrive. Confidence can make cooperation easier without replacing contracts, records or checks.
Trust therefore need not mean total faith or certainty. Nor does a country’s level of trust, by itself, prove why its economy grows or contracts. Many other conditions affect economic outcomes.
What is a trust fund?
A trust fund is the assets held under a trust. These may include cash, shares, land or buildings. The fund need not be a single bank account.
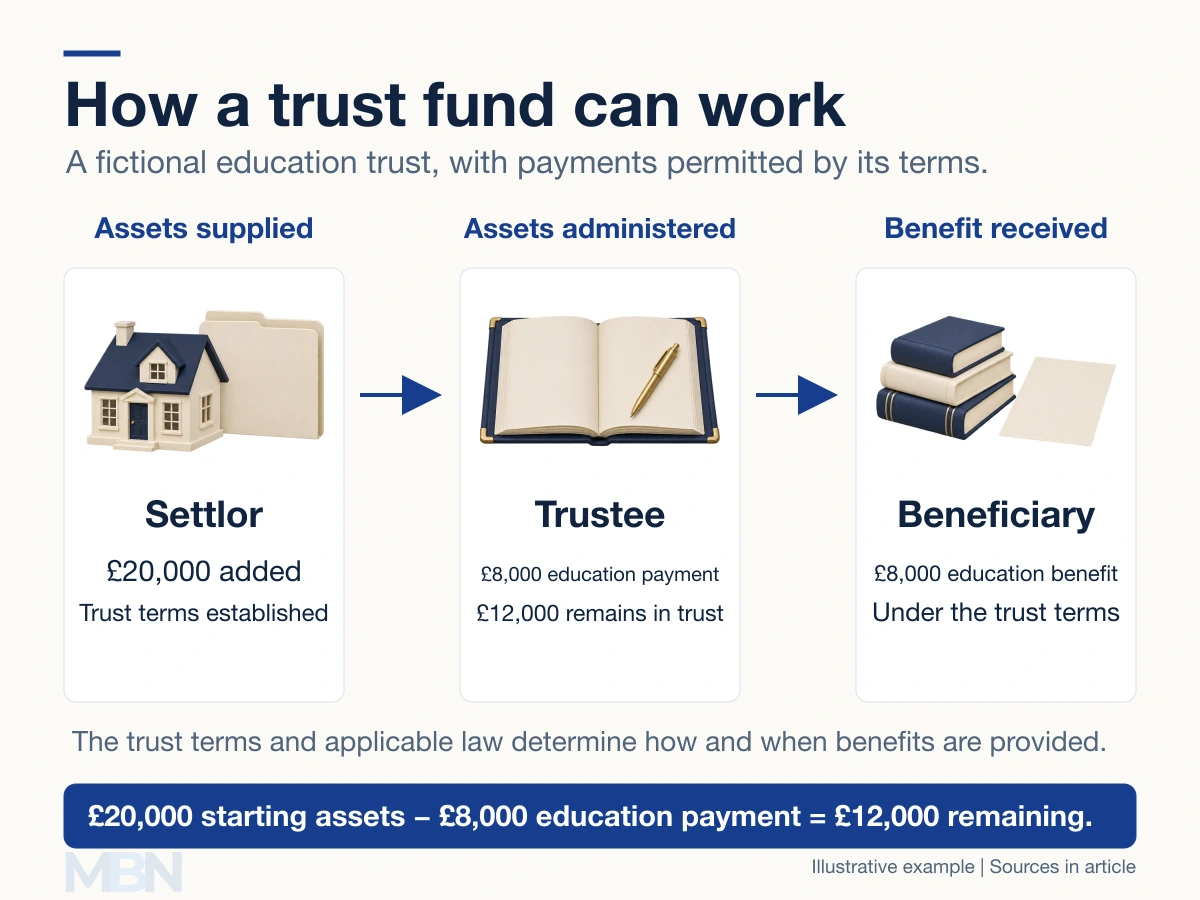
GOV.UK identifies three central roles: the settlor supplies assets, the trustee manages them, and the beneficiary receives benefits. The trustee holds legal title and must administer the assets under the trust’s terms and applicable law.
These roles do not always require three separate people. Depending on the arrangement, a settlor may also be a trustee or beneficiary. A trust may have several trustees or beneficiaries.
Suppose a fictional settlor puts £20,000 into an education trust. Its terms permit the trustee to pay £8,000 in education costs for the beneficiary. With no income, fees, tax or other transactions, £12,000 remains.
This does not mean every beneficiary receives the whole fund at 18. Rights depend on the trust type, its terms and the law. For example, GOV.UK’s bare-trust guidance gives different ages for entitlement in England and Wales and in Scotland. Other trusts can give trustees discretion over payments.
Trust types can overlap
A living trust is created during the settlor’s lifetime; a testamentary trust arises through a will after death. Revocable and irrevocable describe a different feature: whether the creator retains a power to revoke or change the arrangement. The IRS explains these distinctions in its trust guidance.
They are not four mutually exclusive categories. A living trust can be revocable or irrevocable. “Irrevocable” also does not establish that no lawful variation could ever occur. In England and Wales, for example, the Variation of Trusts Act 1958 permits court-approved arrangements in specified circumstances, with protections for affected beneficiaries.
Tax treatment is a separate question
A trust does not automatically eliminate tax, guarantee secrecy or protect every asset from every claim. The result depends on the arrangement, jurisdiction and relevant rules.
Moving a trust offshore does not put it beyond domestic obligations. The IRS describes US tax and reporting requirements for foreign trusts, including situations involving US owners, transfers and distributions. The legal label alone does not determine the outcome.
Last checked and updated on November 4, 2026 by the MBN editorial team.