
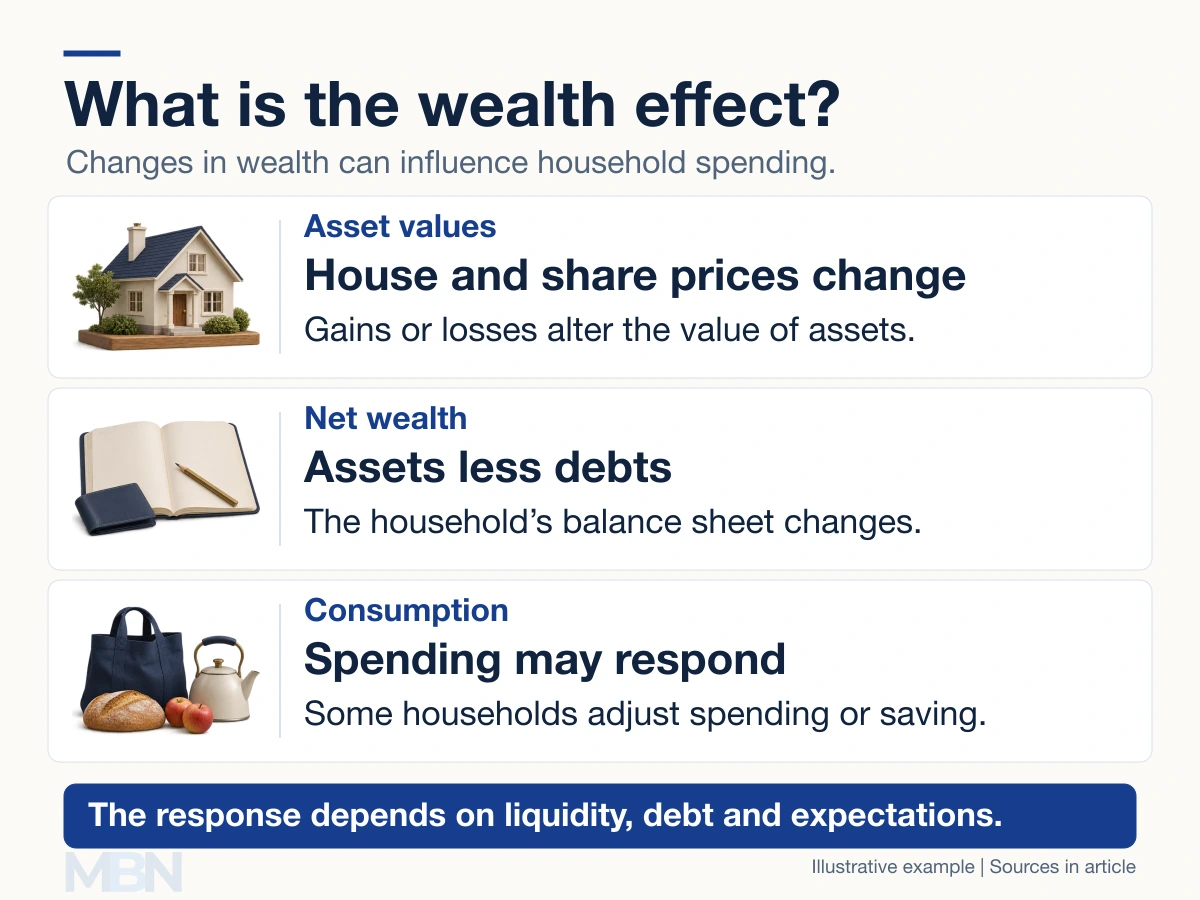
The wealth effect is a change in household spending associated with a change in wealth. Rising asset values can encourage people to consume more, even if their current income has not increased. Falling wealth can work in the opposite direction.
Wealth is the value of assets, such as homes, savings and investments, less debts. Income is a flow received over a period, such as wages earned during a month. A rise in an asset’s market value can increase wealth without adding money to a bank account.
How the wealth effect works
A household that expects a lasting increase in wealth may decide it can afford more consumption over its lifetime. It might spend some savings, sell an asset or borrow against collateral, an asset pledged as security for a loan.
The response goes beyond simply feeling richer. Asset ownership changes the resources available to a household, while expectations and access to finance affect how much of those resources it can use.
The European Central Bank’s analysis explains why the type of wealth, its distribution and households’ circumstances influence consumption responses. There is no fixed amount that every household spends from each dollar gained.
A home-equity example
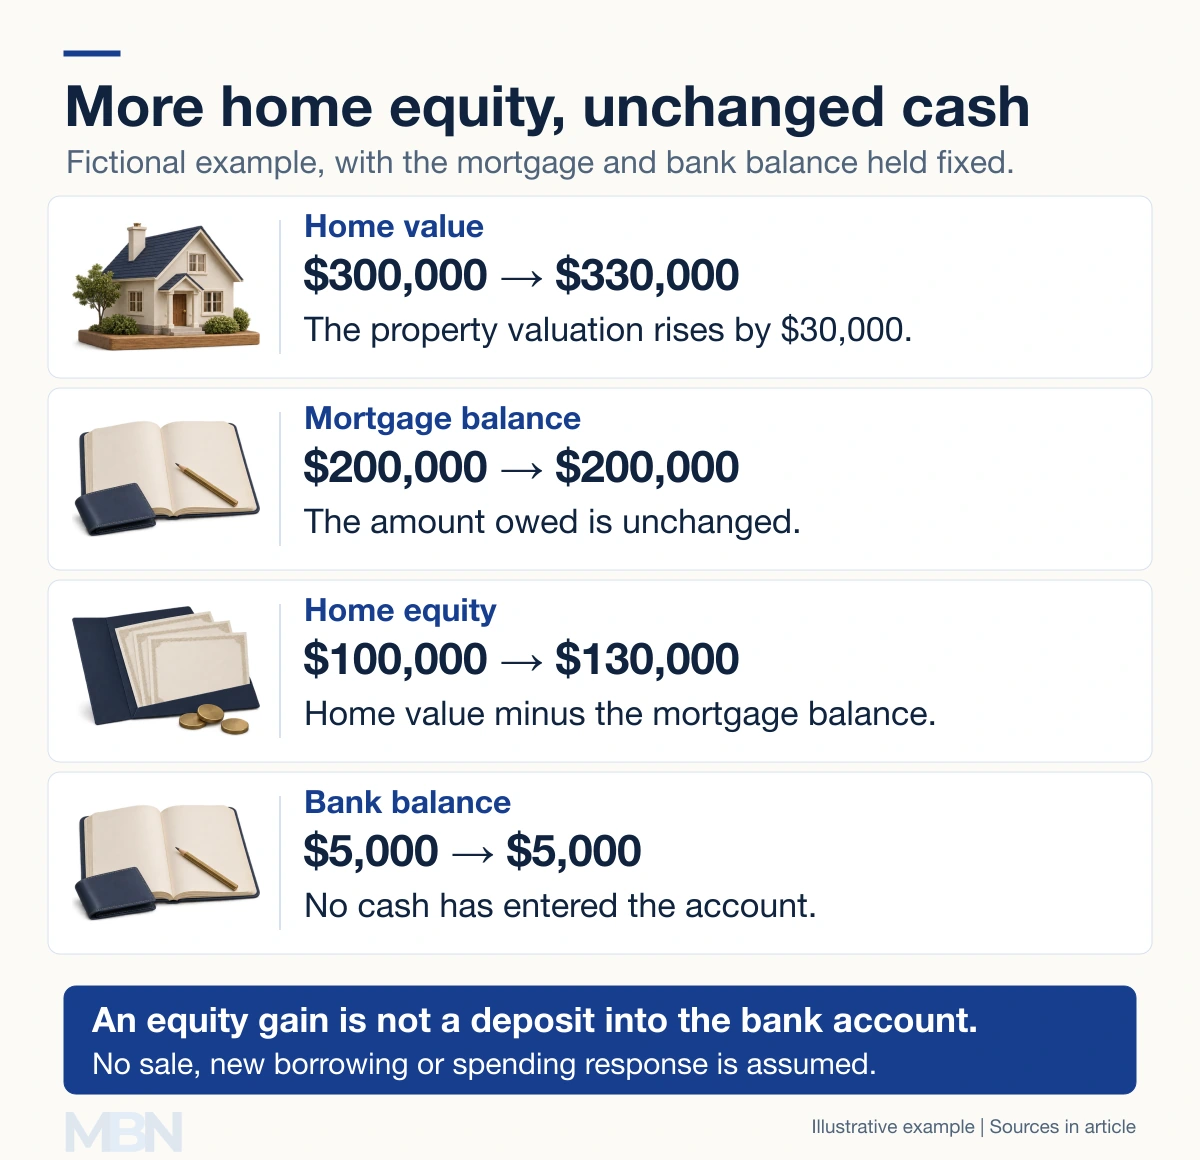
Suppose a fictional household’s home rises in estimated value from $300,000 to $330,000. Its mortgage stays at $200,000. Home equity, meaning the property’s value less the mortgage, rises from $100,000 to $130,000.
The household’s bank balance remains $5,000 and its wages are unchanged. It has a $30,000 valuation gain in home equity, but no extra cash has arrived. The example assumes no sale, new loan or change in spending.
The owner still needs somewhere to live. If it sells and buys a similar home in the same market, the replacement may also cost more. Higher prices can also make housing less affordable for people who do not yet own a home.
Why households respond differently
Liquid assets are relatively easy to turn into spendable money. Housing and some retirement assets are harder to access. A short-lived market gain may produce a smaller response than one a household expects to last.
Debt, borrowing conditions, age and financial security also matter. People who own few of the assets gaining value receive little direct benefit from those gains.
The Bank of England describes how house prices can affect confidence and borrowing against property. A higher valuation does not guarantee that a lender will advance more money.
A negative wealth effect
When investments or property lose value, some households reduce spending or save more to rebuild resources. This can weaken aggregate demand, the total demand for goods and services in the economy.
An Atlanta Fed paper published in September 2026 examines possible consumption declines under hypothetical stock-market falls. Its scenarios illustrate this channel; they are not predictions of a particular crash.
Why correlation is not enough
Asset prices and spending can rise together because both respond to improved income expectations or other conditions. That makes the size of the separate wealth effect difficult to estimate.
A Federal Reserve research paper discusses these shared influences in housing. An observed increase in spending alongside house prices does not, by itself, show how much spending the price increase caused.
Last checked and updated on November 2, 2026 by the MBN editorial team.