
A mortgage is borrowing secured against real estate, such as a home or commercial building. In everyday usage, the word usually means the mortgage loan. The property provides security for the lender, while the borrower owes repayment under the loan agreement.
The Consumer Financial Protection Bureau explains mortgages used to buy a home or borrow against one already owned. Taking a mortgage does not turn the amount borrowed into income or remove the obligation to repay it.
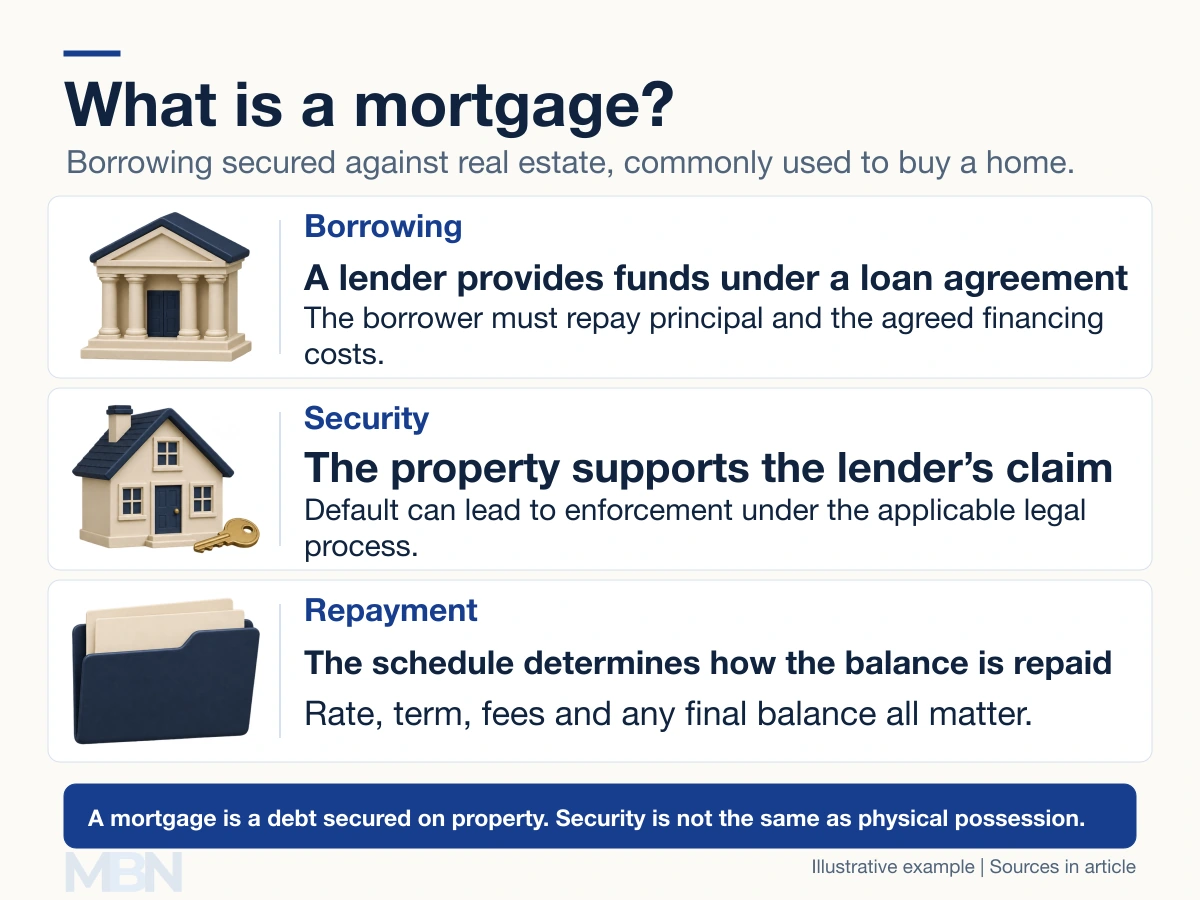
What does property security mean?
A lien is a legal claim over property used as security for an obligation. It should not be defined as the lender physically holding the home until the debt is paid. A borrower can continue living in a mortgaged home while making the required payments.
US Regulation Z treats terms such as lien and mortgage as forms of security interest for disclosure purposes. The relevant documents and legal framework determine the lender’s rights. If the borrower defaults, enforcement can result in foreclosure or repossession and sale, subject to applicable procedures and protections.
The borrower is sometimes called the mortgagor and the lender the mortgagee. A mortgage broker can arrange financing, while a servicer may collect payments and manage the account. They need not all be the same organization.
Principal, interest and other costs
Principal is the amount borrowed. Interest is the financing charge calculated under the agreement. An amortizing loan reduces principal through scheduled payments. Other structures can leave a balance due at maturity.
Canada’s Financial Consumer Agency explains mortgage principal, payment components, term and amortization. The repayment period and a shorter interest-rate deal or renewal term are not necessarily the same length.
A monthly housing bill can also include property taxes, insurance and other charges. Closing costs and lender fees are distinct from the down payment. Annual percentage rate, or APR, is a cost measure that includes relevant financing charges as well as interest.
A purchase and loan-to-value example
Suppose a fictional home has a $250,000 purchase price and the same accepted property value. The buyer contributes $50,000 and borrows $200,000. Excluding fees and other debts, initial equity is $50,000, the value remaining after subtracting the loan.
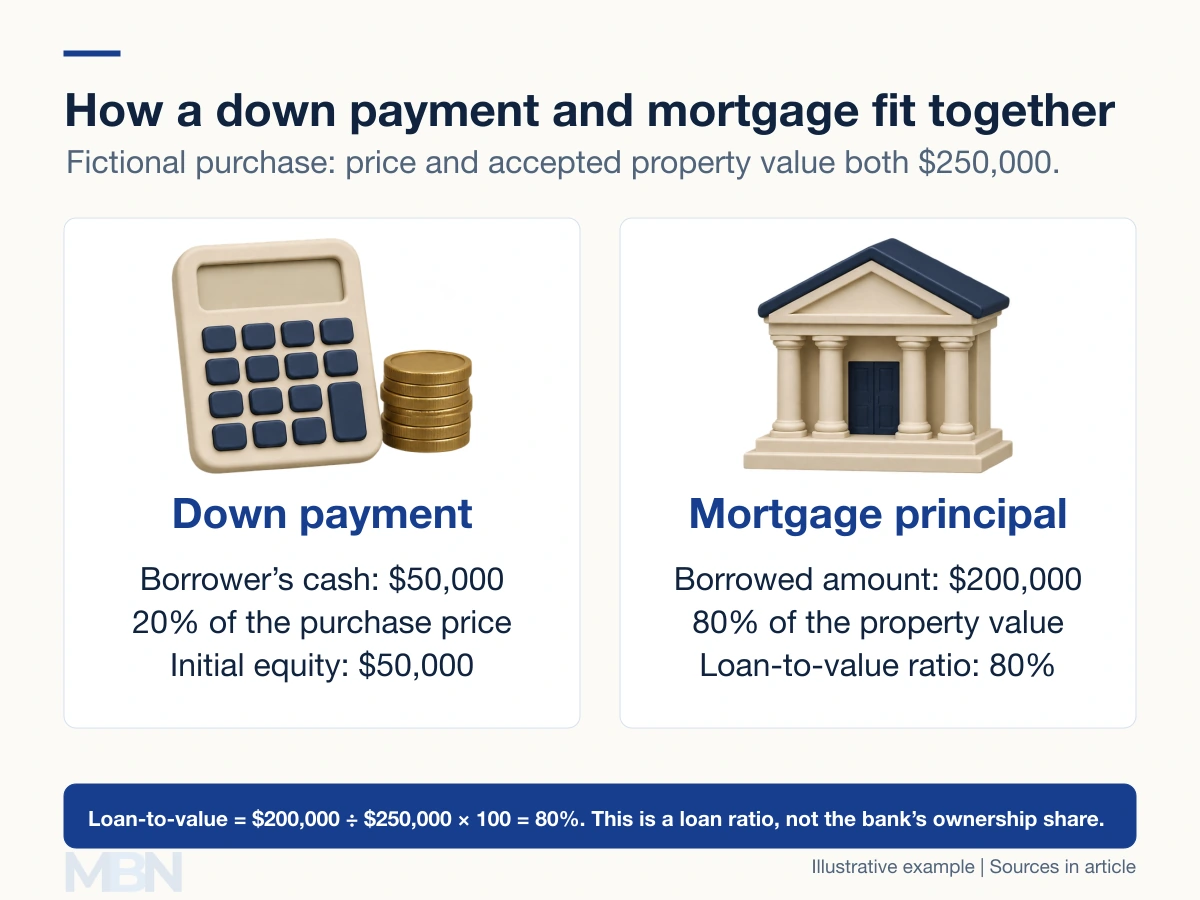
The CFPB defines loan-to-value, or LTV, by comparing the financing amount with the property’s appraised value. Here, $200,000 ÷ $250,000 gives 80%. The loan finances 80% of the value; that does not mean the bank owns 80% of the home. Other secured loans can require a separate combined-LTV assessment.
Which features can change?
A fixed-rate mortgage keeps its rate for a specified period. A variable-rate mortgage can change under its contract. A balloon mortgage leaves a large final payment. Those labels describe different features and are not complete descriptions of every loan.
Is a new physical appraisal always required?
No worldwide rule requires one for every mortgage. For eligible US loans, Fannie Mae offers value acceptance, formerly called an appraisal waiver, subject to program and lender requirements. Other loans require different valuation processes. An appraisal is also different from a buyer’s inspection of the property’s condition.
The US Closing Disclosure presents the loan terms, projected payments and closing costs for covered mortgages. The actual documents establish the debt, payment schedule and security obligations more precisely than a broad product label.
Last checked and updated on November 4, 2026 by the MBN editorial team.