
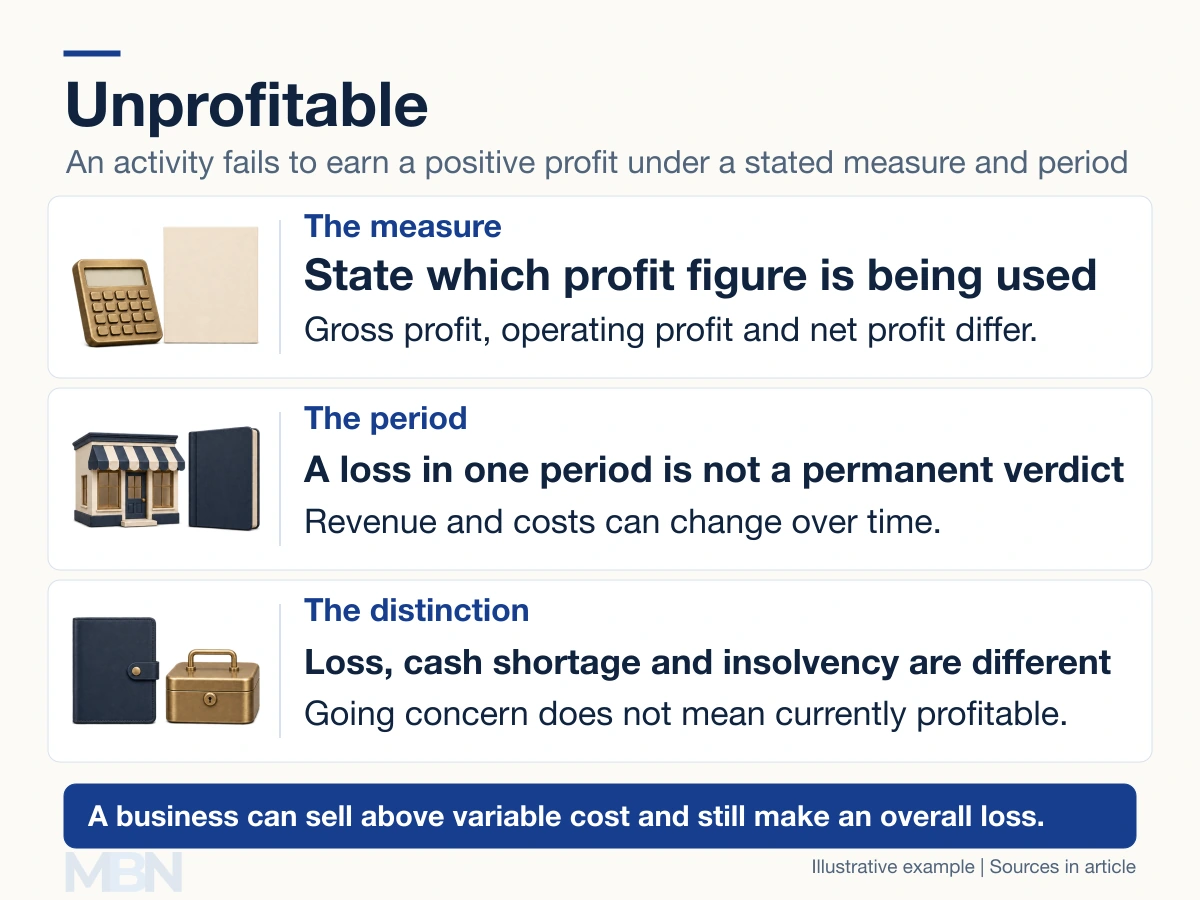
Unprofitable describes a business, product, customer relationship or project that does not earn a positive profit under the measure and period being considered. A loss means costs exceed the corresponding income. Break-even means profit is zero.
The measure matters. A business can have a positive gross profit but an operating or net loss after further expenses. It is clearer to state the actual result than to describe every form of profitability as one number.
How a sale can contribute while the business loses money
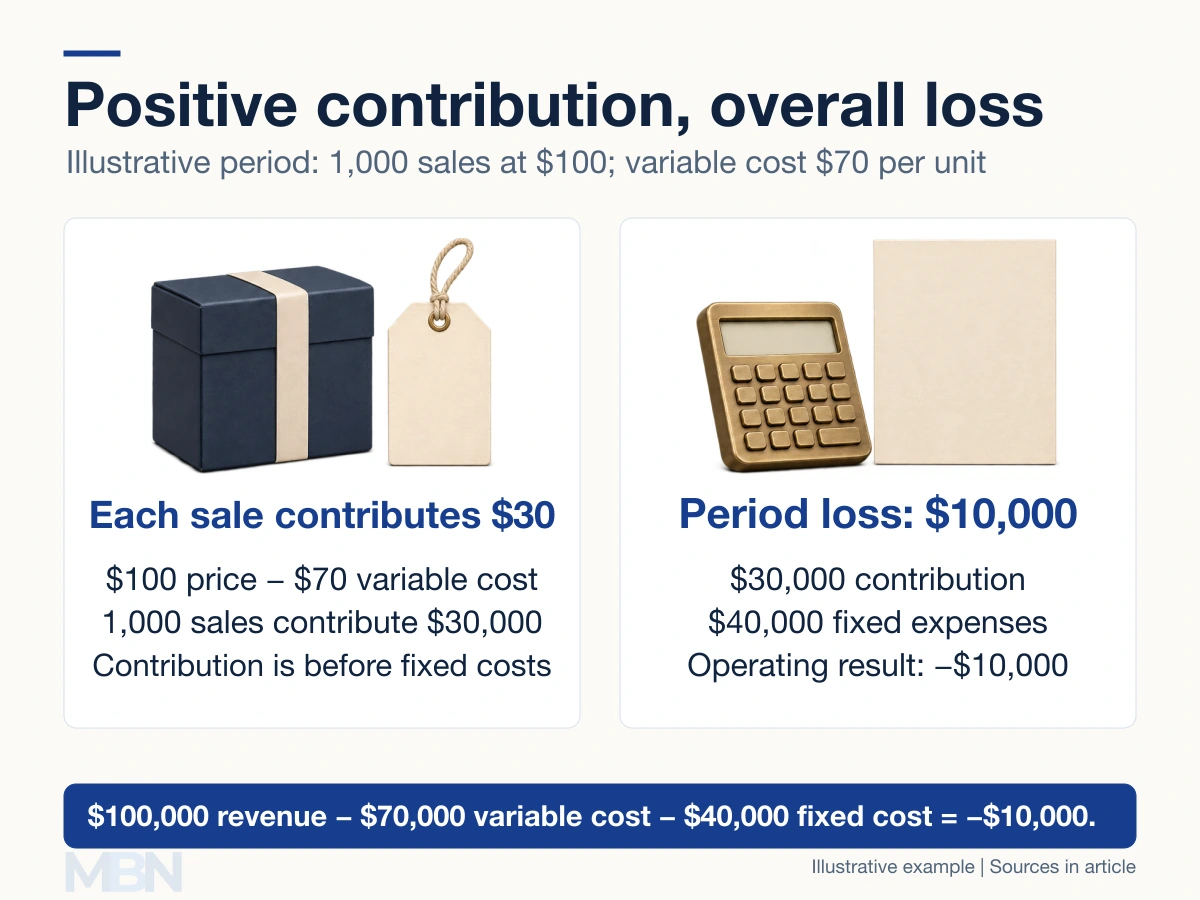
Suppose a business sells 1,000 units at $100 each. Revenue is $100,000. Variable costs are $70 per unit, or $70,000 in total, leaving $30,000 of contribution towards fixed costs.
If fixed expenses for the period are $40,000, the simplified operating result is a $10,000 loss. Each unit sells above its variable cost, but the combined contribution does not cover fixed expenses. The example excludes financing costs and taxes.
The SEC explains how revenue and expenses appear in financial statements. A reported loss should be read alongside its period, accounting policies and significant items. Economic profit can also include opportunity costs that are not expenses in the financial accounts.
Losses, cash flow and going concern
Accounting profit and cash flow differ. A profitable company may struggle to pay bills when customers have not paid. A loss-making company may still have cash from reserves, borrowing or investors.
A going concern is an entity for which continuing operations is an appropriate basis for preparing accounts. It is not a synonym for a profitable company. The IFRS Foundation’s going-concern material explains the assessment and the need to disclose material uncertainties where relevant.
Persistent losses can create financial pressure, but a loss does not automatically establish insolvency or bankruptcy. For UK companies, the Insolvency Service distinguishes inability to pay debts on time and liabilities exceeding assets. Legal procedures and terminology depend on jurisdiction and business structure.
What makes a customer or product unprofitable?
A customer relationship may cost more to supply and service than it earns over the chosen period. Relevant items can include product costs, delivery, returns, support and credit losses. The result depends partly on which costs are allocated and why.
Allocated overhead is different from a cost that would actually disappear if a customer left. For example, ending a relationship might remove delivery costs while leaving rent unchanged. Contribution and fully allocated profit therefore answer different questions.
A current loss also differs from a forecast of future value. Repeat purchases or related sales may matter, but they are uncertain and should not be assumed. Customer size, age or appearance is not evidence of profitability; the calculation requires actual revenue and relevant costs.
Last checked and updated on November 10, 2026 by the MBN editorial team.