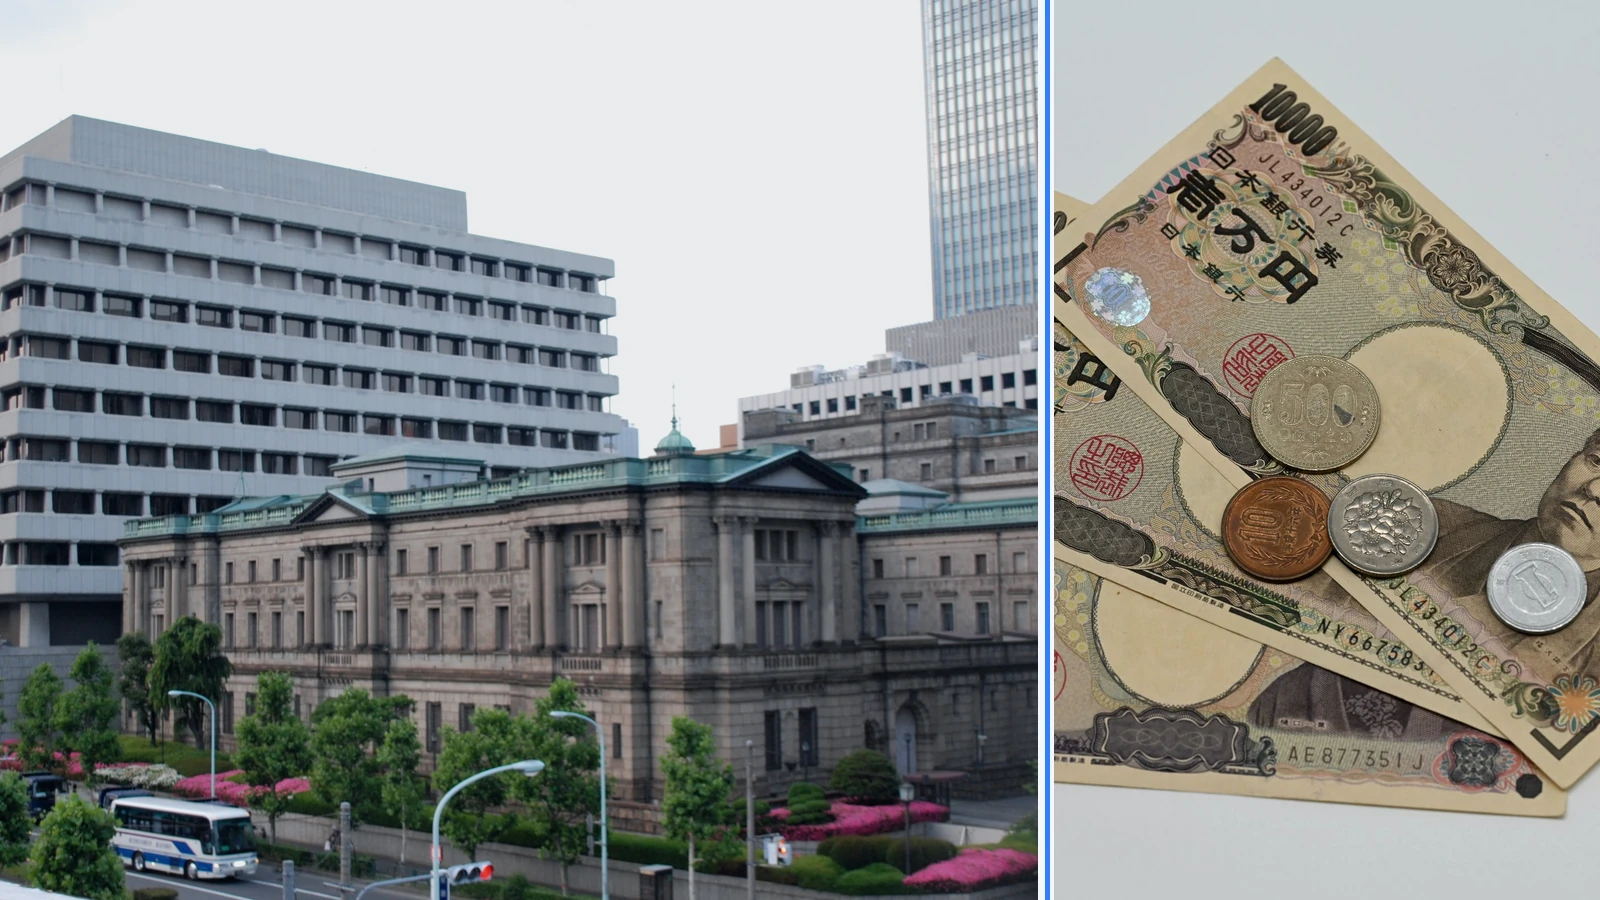
The Bank of Japan raised its policy rate by 0.25 percentage point to around 1.25%, taking its main short-term rate to its highest level in about 31 years.
The decision moves Japan further away from the exceptionally low rates used for decades to counter deflation. The Bank’s guideline now calls for the uncollateralized overnight call rate, the rate banks charge one another for overnight lending, to remain around 1.25%.
Higher policy rates can feed through to mortgage rates, business loans and savings returns, although the speed and size of those changes depend on each bank and contract. They also raise the return banks receive on some funds held at the central bank.
What the Bank changed
The Bank of Japan’s policy release set the money-market target at around 1.25%. A related notice says the interest rate on the complementary deposit facility will become 1.25% on 24 September.
The complementary deposit facility is the rate paid on certain excess reserves that financial institutions keep at the Bank of Japan. Raising it helps move very short-term market rates in line with the new policy target.
Why a 1.25% rate is notable in Japan
A 1.25% rate would be low in many economies, but Japan spent years with rates near zero or below zero while policymakers tried to lift inflation and demand. The latest move is the highest since 1995, according to reporting by Associated Press.
The Bank is weighing inflation, wages, exchange rates and overseas risks. A higher rate can curb demand over time, but it also increases borrowing costs for households and companies. Those effects are gradual and vary widely across borrowers.
What borrowers and savers should watch
Borrowers on variable-rate loans are more exposed to policy changes than borrowers who have locked in a fixed rate. Companies with large floating-rate debt may also face higher interest costs when loans reset.
Savers may receive better deposit returns, though retail rates do not automatically match the central bank’s move. The Bank’s next decisions will depend on how inflation and the economy develop, so the increase should not be read as a promise of a preset sequence of further rises.
