
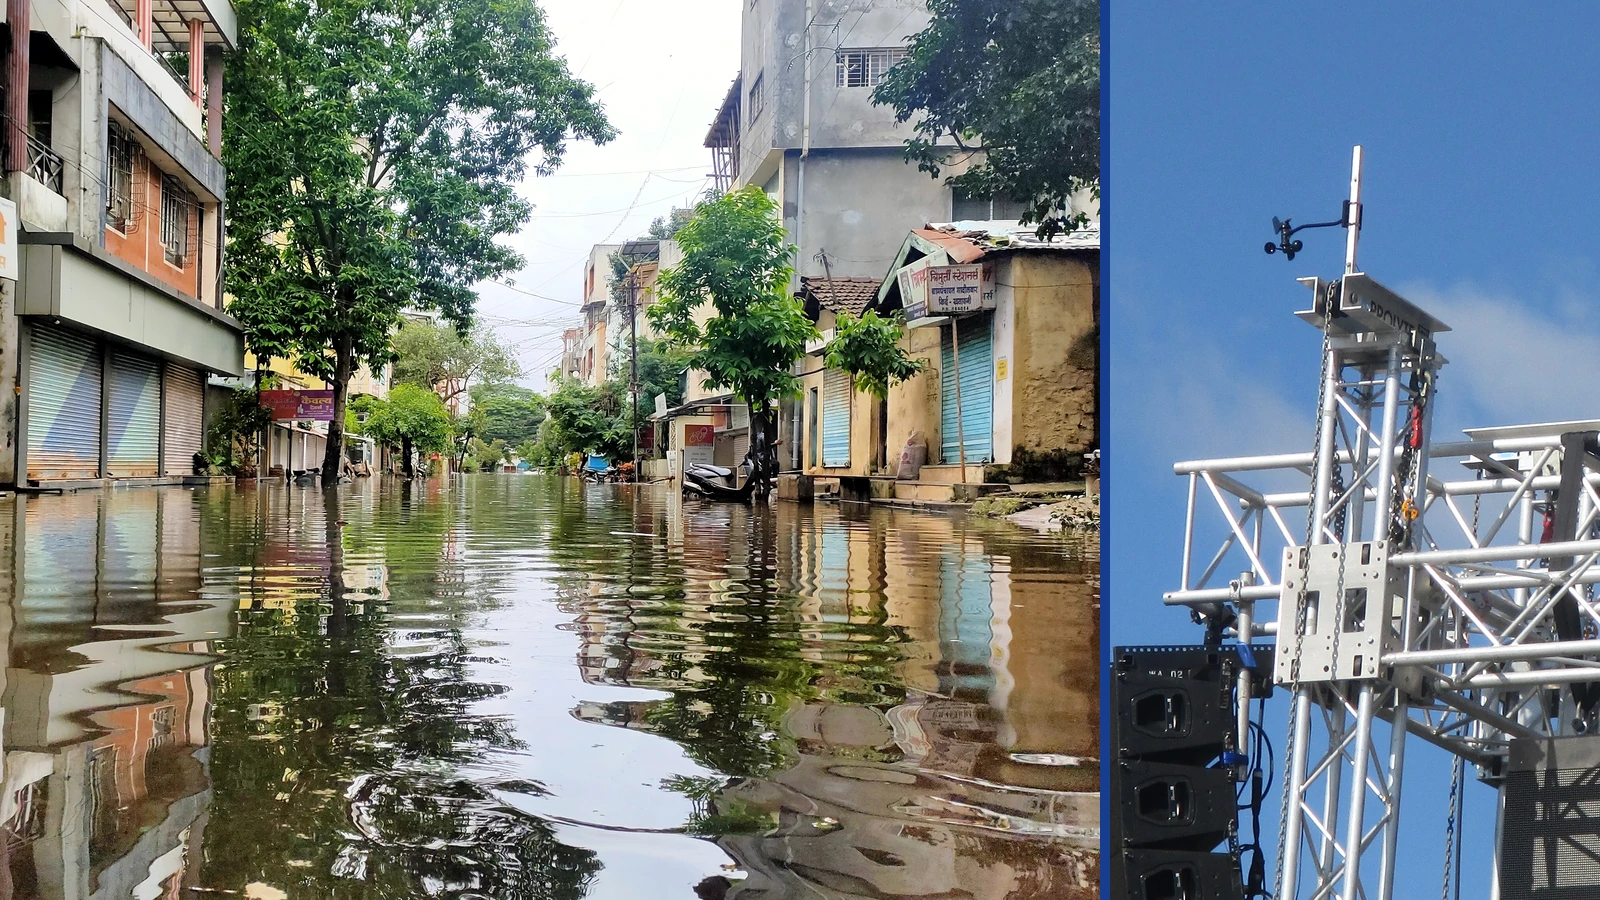
A 2026 study of 362 Italian small and medium-sized businesses identifies a central concern about parametric insurance: a disaster can cause serious losses without activating a payment. This cover ties payments to an agreed measurement, such as wind speed or rainfall, making the choice of trigger crucial.
The study, published in Research in International Business and Finance, combined questionnaire responses with secondary data from a stratified random sample, selected to represent different groups of Italian firms.
The researchers found that concerns about the gap between payments and losses remained important. Recent losses, company size, use of digital technology and access to adequate information were also associated with firms’ willingness to purchase this insurance.
Those findings describe the Italian sample. They do not establish that providing information causes businesses to buy cover, or that a particular policy will protect a company adequately.
How a measurement becomes a payment
A business buying parametric insurance pays a premium, the price of its cover, to an insurer. In return, the insurer takes on the obligation to pay under specified conditions.
The contract might use a recorded wind speed, a rainfall total or a river level. It defines the measurement, the threshold that activates payment and the amount payable. Some policies have several thresholds, with larger payments for more severe events.
Conventional indemnity insurance compensates the policyholder for an actual covered loss, subject to the contract’s limits and conditions. A claim may involve checking damaged property, repair costs and the extent of an interruption to trading.
Parametric cover uses the agreed event measurement to determine the payment instead. The US National Association of Insurance Commissioners explains that the contract should specify who independently verifies the trigger, alongside the parameter and payment.
Avoiding a detailed assessment of each policyholder’s damage can make money available sooner. That matters when a business needs temporary premises, replacement stock or funds to continue paying staff.
Faster does not mean instant. The event data must become available and the contract’s conditions must be met. Some jurisdictions also require evidence that a loss occurred.
Why the trigger can miss the loss
The mismatch between the payment and the actual loss is called basis risk. It can leave a business with too little money, including no payment at all. A payment can also exceed the loss suffered.
Consider a hypothetical business with drought cover based on rainfall at a named weather station. Its operations could suffer from a water shortage even though rainfall at that station stays just above the policy’s threshold.
The business has lost money, but the agreed trigger has not been reached. Local conditions, the period being measured and the firm’s dependence on water can all affect how well that measurement represents its exposure.
A report by authors at the Financial Stability Institute and the International Association of Insurance Supervisors examines these design choices. Data quality, geographical coverage and the relationship between the measurement and losses affect whether a product provides useful protection.
More detailed observations can help, but a reliable measurement of the weather is not necessarily a reliable measurement of one company’s financial damage.
Researchers Markus Johannes Maier and Matthias Scherer examined ways to design payments around that difference in a 2026 European Actuarial Journal paper. Their mathematical framework allows greater weight to be placed on avoiding underpayment than overpayment.
This is research into payment design. It does not establish that a commercial policy can eliminate the mismatch for every business or disaster.
A hurricane payout for a Mexican reef
One operating example comes from Quintana Roo, Mexico, where insurance was arranged to fund repairs to coral reefs and beaches following hurricanes. Reefs help reduce wave energy, protecting coastal areas that support the tourism economy.
The Nature Conservancy says it partnered with the state to create the policy in 2019. When Hurricane Delta struck in 2020, the cover paid nearly US$850,000 to support restoration, according to the organisation’s account of the programme.
The payment depended on the hurricane’s wind trigger, rather than a full valuation of damage to individual sections of reef. It illustrates how an agreed event can release funds for a defined response.
It is also a different arrangement from insuring a shop or factory. The payout does not show that the same trigger would meet the needs of every business along that coast.
Where the cover fits in disaster planning
Parametric insurance can sit alongside conventional cover, supplying money while claims requiring individual assessment proceed. It does not remove the cost of the disaster or make every exposed property affordable to insure.
In a review published on 30 September, actuaries Hansjörg Albrecher and Stéphane Loisel examine why climate-related risks strain insurance. Changing hazards and exposure complicate estimates, while one catastrophe can generate losses across many policyholders simultaneously.
Choosing a policy therefore means comparing the protection with the business’s needs, not only comparing premiums. Our earlier coverage of commercial insurance pricing explains why broad market averages can conceal substantial differences between individual risks.
A business considering parametric cover needs to know which location and period are measured, who supplies the data, and what happens if that source fails. It also needs the payment schedule and any remaining evidence requirements.
Testing possible loss scenarios against those terms can expose gaps before purchase. A plan should account for disruption that falls outside the trigger, using other insurance, available cash or changes to operations where appropriate.
The emergency plan still needs arrangements for suppliers, premises, staff and repairs. A payment becomes useful when the business has already worked out how to put it to work.
