Mistras Group has agreed to be acquired by affiliates of H.I.G. Capital for $20.35 a share in cash, a transaction the industrial inspection company says has an enterprise value of about $866 million.
The board has unanimously approved the deal, which is expected to close in late 2026 or early 2027 if shareholders and regulators approve it. Enterprise value includes a company’s debt as well as its equity value, so it is different from the cash price paid for each share.
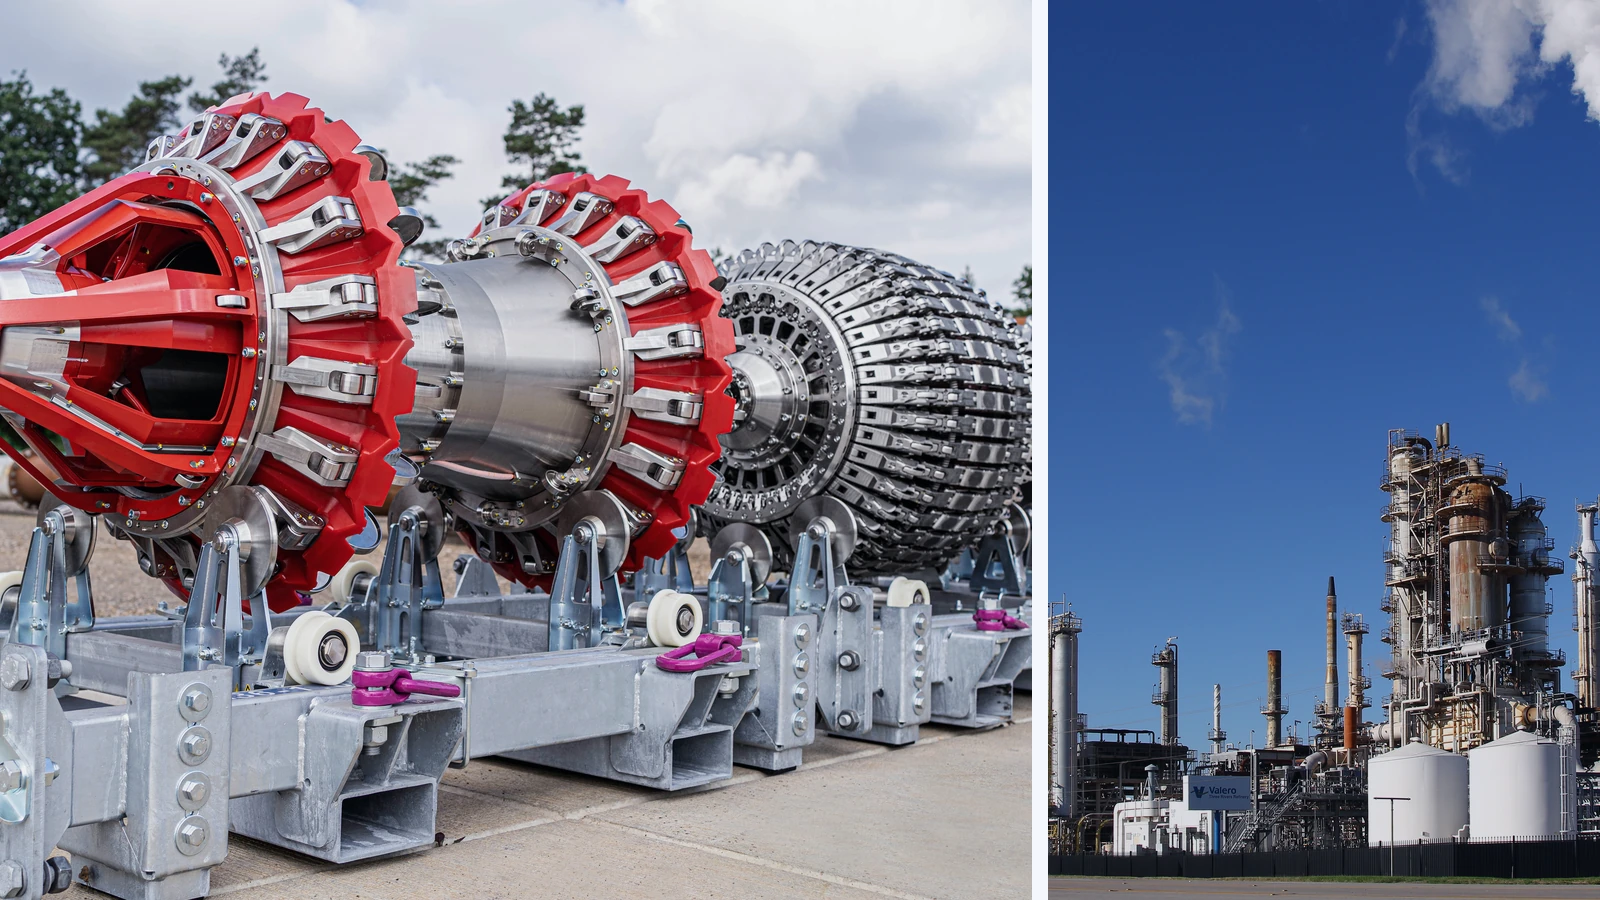
Mistras provides non-destructive testing, condition monitoring and laboratory services to customers in energy, aerospace, infrastructure and other industrial markets. Its work is designed to help operators inspect equipment and plan maintenance without taking every asset apart.
Shareholders would receive $20.35 a share
Under the agreement, Mistras shareholders would receive cash for each common share. The company said the price represented premiums of about 8% and 13% to its 30-day and 90-day volume-weighted average share prices through 17 September.
A volume-weighted average gives greater influence to days when more shares traded. It is one way companies describe the offered premium without relying on the share price from one particular day.
The purchase agreement is not a completed sale. Mistras said it still needs shareholder approval and required regulatory clearances. If it closes, Mistras shares would no longer be listed on the New York Stock Exchange.
The agreement includes a 40-day go-shop period
Mistras can actively solicit and consider alternative proposals until 27 October under a 40-day go-shop provision. The board may accept a superior proposal, subject to the terms of its agreement with H.I.G., including a termination fee.
H.I.G. affiliates have voting and support agreements with holders of about 31% of Mistras common stock, the company said. Those arrangements commit the named shareholders to support the deal, but do not replace the wider shareholder vote.
Why an asset-inspection business attracted a buyer
Mistras sells services that sit close to customers’ ongoing operations: pipeline inspections, materials testing, real-time monitoring and maintenance planning. Demand can be linked to safety requirements, aging equipment and the cost of unplanned outages, rather than a single construction cycle.
In its announcement, Mistras said H.I.G. would provide resources for further investment. That is management’s view. The nearer-term issues for investors are the proxy vote, any competing bid during the go-shop period and the conditions attached to closing.
