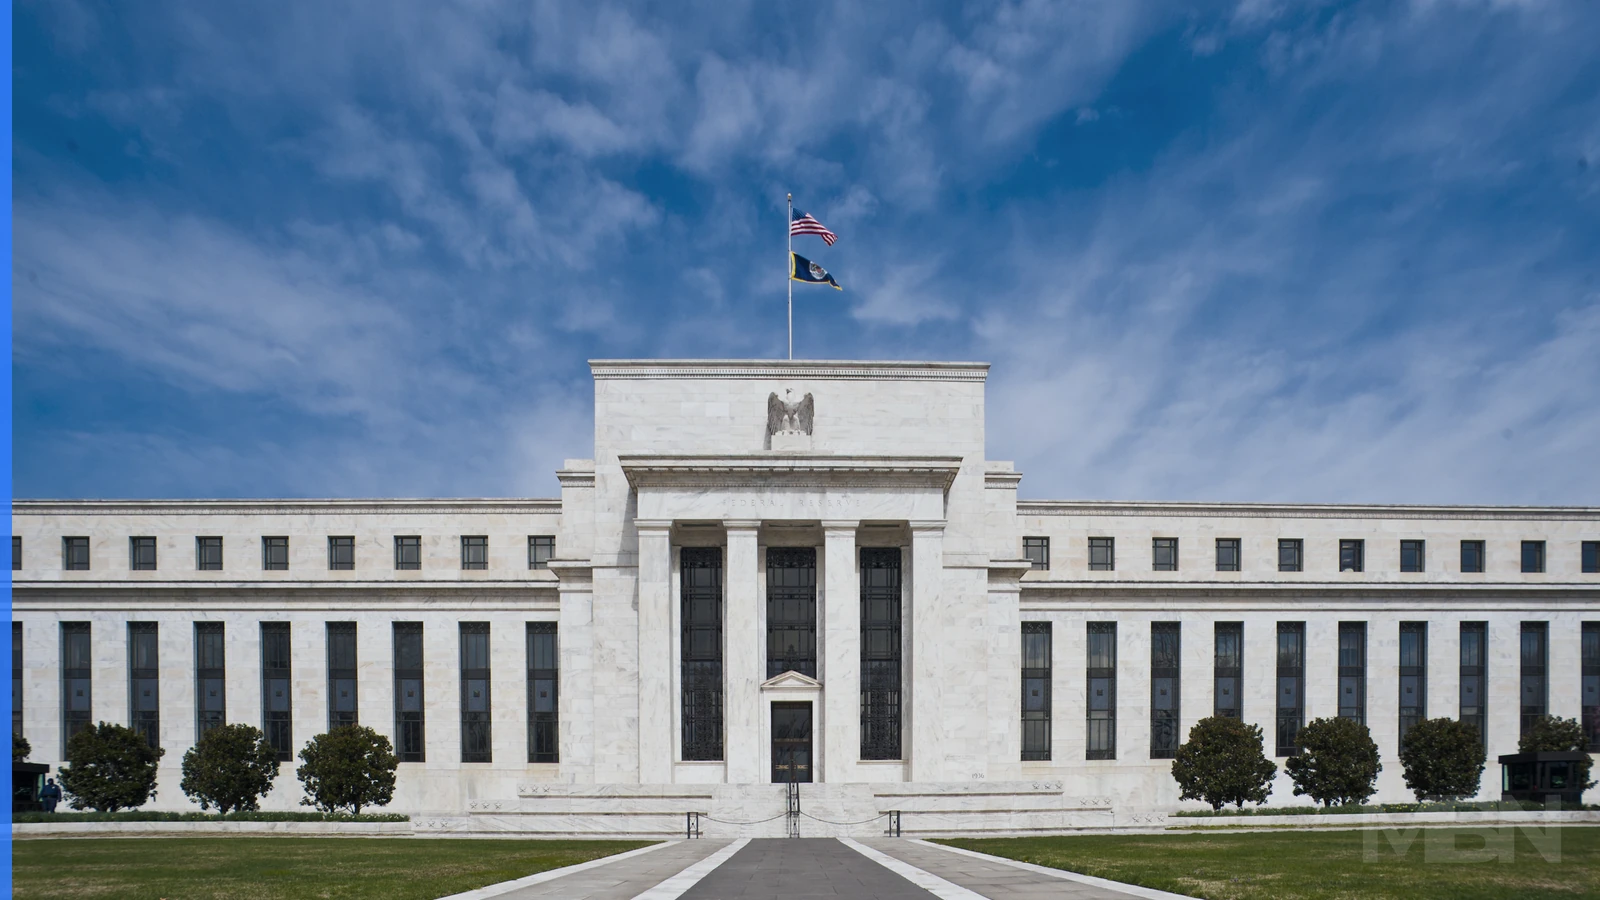
The Federal Reserve raised its target range for the federal funds rate by a quarter of a percentage point to 3.75% to 4.00%, its first increase since 2023. The unanimous decision reflects an assessment that inflation remains too high even as economic activity and employment have held up.
The rate is the interest rate banks charge one another for overnight lending. It influences, rather than directly sets, the borrowing costs households and businesses face on products such as mortgages, credit cards and business loans.
In its September 16 statement, the Federal Open Market Committee said domestic spending had remained resilient, productivity growth was strong and job gains had kept pace with the workforce. It also said inflation remained elevated and that the increase would support a timely return to its 2% goal.
Why the Fed raised rates
Higher policy rates usually cool demand by making borrowing more expensive and saving more attractive. That can ease pressure on prices, but it also works with a delay and can weigh on investment and consumption. The Fed’s legal mandate requires it to pursue maximum employment and stable prices, so the committee must judge both sides of that balance.
The latest US consumer-price figures underscored the difficulty. As we reported last week, consumer prices rose 0.4% in August, with gasoline accounting for more than a third of the monthly increase. The annual CPI rate was unchanged at 3.4%.
The Fed does not target the Consumer Price Index directly. Its 2% objective is based on the Personal Consumption Expenditures price index, which differs in coverage and weighting. But the CPI remains an important timely signal about pressures facing households and businesses.
The new rate range is not a forecast
The committee also released its quarterly Summary of Economic Projections, which sets out participants’ individual views on growth, unemployment, inflation and appropriate policy. The figures are not a promise or a single institutional forecast. They are conditional judgements made under each participant’s assumptions.
That distinction is important because the Fed left no automatic path for rates. Its statement did not say that another increase was certain. Instead, it pointed to elevated uncertainty, including geopolitical developments, while saying future decisions would be guided by incoming data and the outlook.
The change is nevertheless immediate for financial markets. The interest rate paid on reserve balances will rise to 3.90% on September 17, according to the Fed’s implementation note. This is one of the operational rates the central bank uses to keep its policy rate within the new target range.
What it means for households, companies and the wider economy
Borrowers will not all see the same change at the same time. Variable-rate borrowing can react relatively quickly, while fixed-rate loans only change when a borrower takes a new loan or refinances. Loan pricing also depends on credit risk, competition between lenders and longer-term market yields, so a quarter-point move by the Fed does not mechanically produce a quarter-point change in every borrowing rate.
For companies, a higher policy rate can increase the cost of working capital, acquisitions and refinancing. The impact is greatest for firms with large near-term funding needs or debt whose interest rate resets frequently. Companies with long-dated fixed-rate bonds may see little immediate effect on their existing interest payments, though new borrowing can still become more expensive.
The decision also matters beyond the United States. Dollar interest rates form a benchmark for global finance. Higher Treasury yields can pull up borrowing costs elsewhere, even when a country’s own credit risk improves. Our recent report on developing-country debt explains how a rise in advanced-economy yields can offset a fall in the extra premium investors charge individual borrowers.
The immediate outcome is clear: the Fed has raised its policy range to 3.75% to 4.00%. The harder question is whether inflation will ease without a material weakening in activity or employment. The answer will depend on the data over the coming months, including consumer prices, wages, spending and the effects of higher energy costs.
