
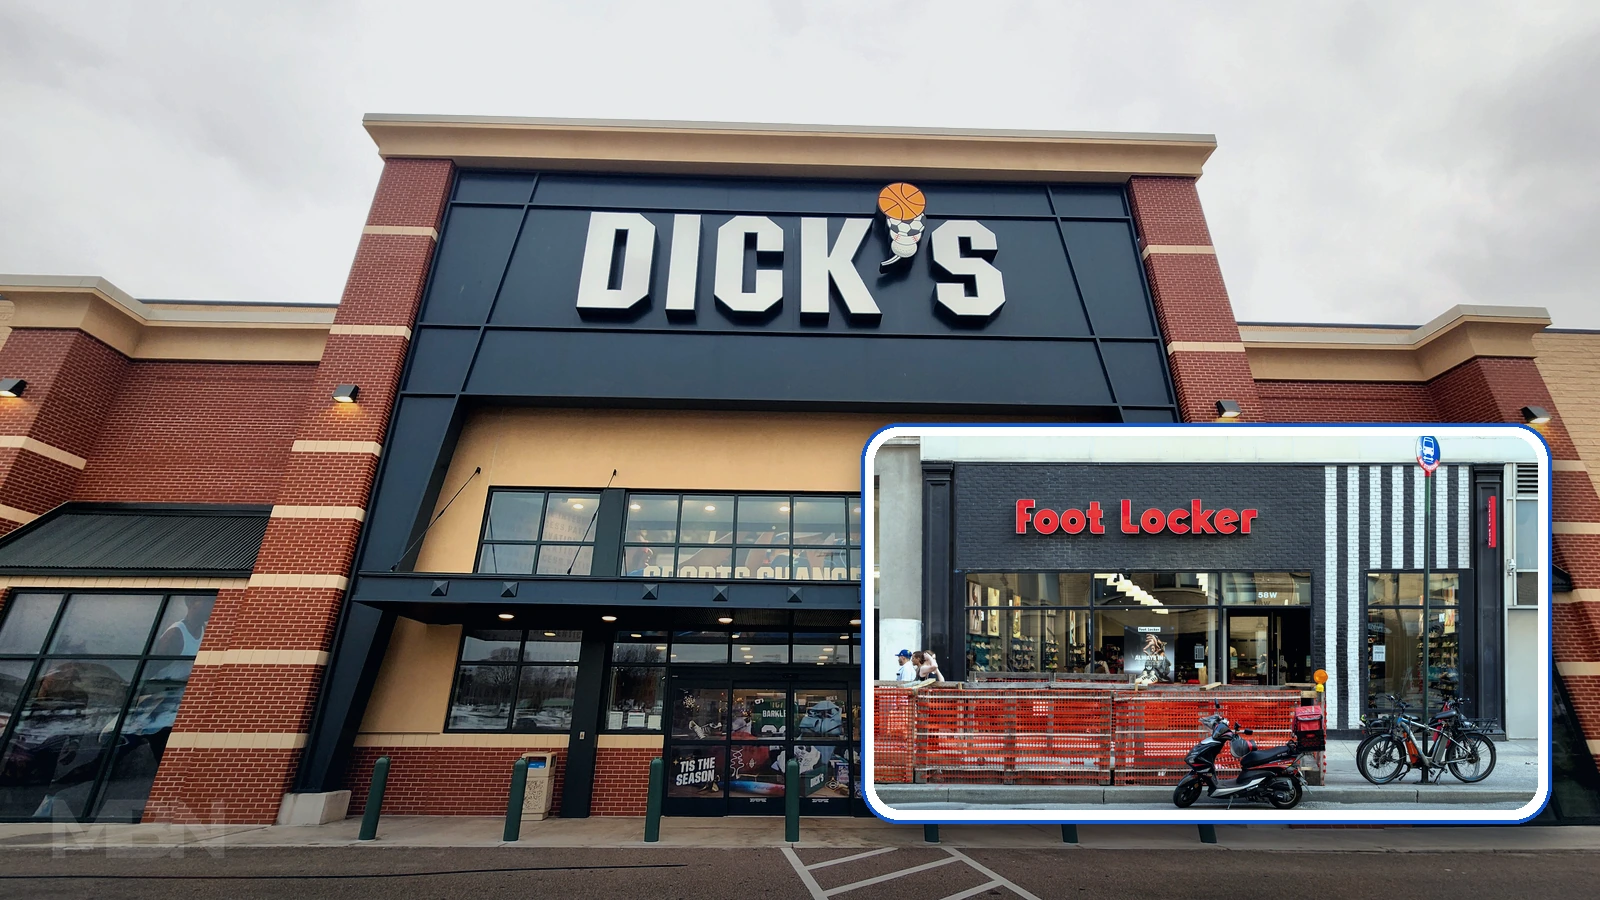
DICK’S Sporting Goods lowered its 2026 profit outlook after weaker product launches and heavier discounting hurt the recently acquired Foot Locker business.
Net sales reached $5.59 billion in the 13 weeks ended August 1, up 53.2% from $3.65 billion a year earlier, according to the company’s second-quarter earnings release.
That increase needs context. The latest quarter includes $1.74 billion of Foot Locker sales, while the prior-year comparison contained only the original DICK’S business. Nearly nine-tenths of the $1.94 billion increase therefore came from adding Foot Locker to the consolidated accounts.
Profit moved in the opposite direction. Net income fell 17% to $315 million, while diluted earnings declined to $3.50 a share from $4.71. Adjusted earnings were $3.53 a share.
Reuters reported that revenue and adjusted earnings missed LSEG estimates of $5.65 billion and $3.76 a share.
Foot Locker weakens the consolidated result
The original DICK’S business performed considerably better than the acquired chain. Its sales rose 5.6% to $3.85 billion, comparable sales increased 4.9%, and segment profit grew 2.2% to $485.2 million.
Comparable sales measure performance at established stores and digital channels, removing much of the effect of adding locations. Foot Locker’s comparable sales are shown on a pro forma basis, meaning the calculation treats the chain as though DICK’S had owned it in both periods.
On that basis, Foot Locker’s comparable sales fell 3.6%. The segment recorded a loss of $31.9 million for the quarter.
Executive Chairman Ed Stack said parts of the athletic footwear and apparel market became increasingly promotional. Foot Locker was more exposed to older footwear styles and depended more heavily on new launches and retro products.
“Not only were there fewer launches in the second quarter, but those launches performed below both industry and our expectations,” Stack said.
The distinction is important. DICK’S did not report broad weakness across the whole company. Its established business continued to grow, helped by higher transaction numbers, a larger average purchase and demand connected with the 2026 FIFA World Cup. The pressure was concentrated more heavily inside Foot Locker and the footwear categories on which it depends.
The bigger warning is in profit, not sales
DICK’S now expects full-year net sales of $21.9 billion to $22.2 billion, down from its previous forecast of $22.1 billion to $22.4 billion. Adjusted earnings guidance fell much more sharply, from $13.50 to $14.50 a share to $11 to $12.
The midpoint of the sales forecast declined by less than 1%, while the midpoint of adjusted earnings guidance fell by about 18%. That gap shows why the quarter is more a margin story than a revenue story.
Operating margin fell to 7.9% from 12.4%. A margin measures how much operating profit a company retains from each dollar of sales. The 4.51-percentage-point decline means the larger combined company converted substantially less of its revenue into operating profit.
DICK’S maintained its comparable-sales forecast of 2.5% to 4% growth for the original business. It cut Foot Locker’s pro forma comparable-sales outlook to a decline of as much as 2%, from an earlier forecast of 1.5% to 3% growth. It now expects Foot Locker to post a full-year segment loss of $40 million to $80 million.
The result contrasts with BJ’s Wholesale Club, which recently raised its profit outlook after reporting higher sales, operating income and membership revenue. The two retailers have different formats and merchandise mixes, but their results show why a large sales increase alone says little about the health of a retail quarter.
For DICK’S, the practical test is now whether Foot Locker can reduce promotions, improve comparable sales and return to segment profitability. Until then, the acquisition can make consolidated sales look much larger without providing the earnings contribution investors expected.
